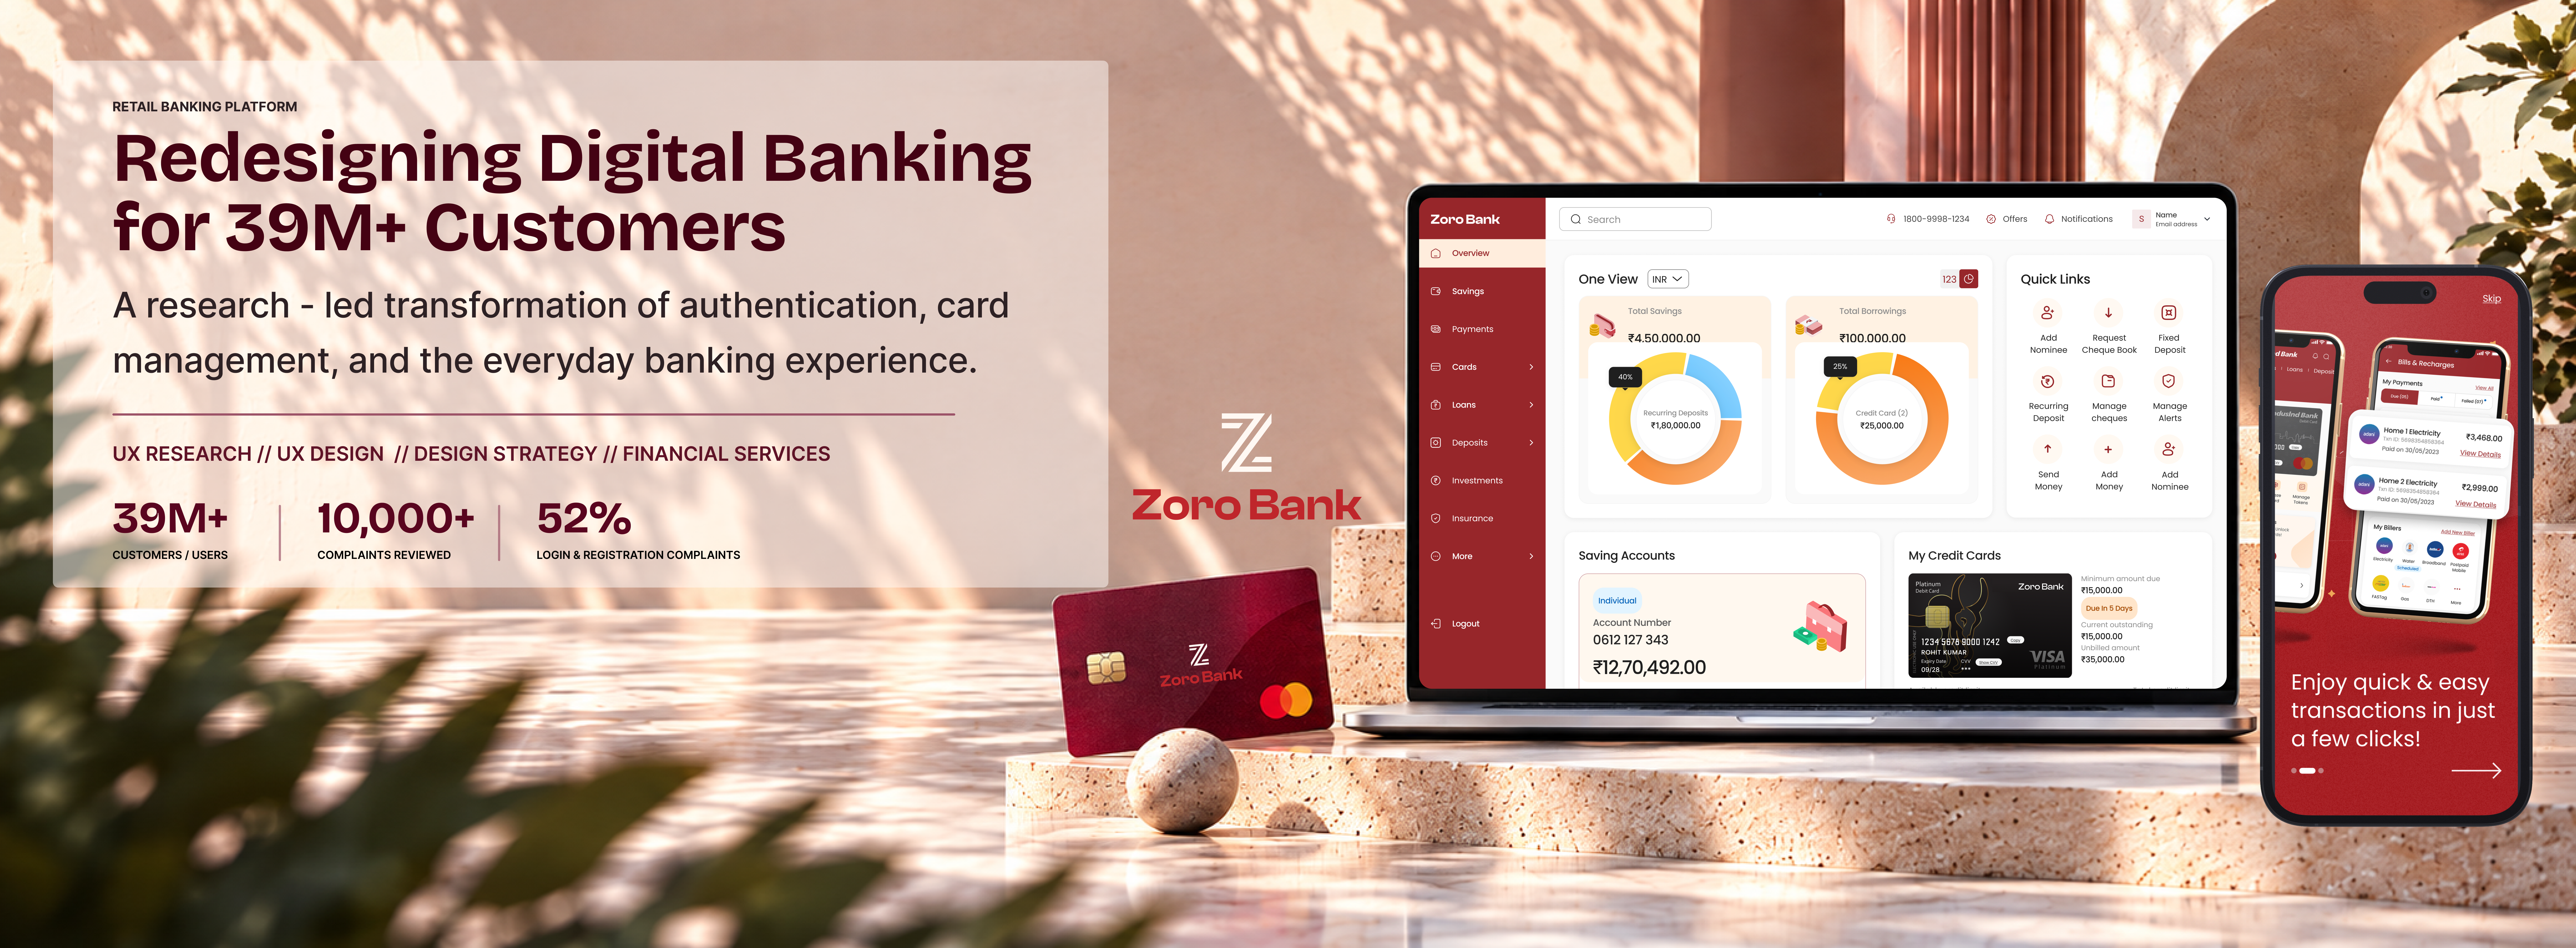
Redesigning Digital Banking for 39M+ Users
A research-led transformation of authentication, card management, dashboard, and the everyday banking experience.
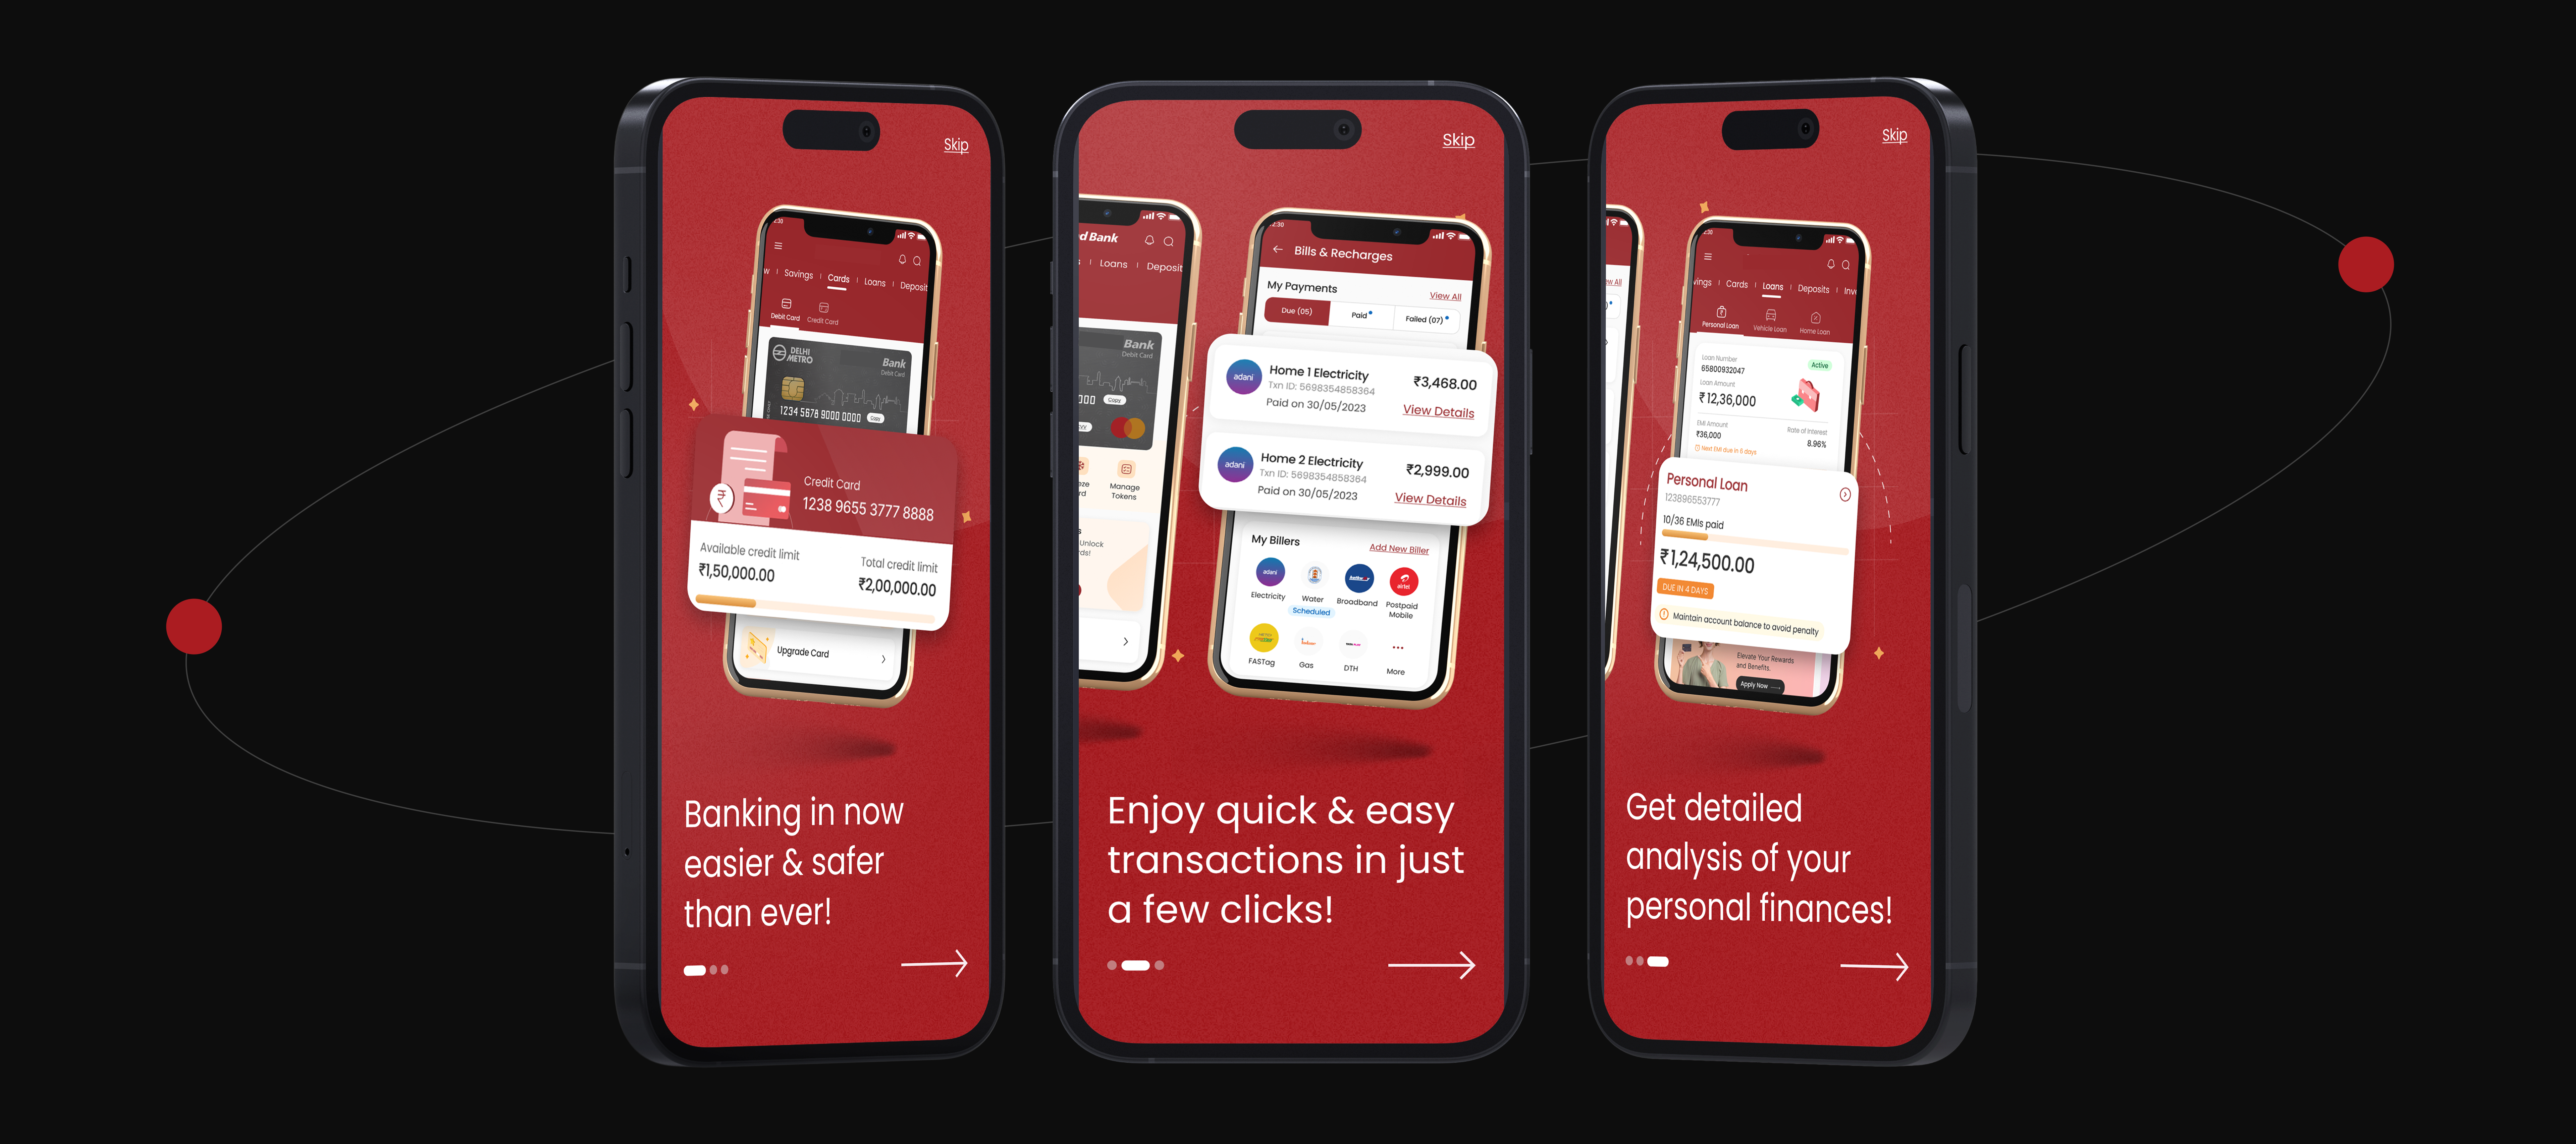
As a Design Consultant at Deloitte Digital, I led UX research and design for Pod 1, owning login and registration
and debit and credit card management, while co-designing the dashboard.
I also contributed to research across the broader banking platform, using evidence to frame problems, guide
product direction, and inform design decisions.
The client has been anonymized as Zoro Bank. Some details have been altered or omitted for confidentiality.
01 The Challenge
One bank, Multiple disconnected experiences.
Customers moved between separate experiences for everyday banking, cards, loans, investments, and insurance, each with different navigation patterns and points of friction. What appeared to be one bank from the outside often behaved like several separate digital products on the inside.
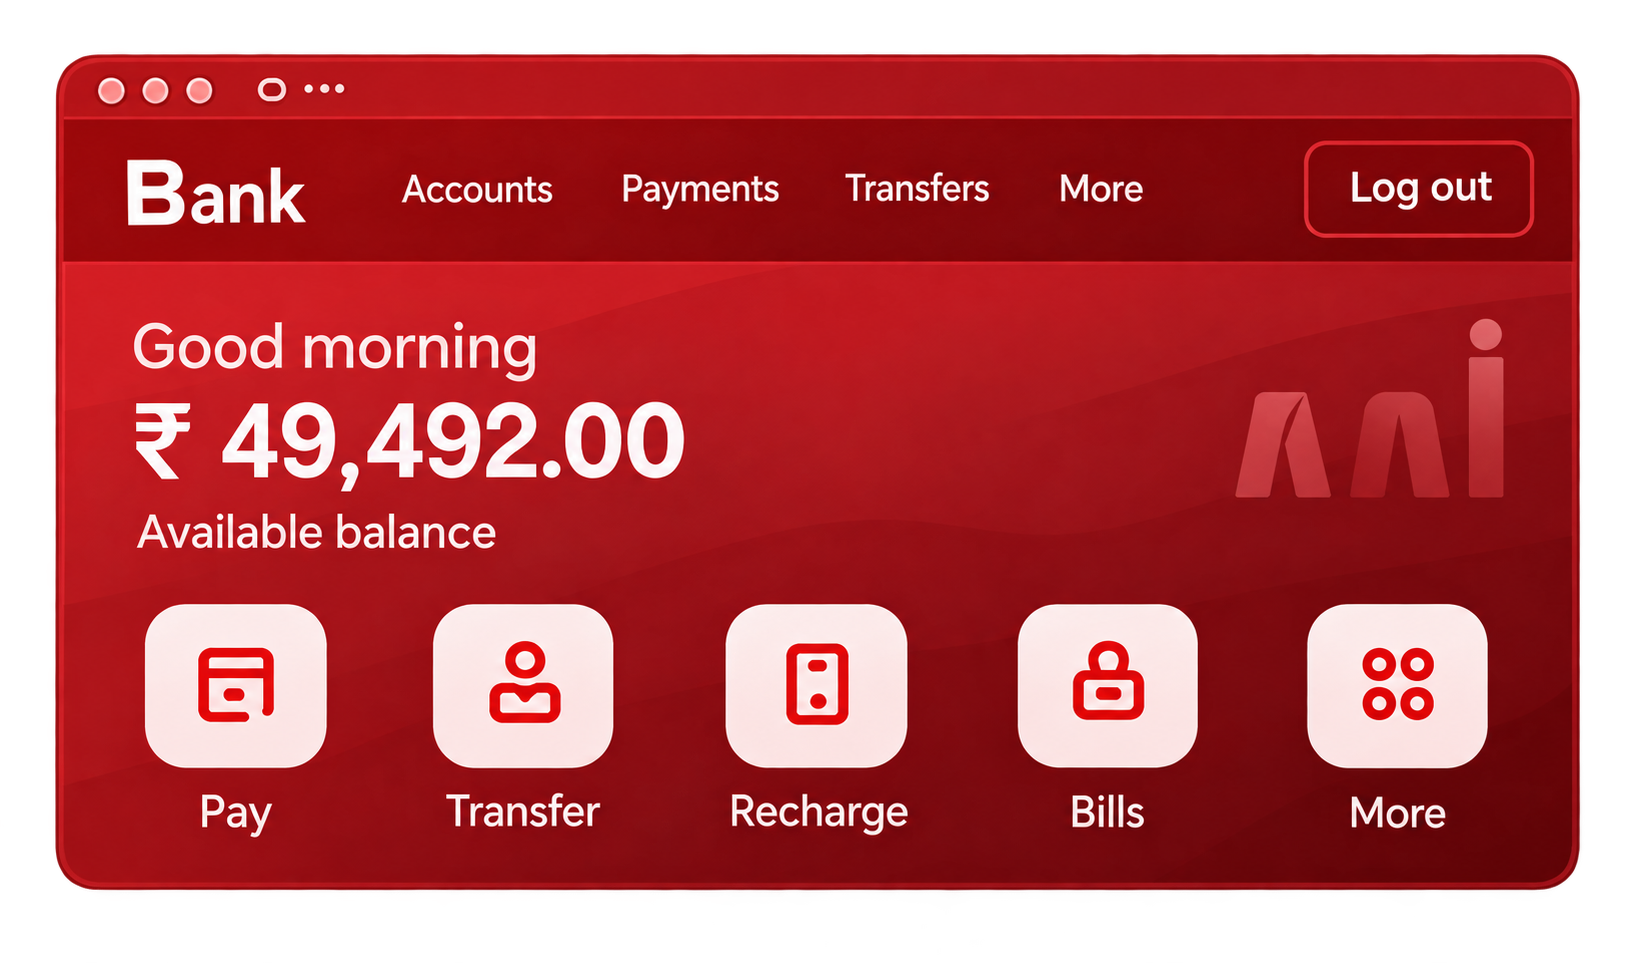
Customers were struggling
before they could even reach
the rest of the banking experience.
DESIGN PROBLEM
Every simplification had to work within multiple constraints, making the problem more complex than just the interface.
SECURITY
Protecting customer data and preventing fraud.
REGULATION
Meeting strict banking and compliance requirements.
TECHNICAL CONSTRAINTS
Working within existing systems and infrastructure.
ESTABLISHED BEHAVIOR
Respecting mental models and usage patterns.
BUSINESS PRIORITIES
Supporting product growth and commercial goals.
How might we make digital banking easier to use without compromising the trust and control customers expect from a bank?
02 Research & Strategy
Research that changed product direction
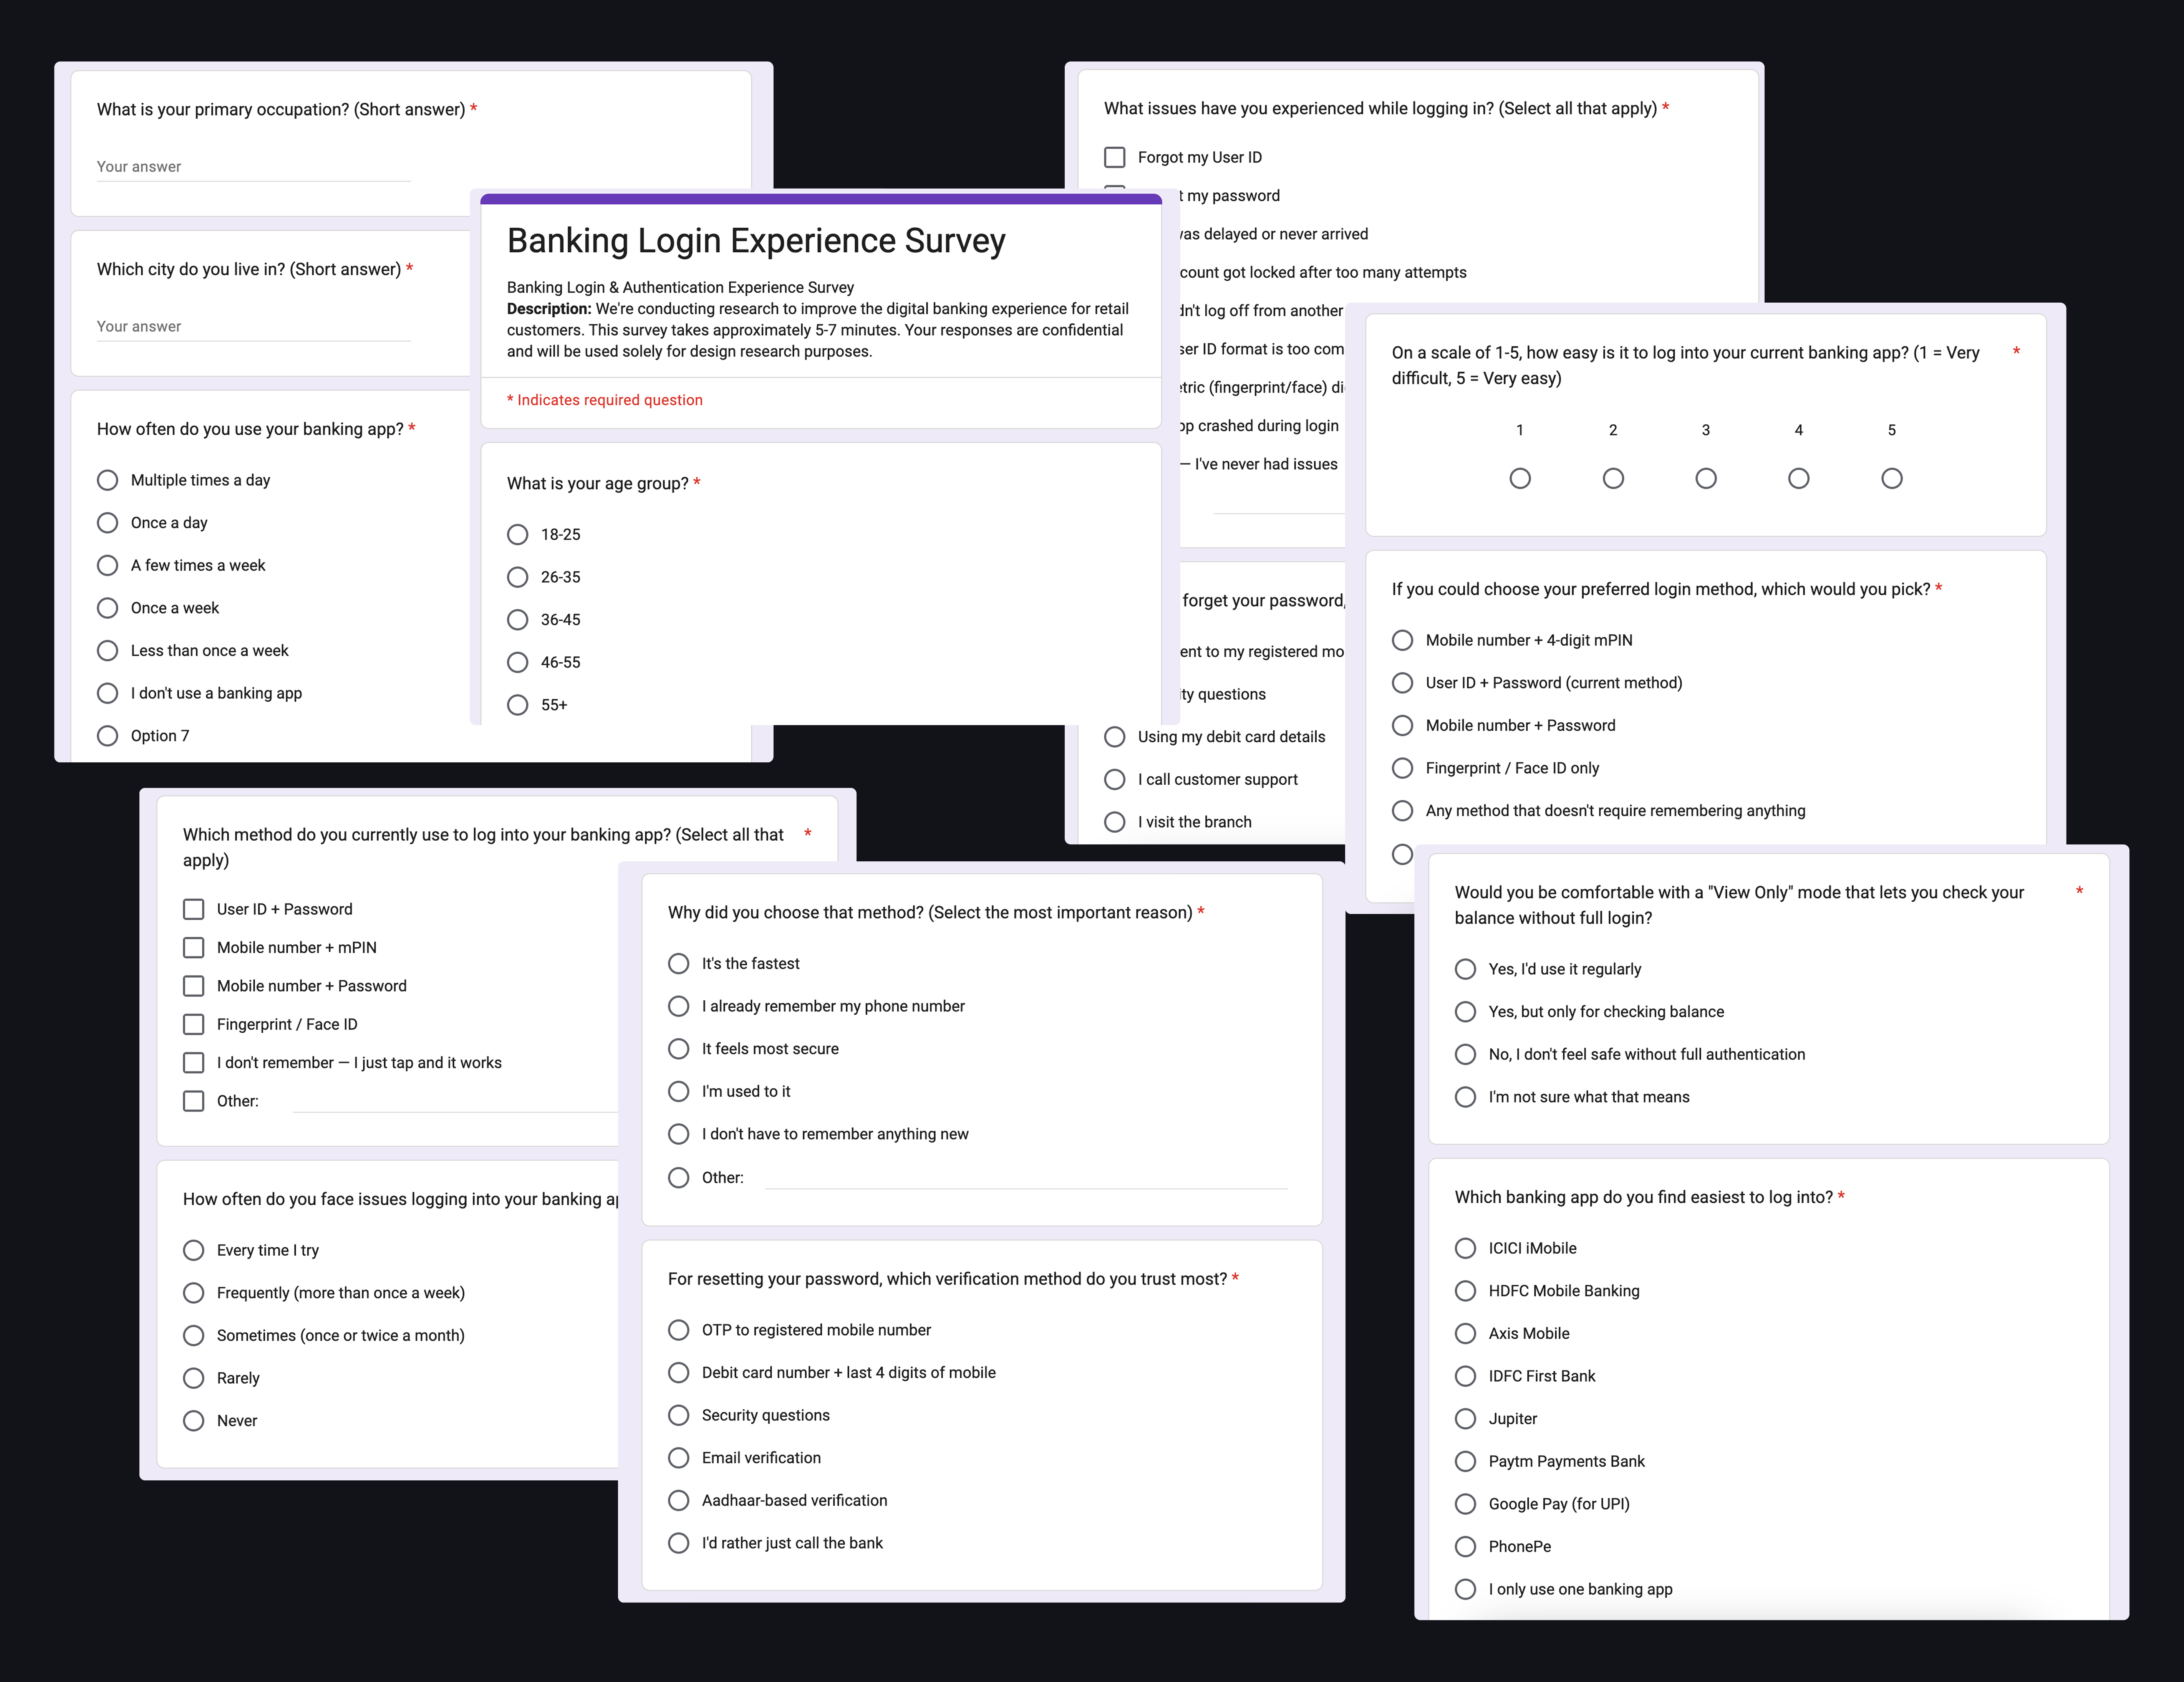
Research ran throughout the engagement. We combined multiple methods
to understand behavior, friction, and decision-making across the banking journey.
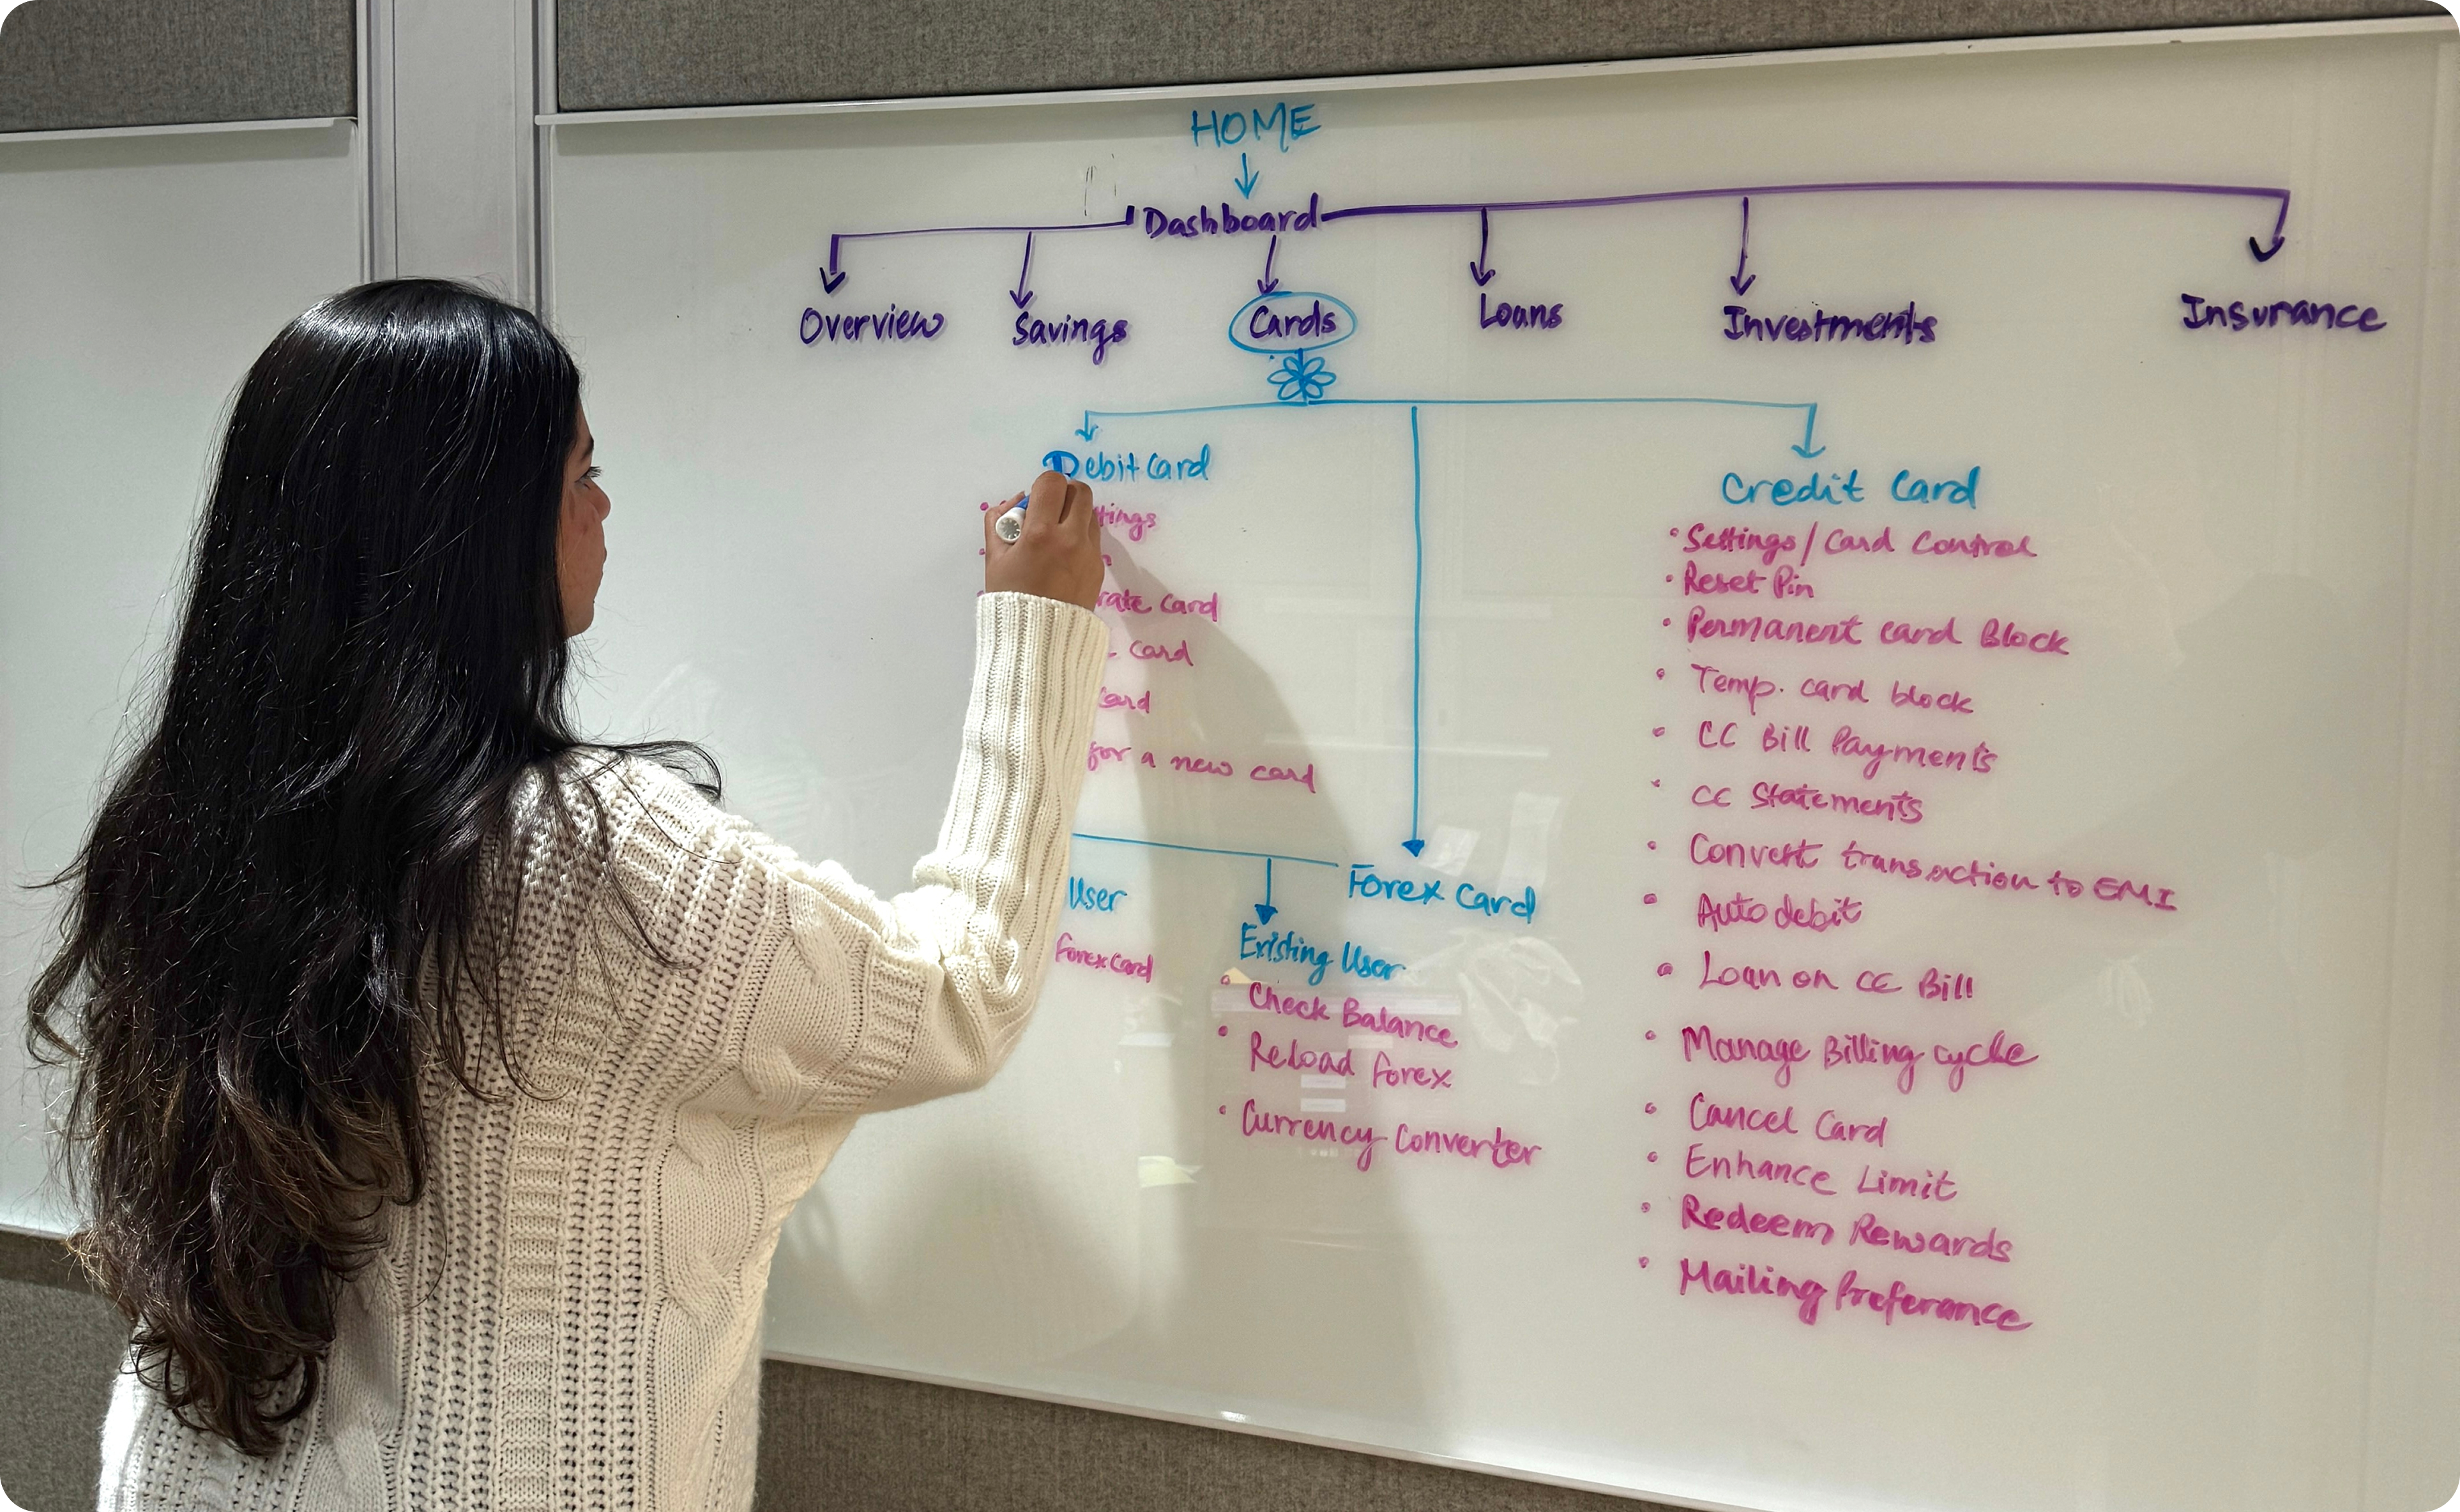
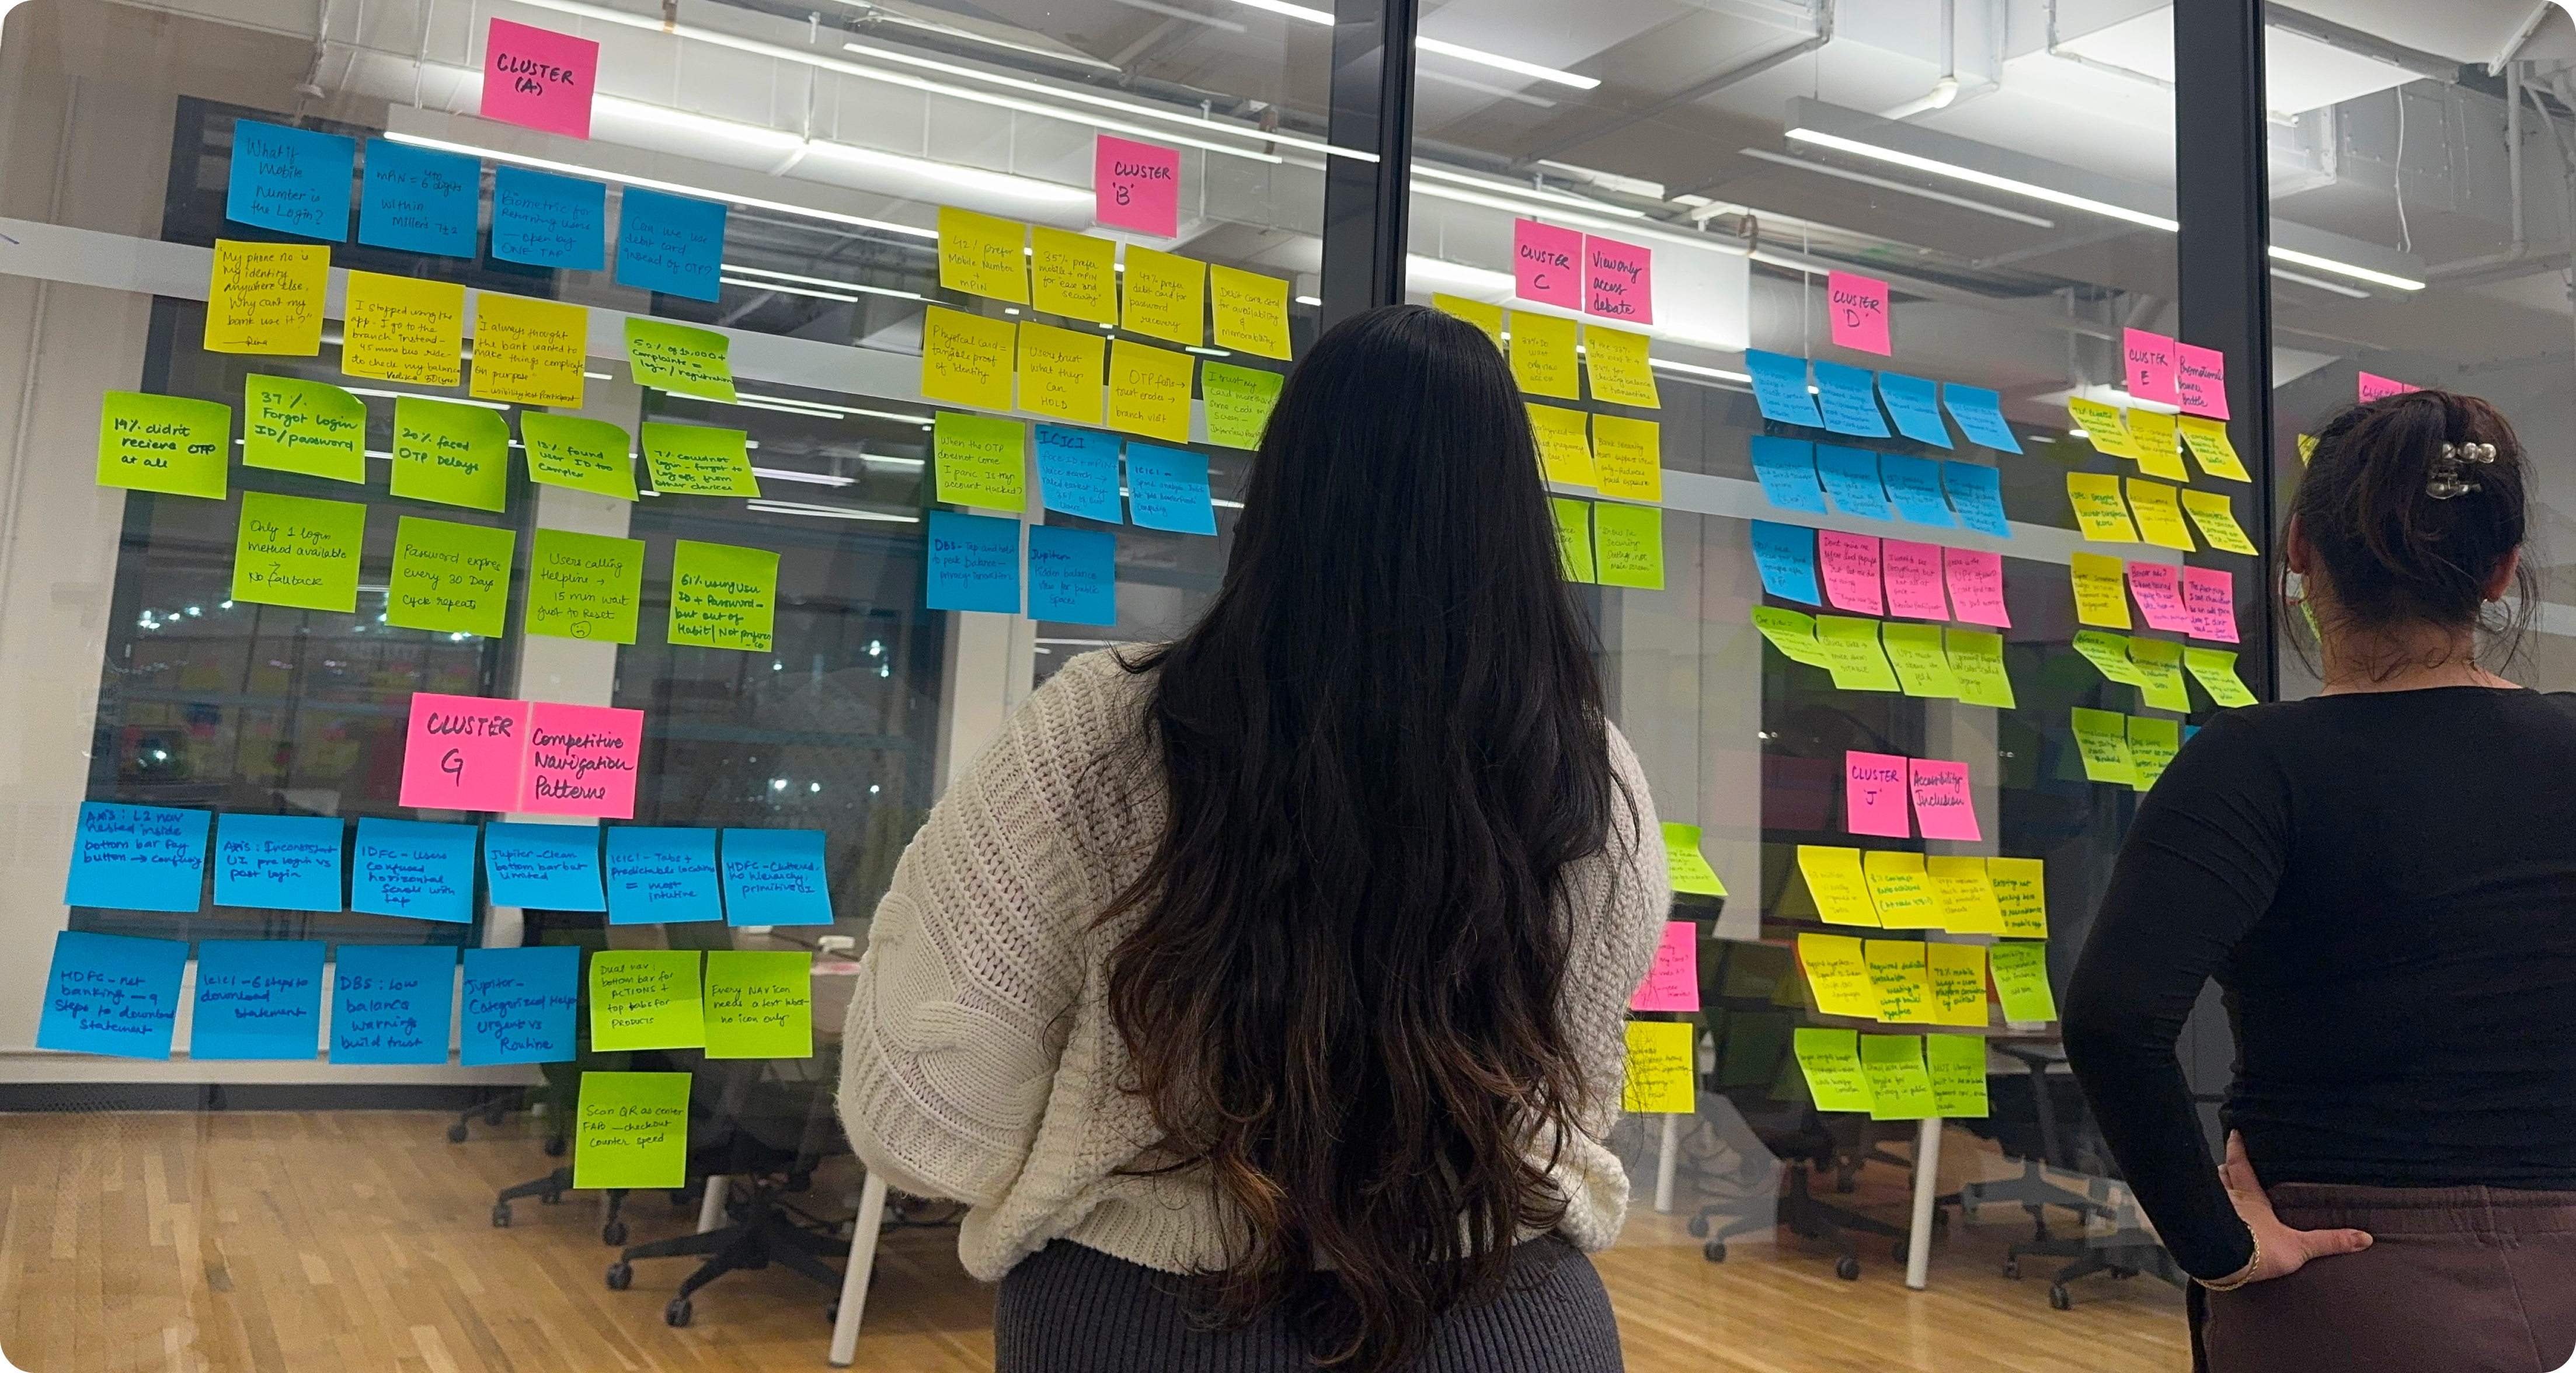
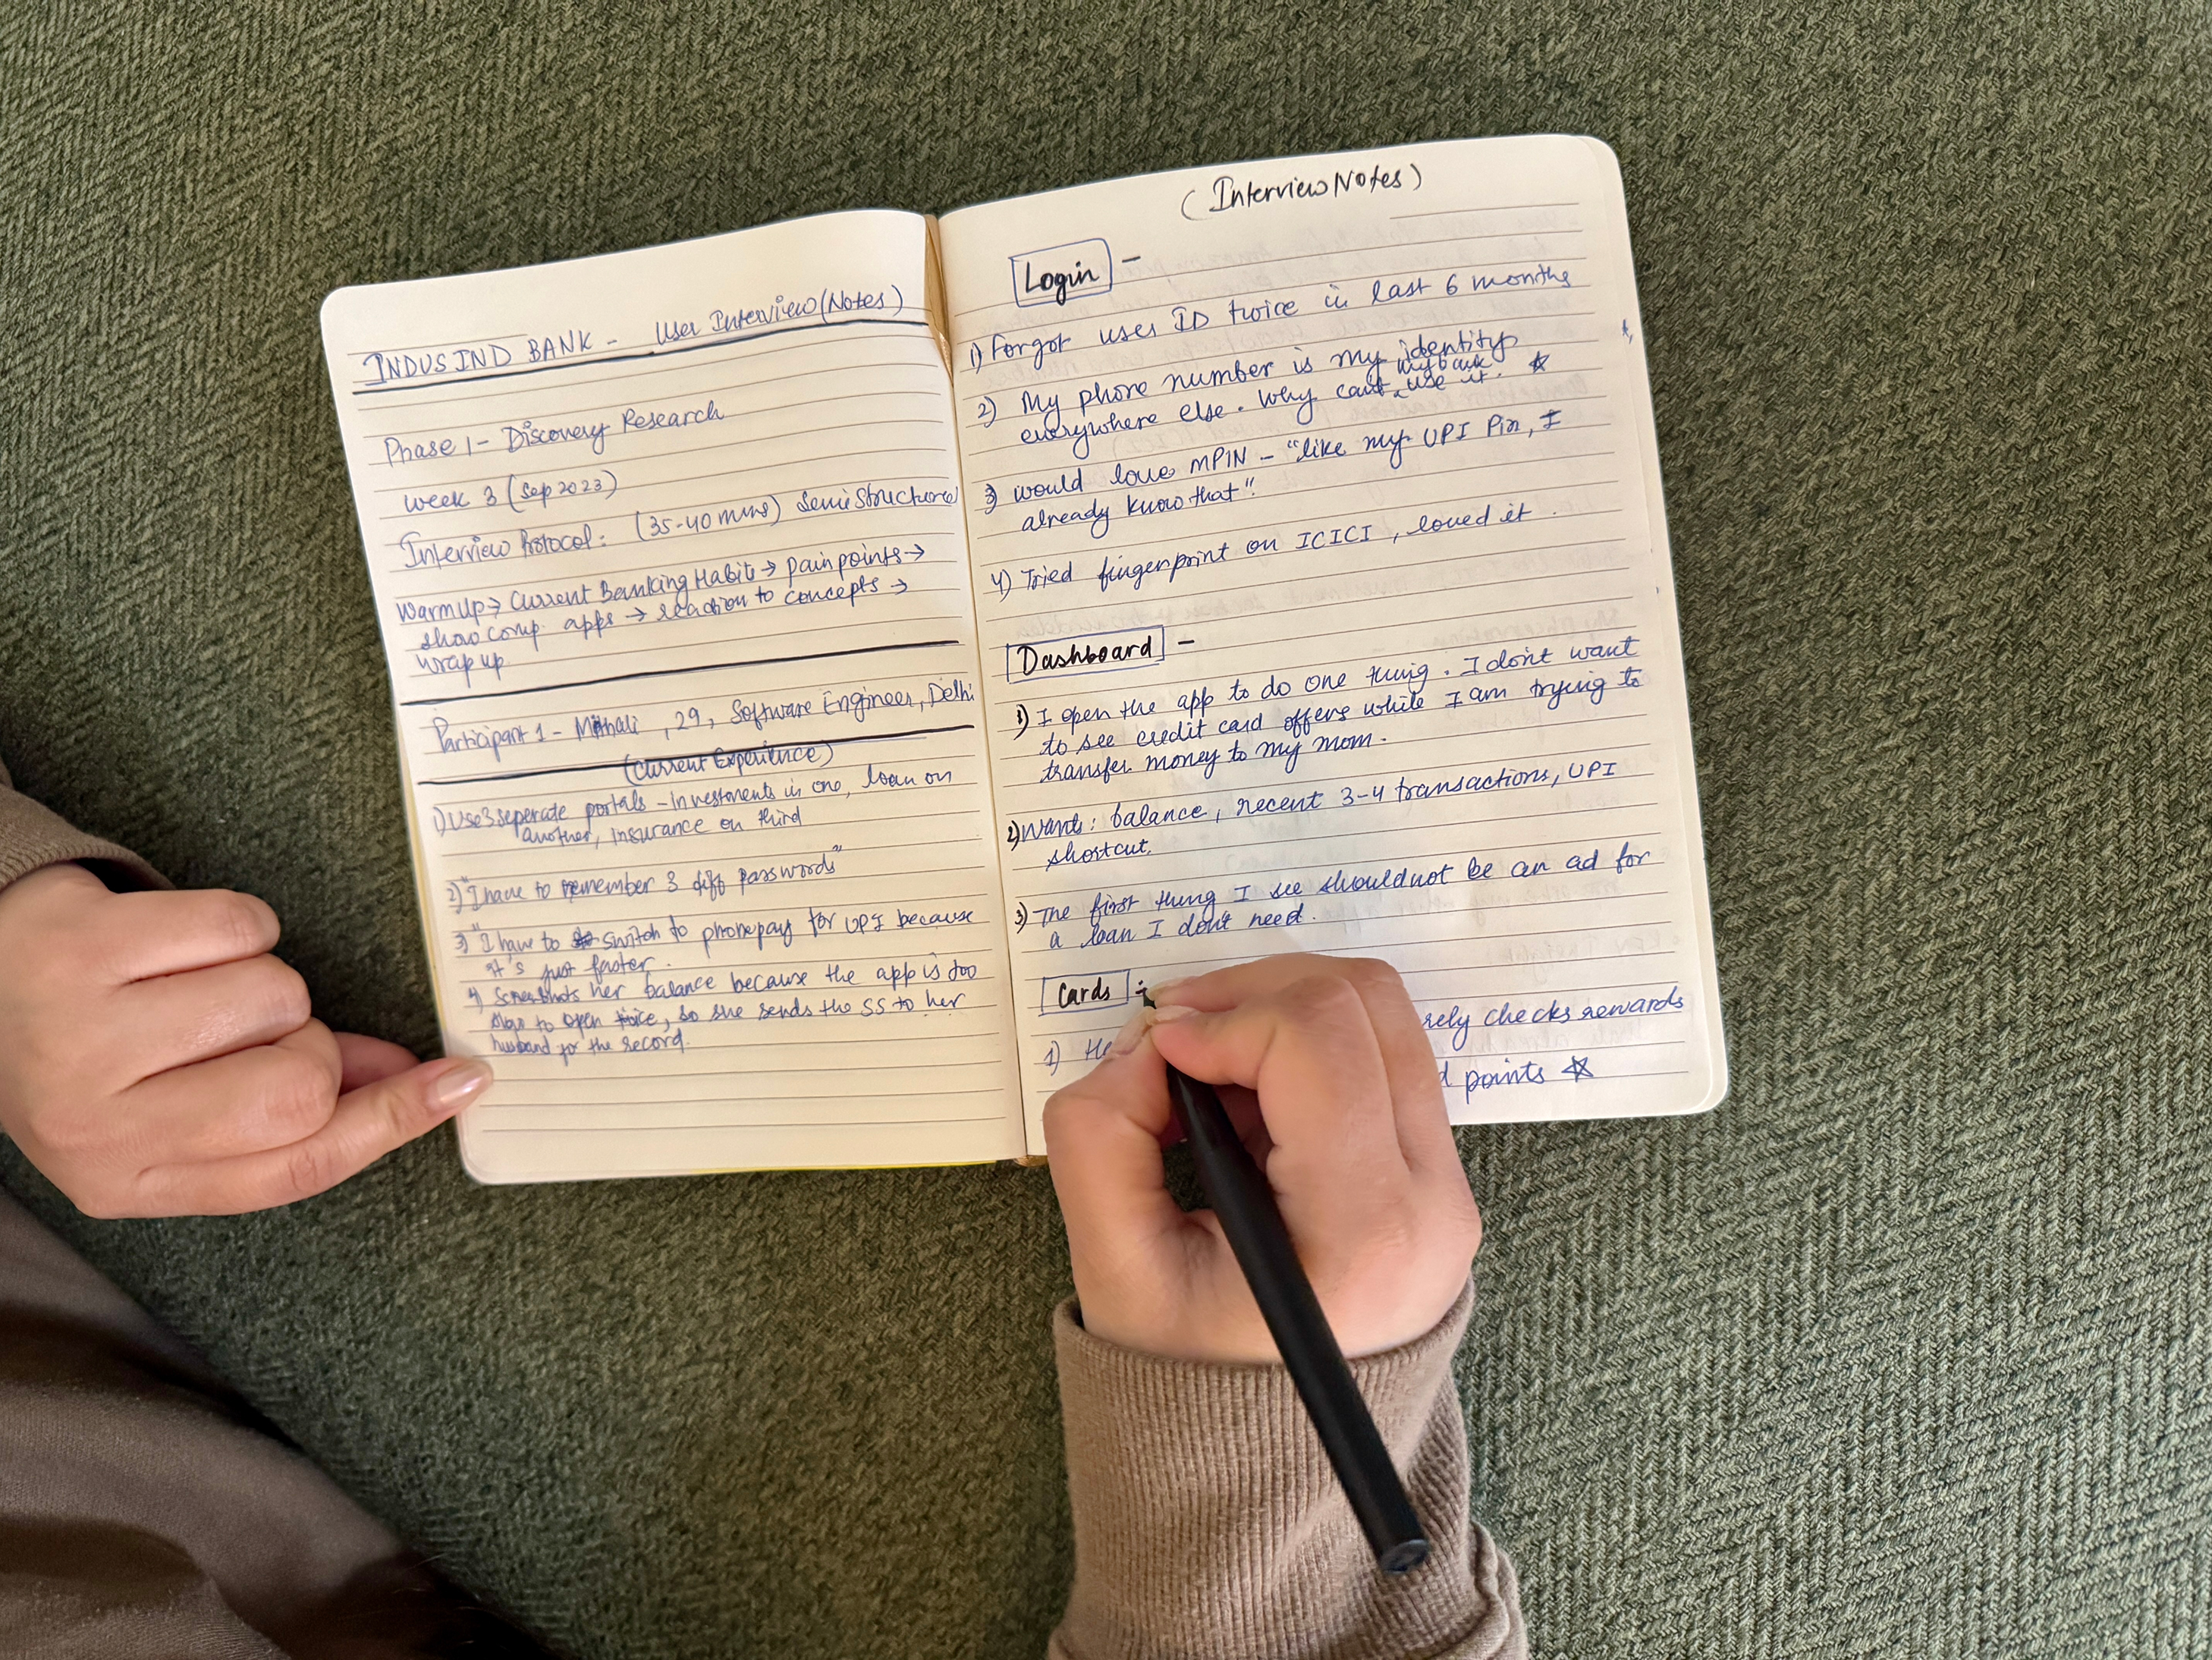
Research Program
A mix of qualitative and quantitative methods helped us build a complete picture
of customer needs, friction points and opportunities.
benchmarking
Study samples
We recruited customers across key journeys to validate behavior and test core flows.
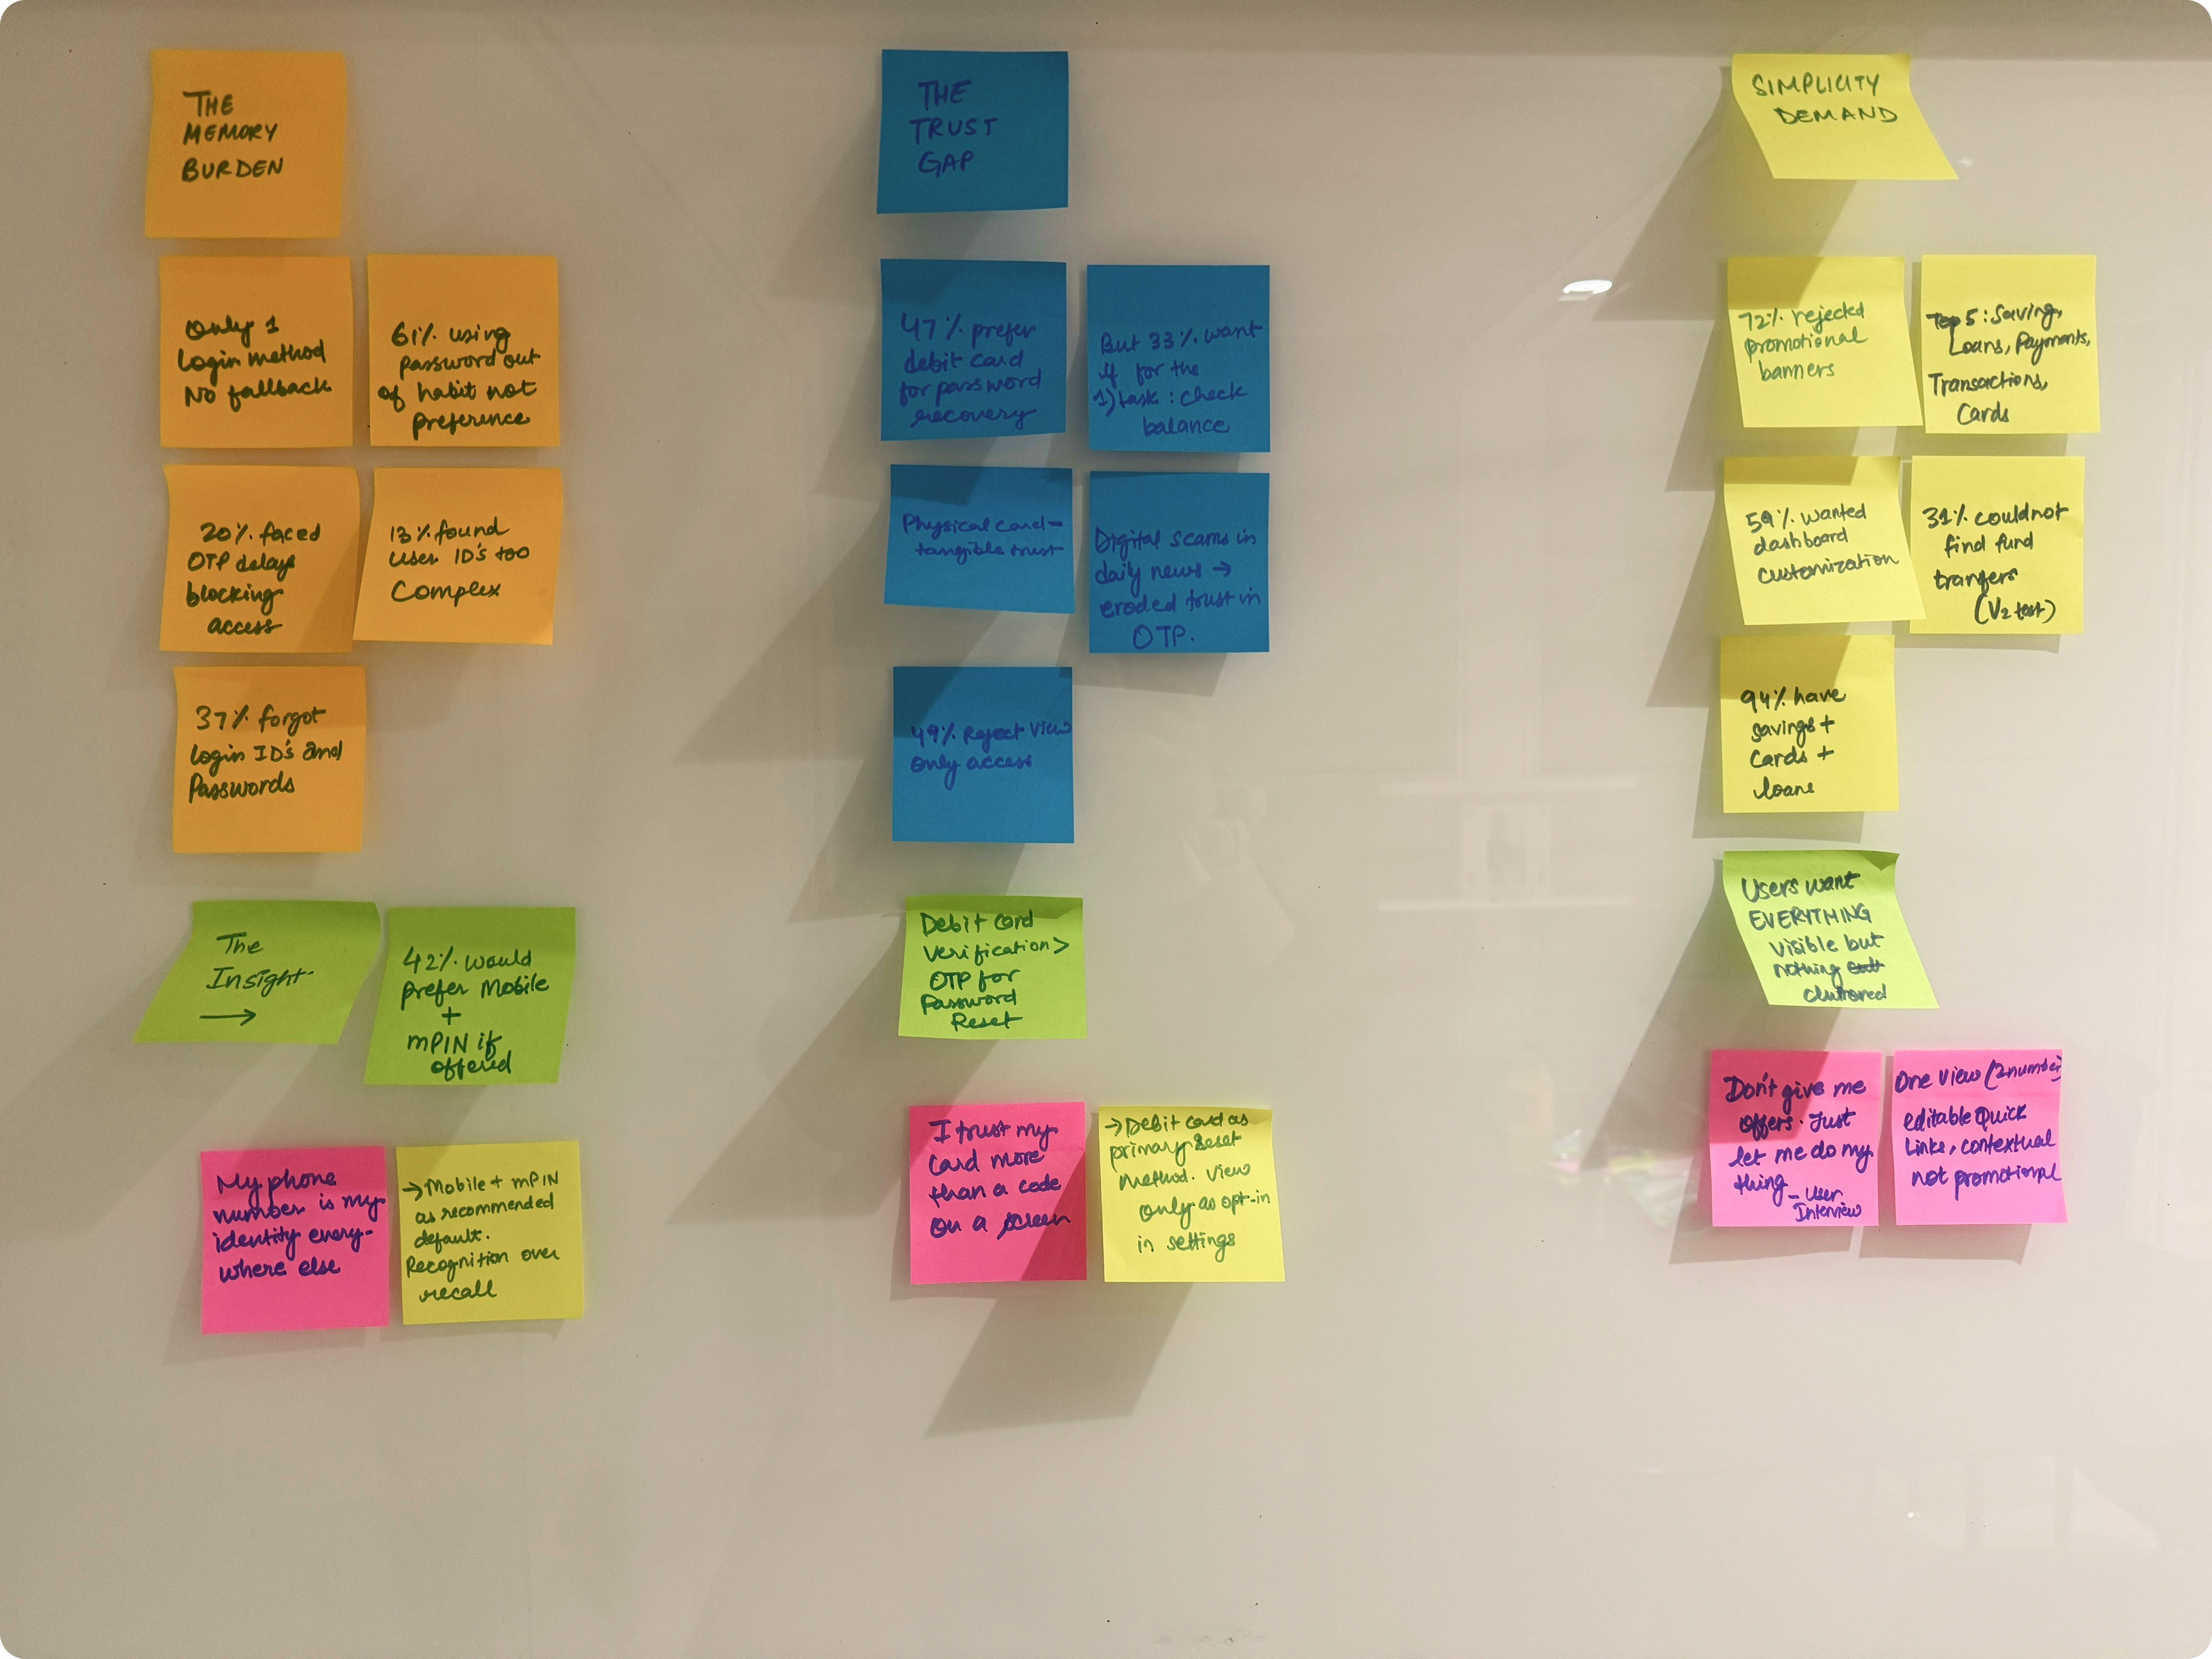
Four findings became four design principles
We synthesised research insights into clear design principles that guided the product
strategy and experience design across the banking journey.
53% forgot their
User ID, password, or both
47% preferred debit-card
verification for recovery
72% did not want promotional
banners dominating the dashboard
Digital friction could move
into the physical service
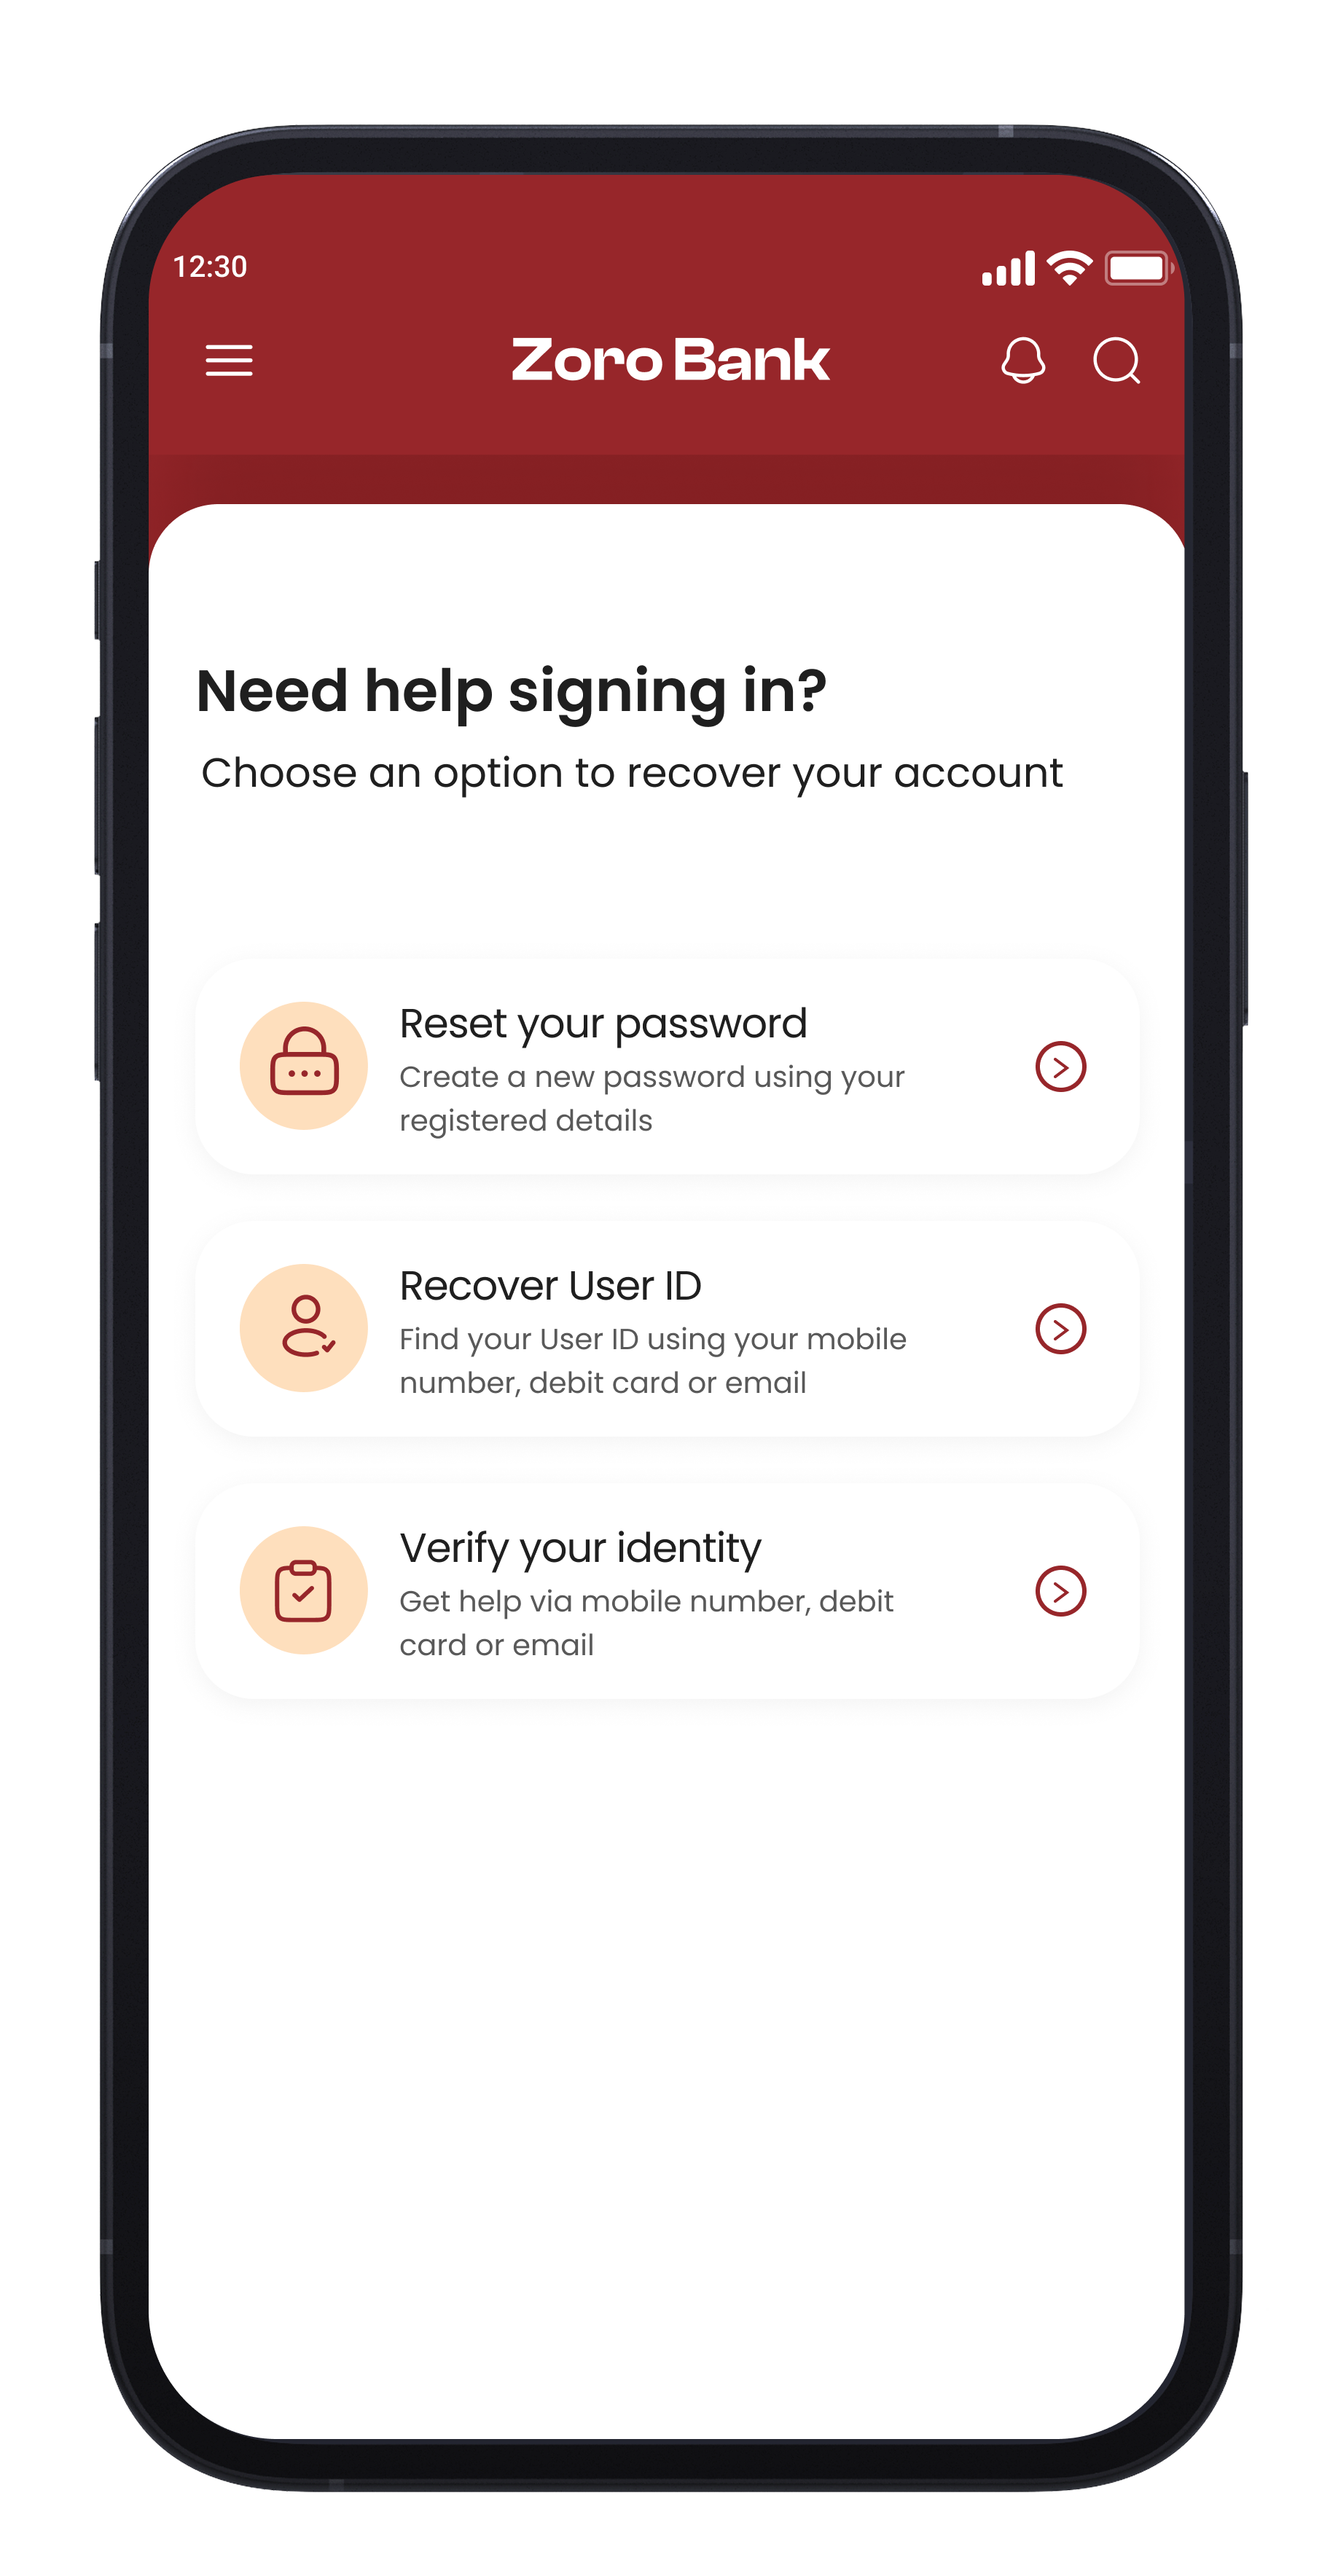
03 Authentication
Reducing memory burden without forcing behavior change.
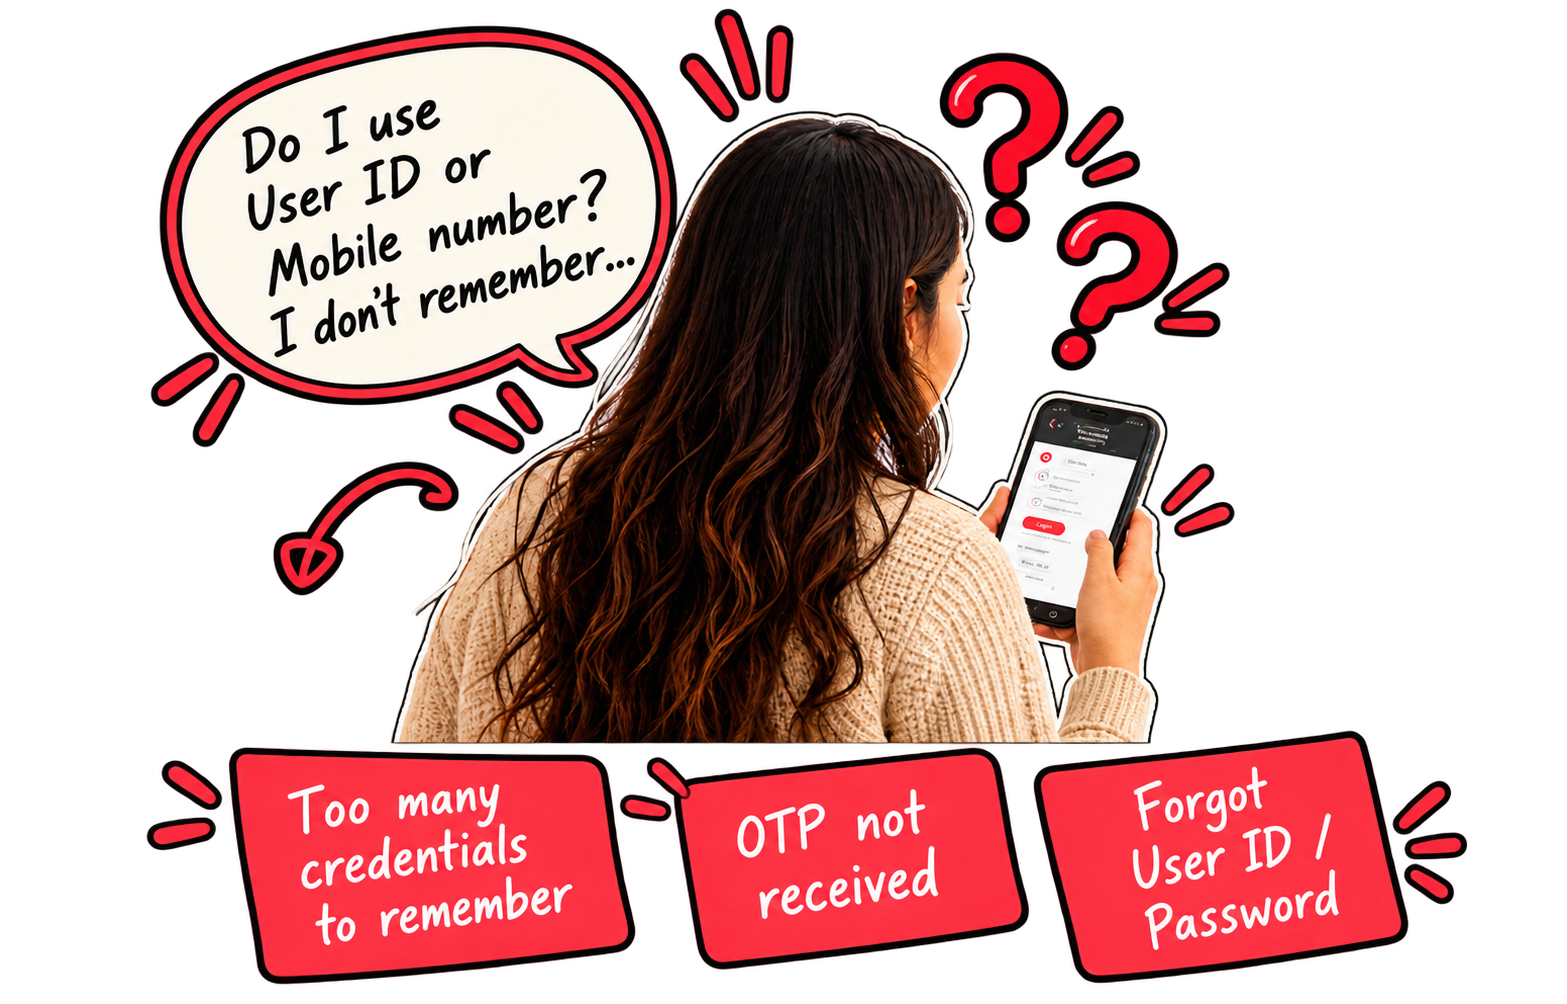
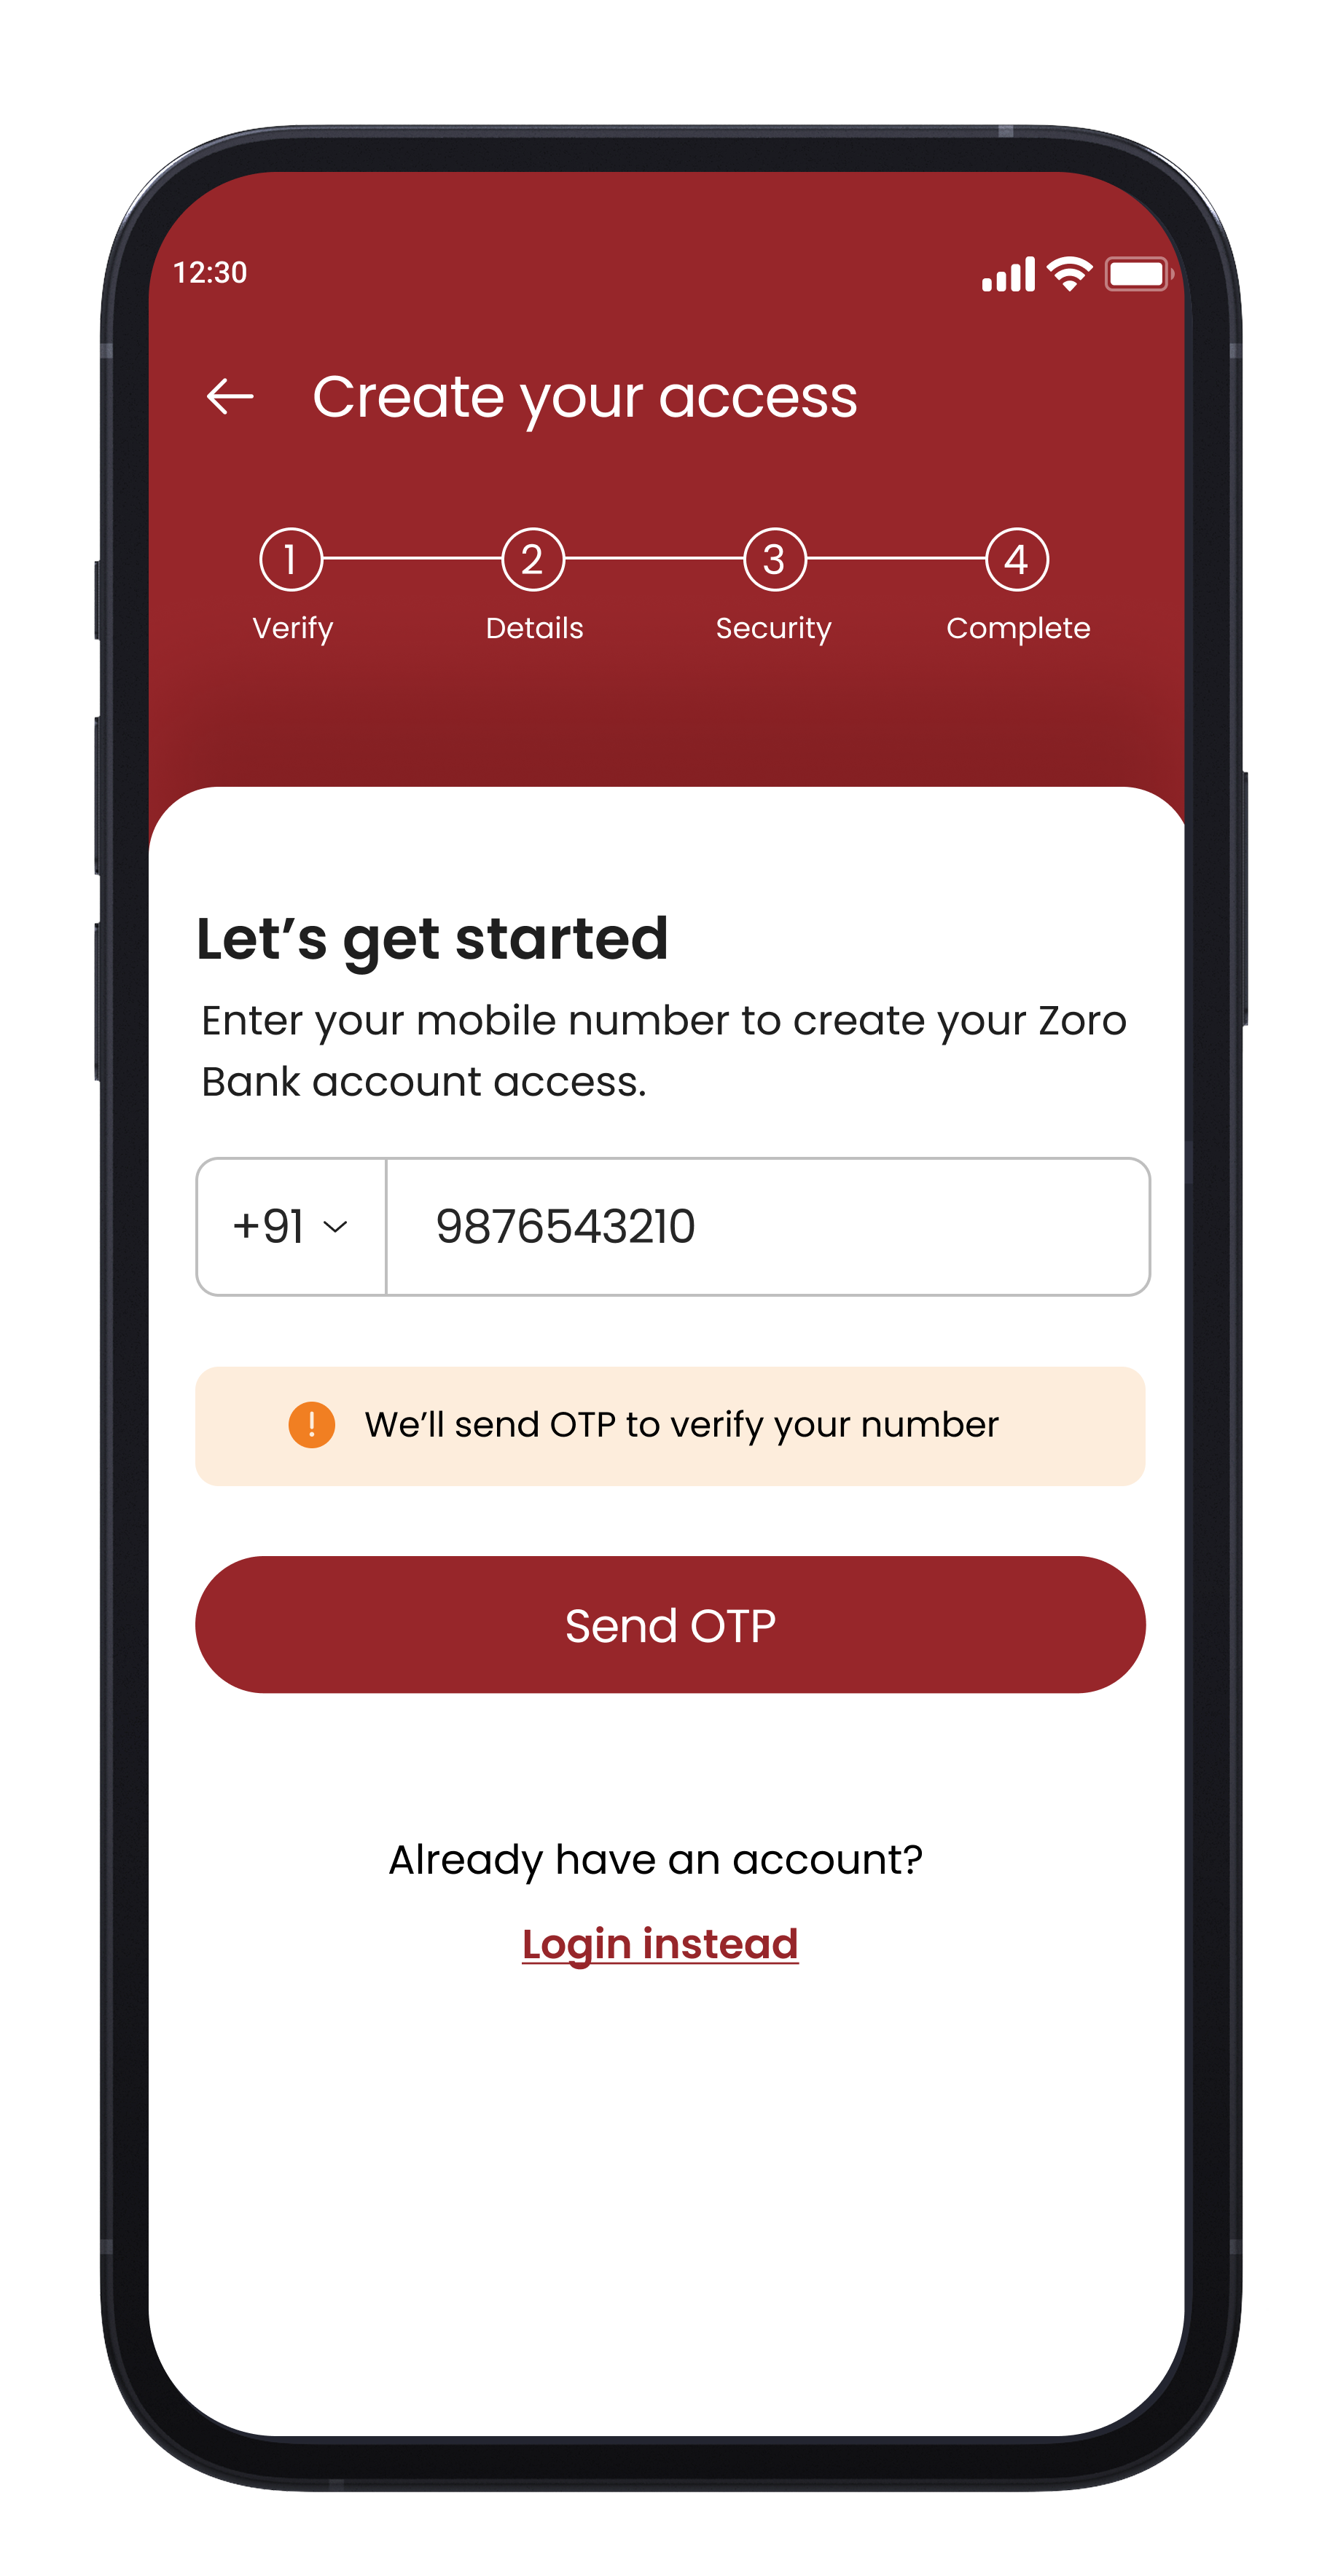
Login and registration were the biggest source of friction, with 52% of customer complaints related to authentication. Customers struggled with remembering multiple credentials, receiving OTPs, and recovering access.
Our goal was to design a simpler, more intuitive authentication experience while maintaining the security, regulatory, and business requirements of a bank.
Key insights from research
Authentication was a major pain point.
Insights from 100+ survey responses, 50+ customer interviews, branch research and usability testing.
forgot their User ID, password or both.
The problem wasn't just the number of steps, but the amount of information customers had to remember.
didn't receive an OTP.
OTP delivery issues created significant drop-offs during login and registration.
still used User ID and Password.
Most customers were familiar with this method and were not ready to fully switch.
preferred using Mobile number + mPIN for login.
Customers preferred options that were easier to remember and always available.
We explored multiple authentication approaches.
We considered different ways to simplify login and registration, evaluated their feasibility, and tested them with customers.
Keep User ID + Password as default
Familiar to most users and requires no behaviour change.
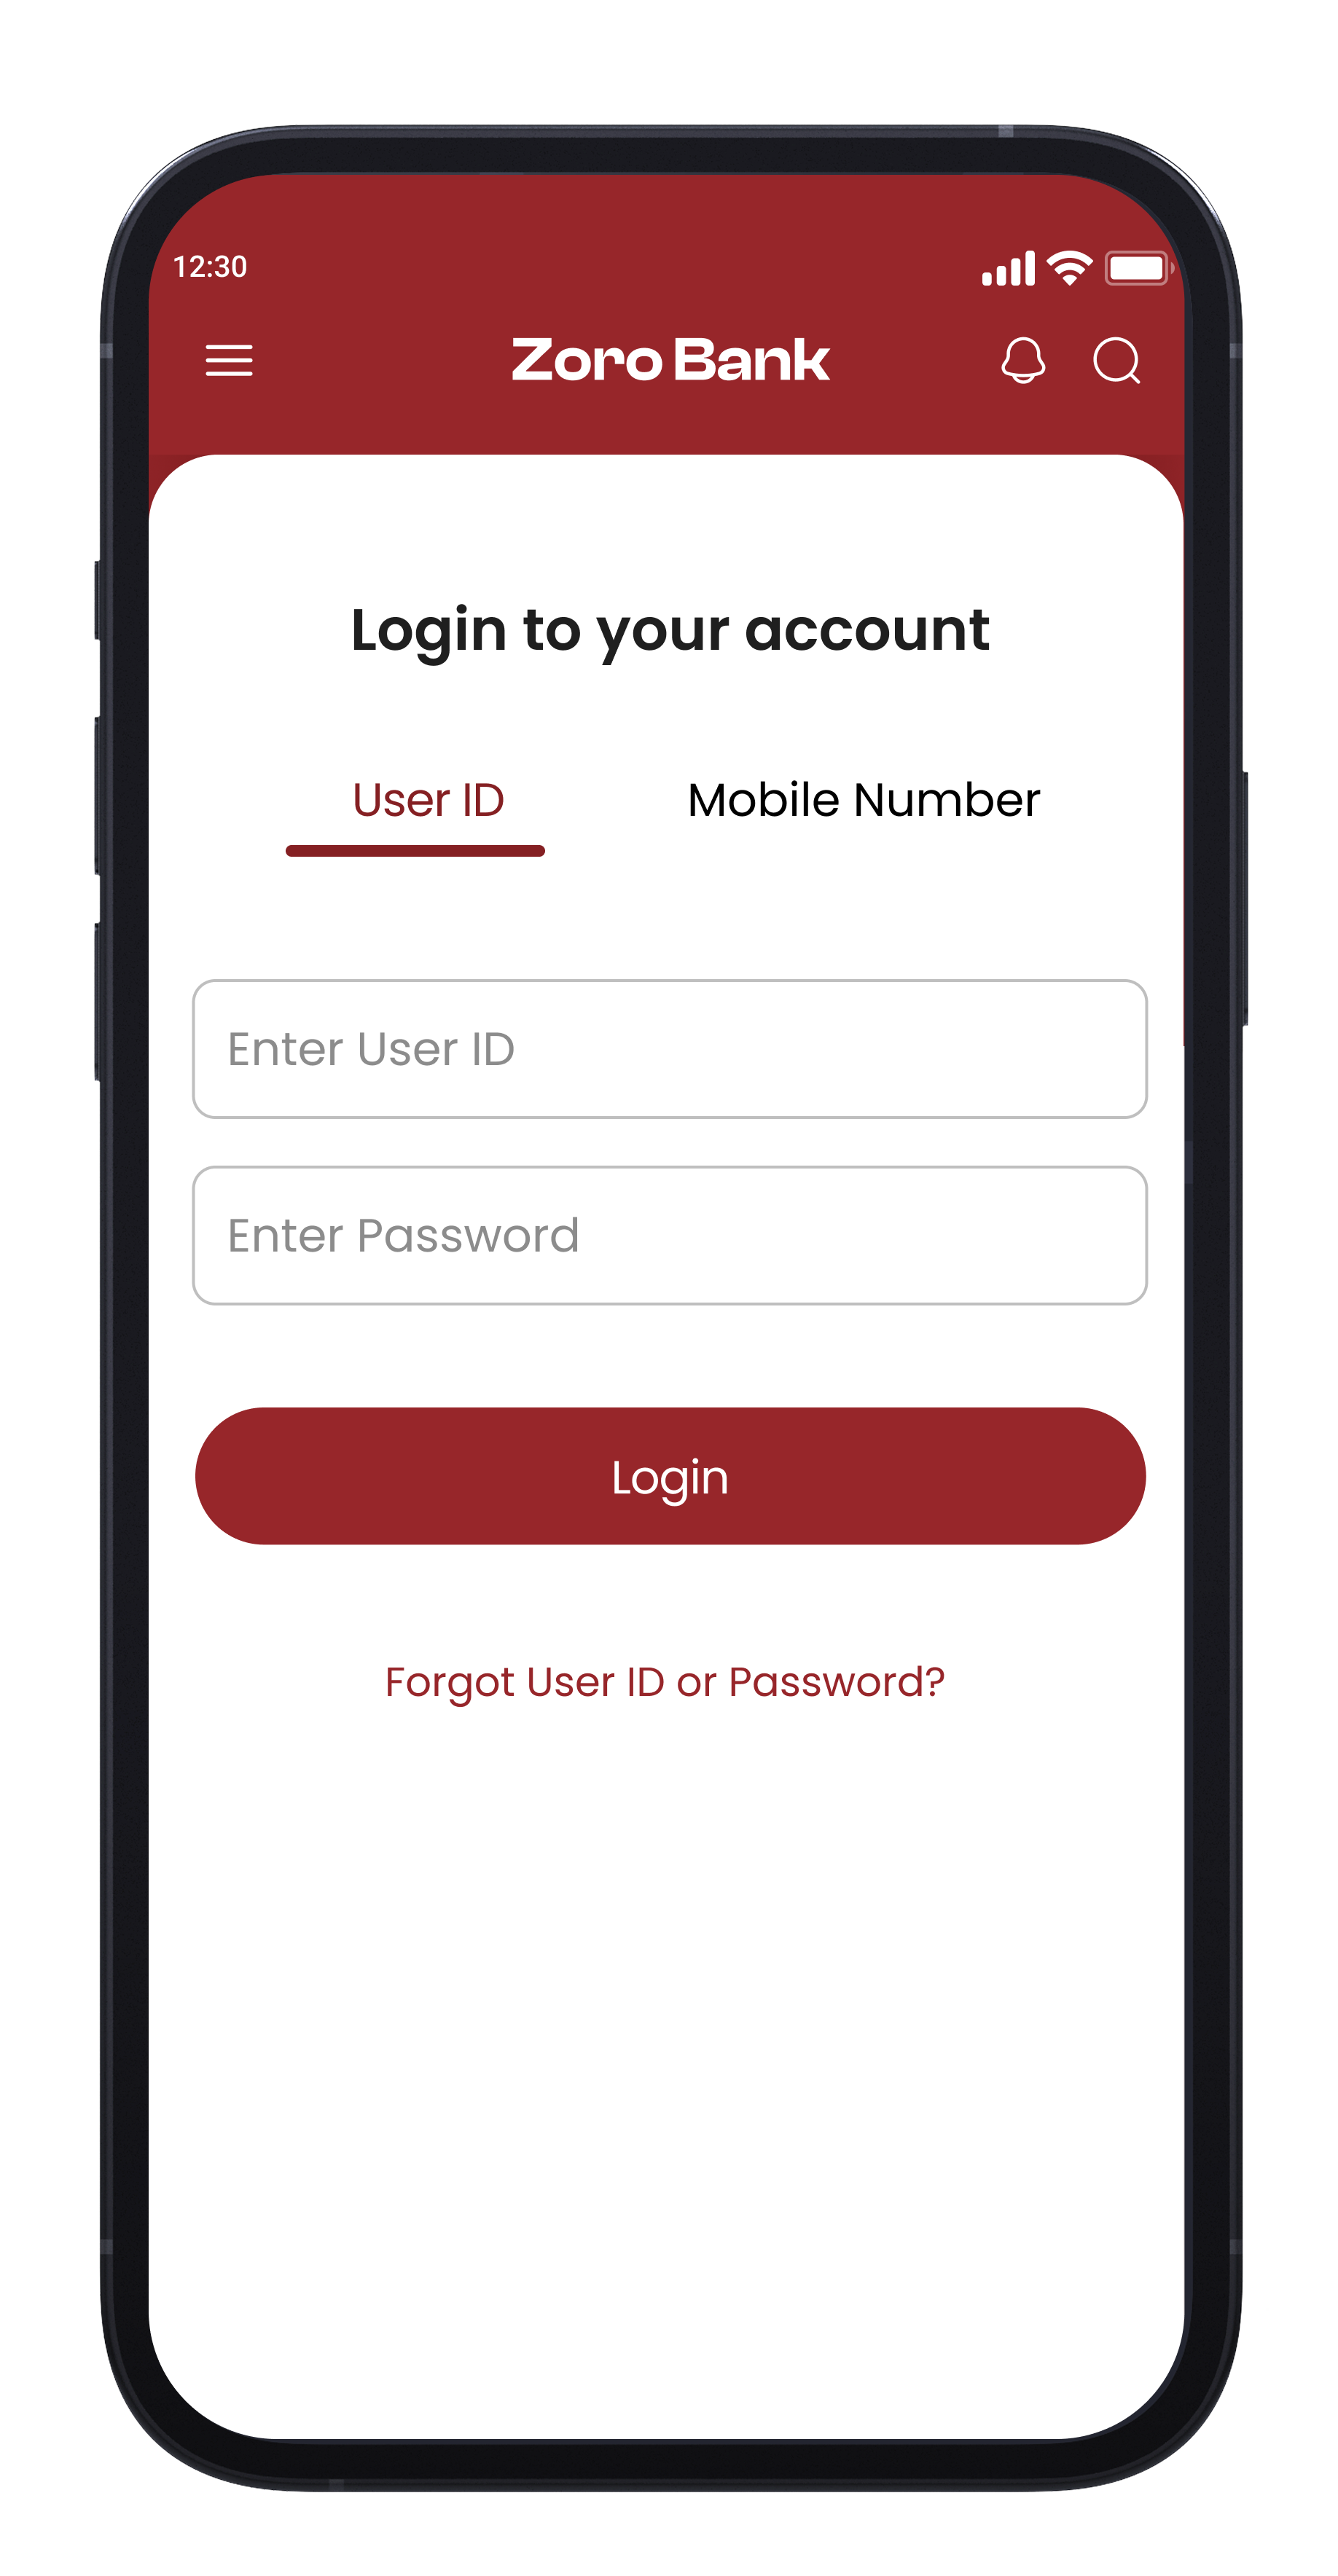
- Familiar and widely used
- Lower support burden
- High memory burden
- Continued login errors
Require Mobile Number + mPIN
Simpler and easier to remember.
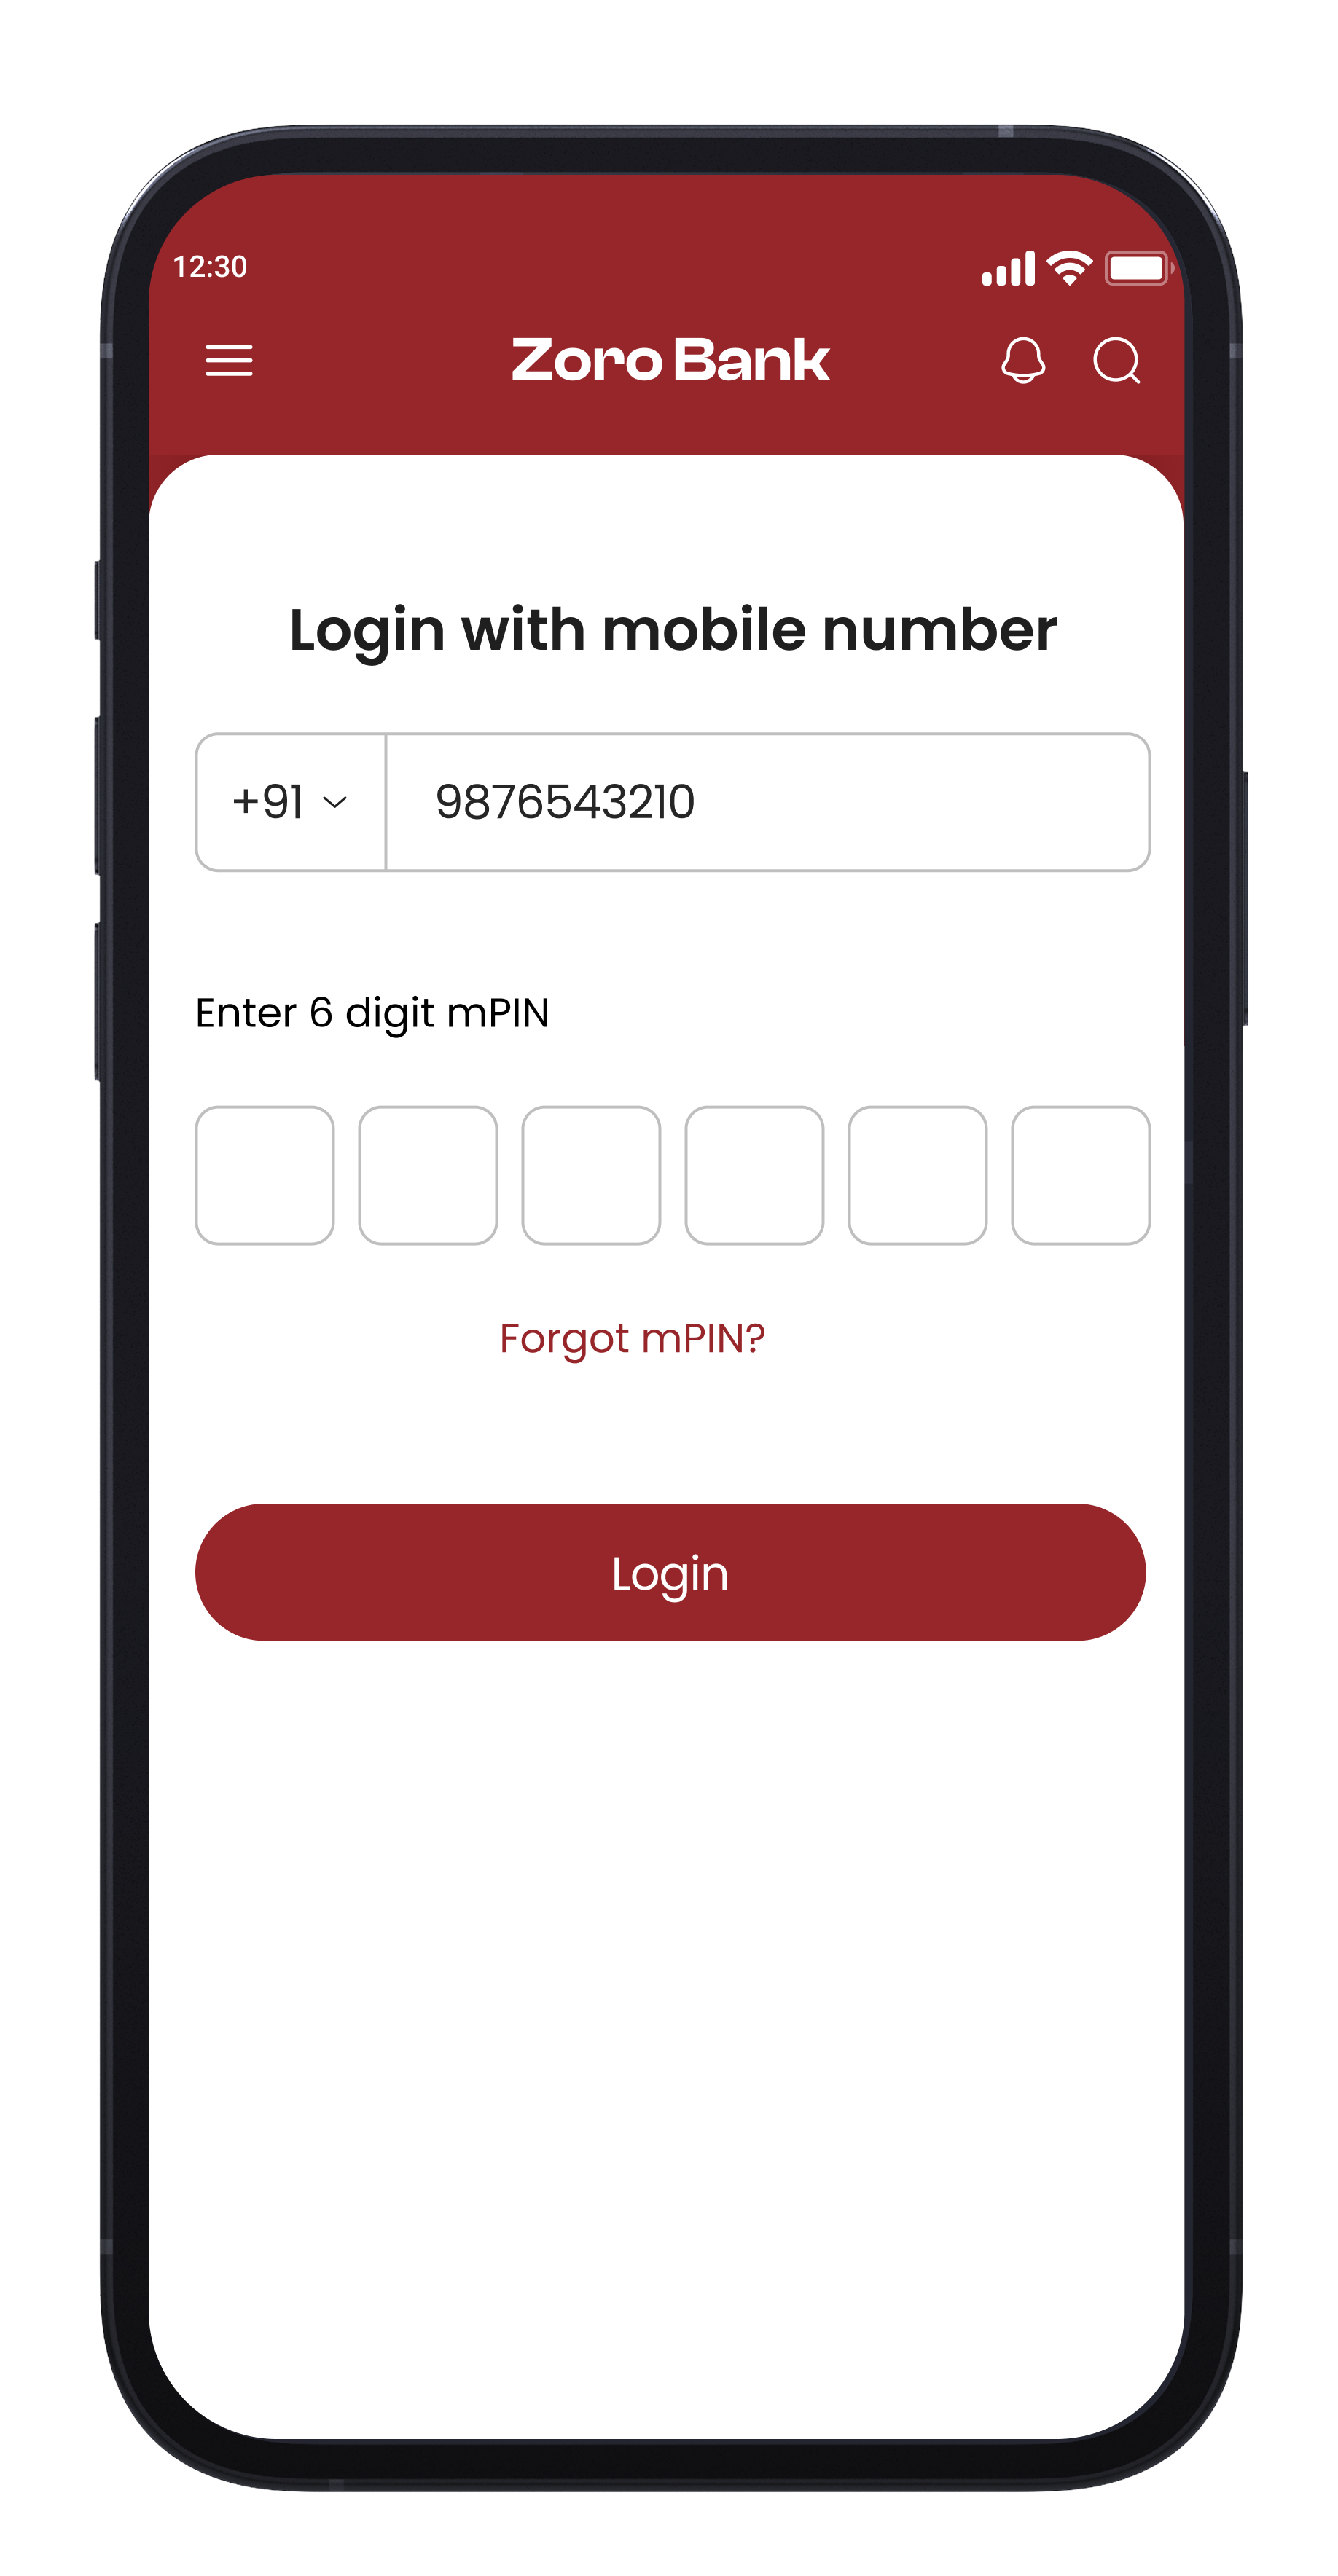
- Reduces credential recall
- Quicker login experience
- Forces behavior change
- Some users don't receive OTPs
Recommend mPIN, retain password
Simplifies access while giving customers a choice.
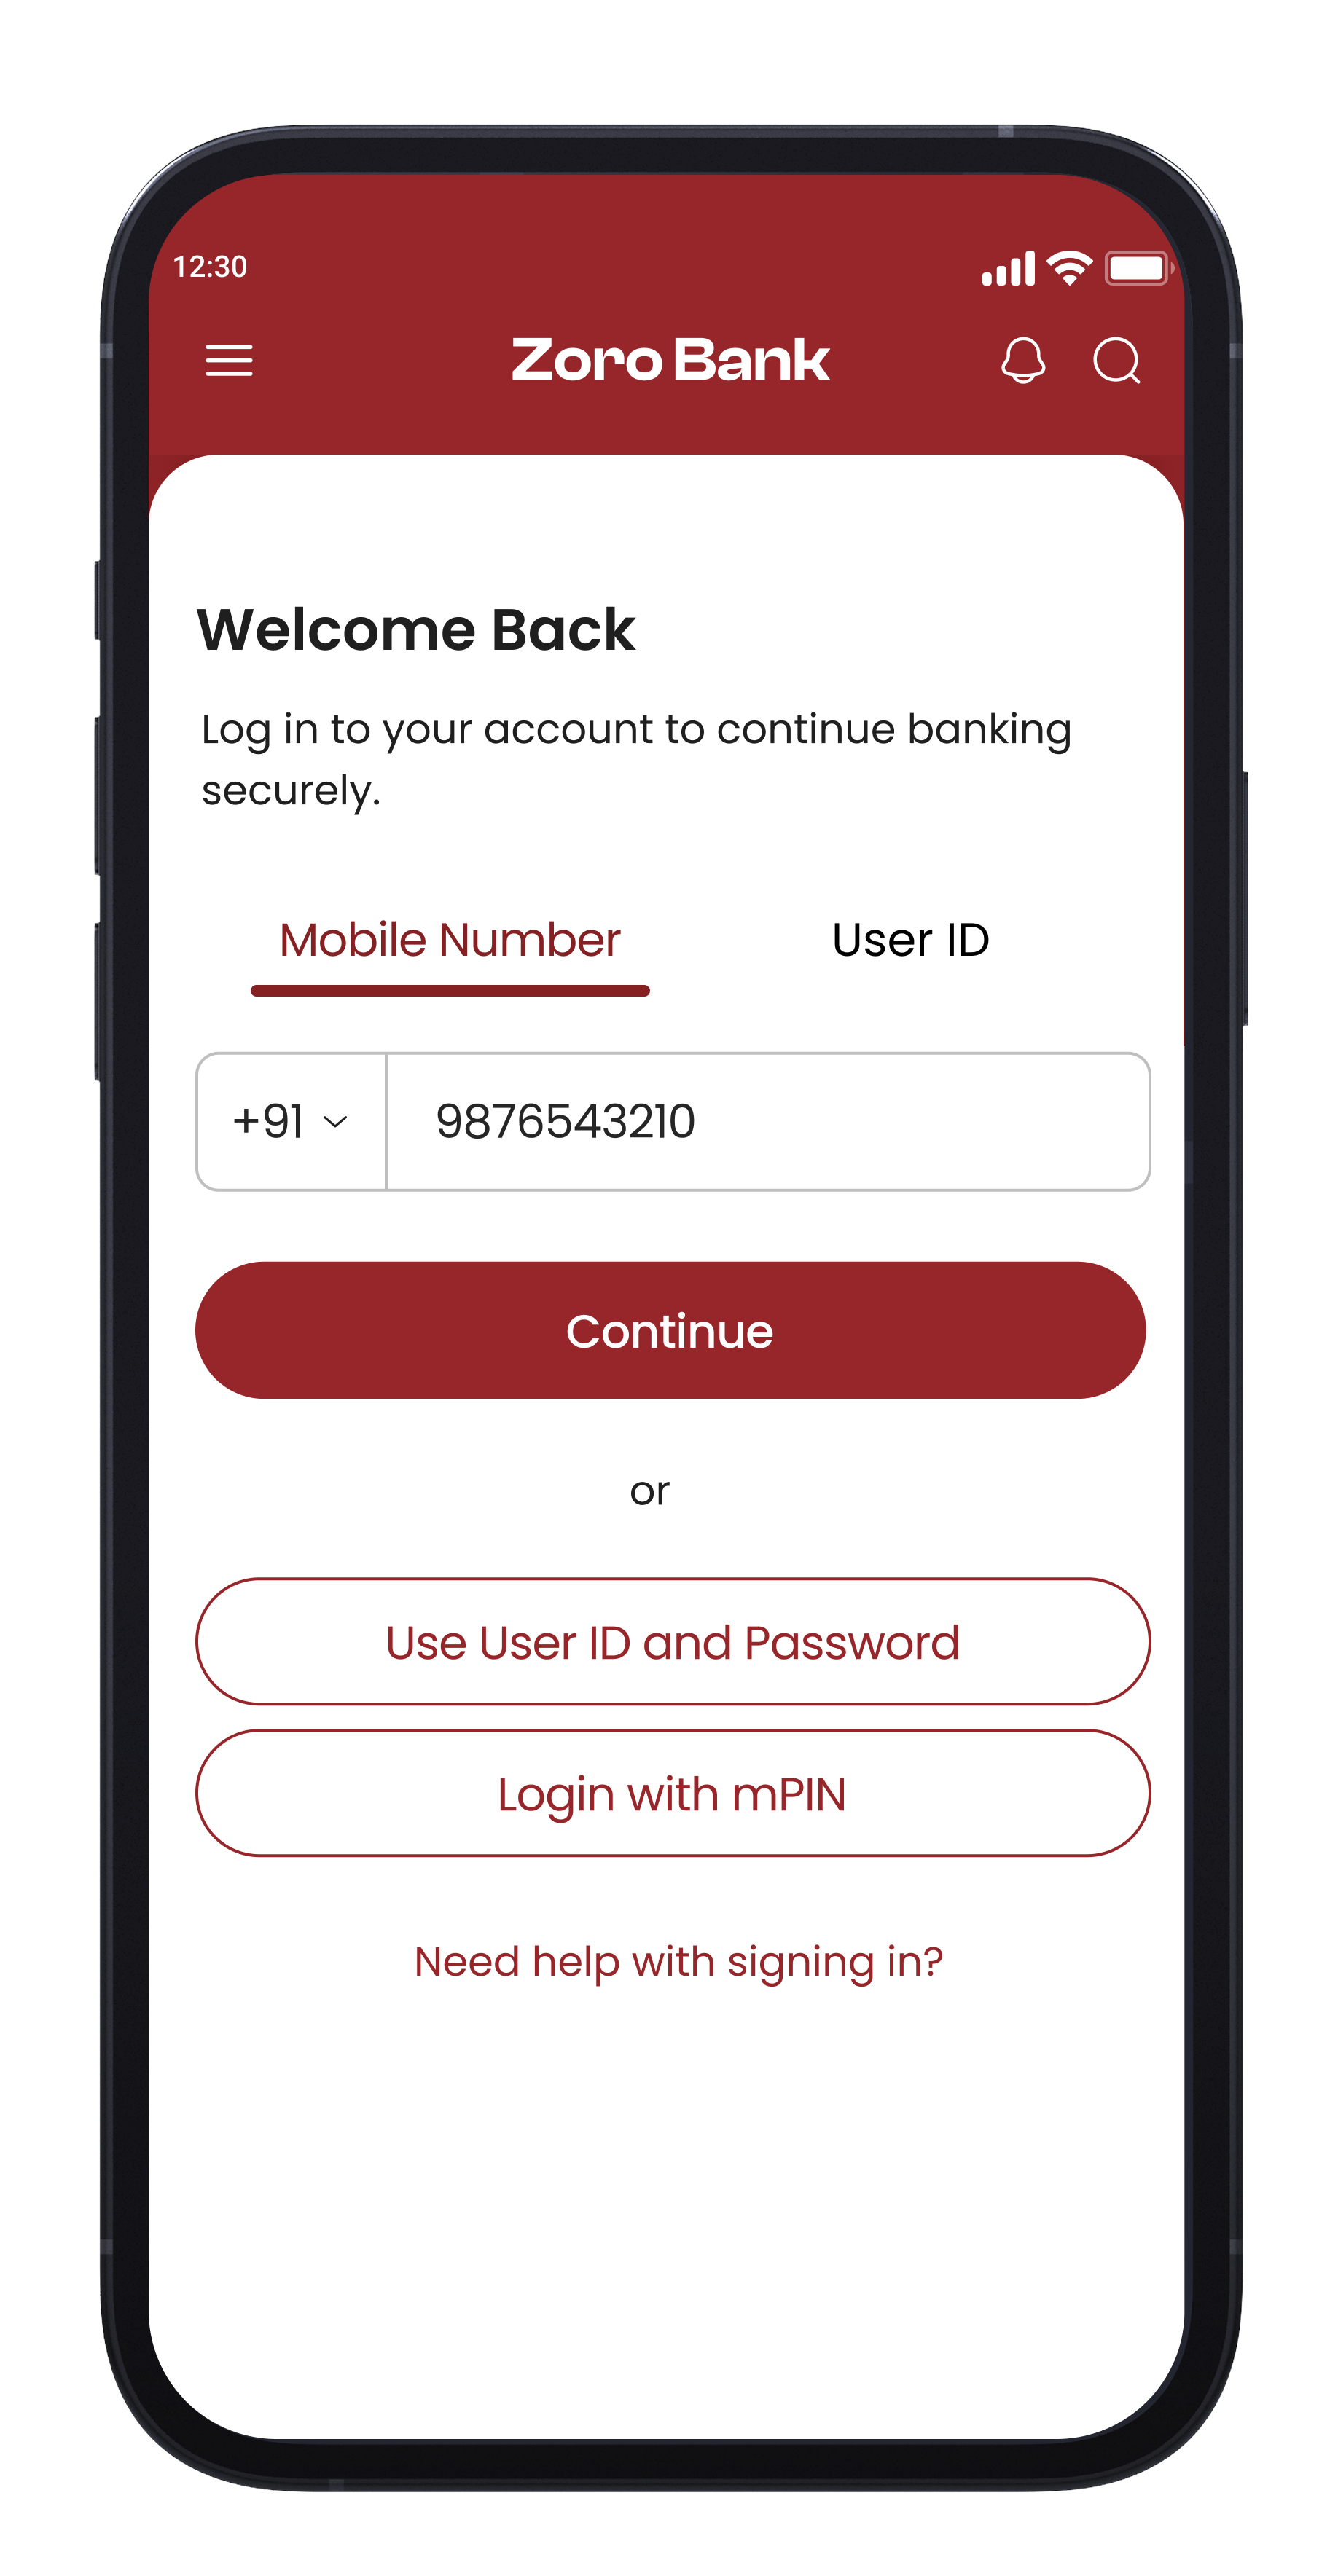
- Reduces memory burden
- Supports existing behavior
- More intuitive experience
- Requires gradual transition
- Need clear communication
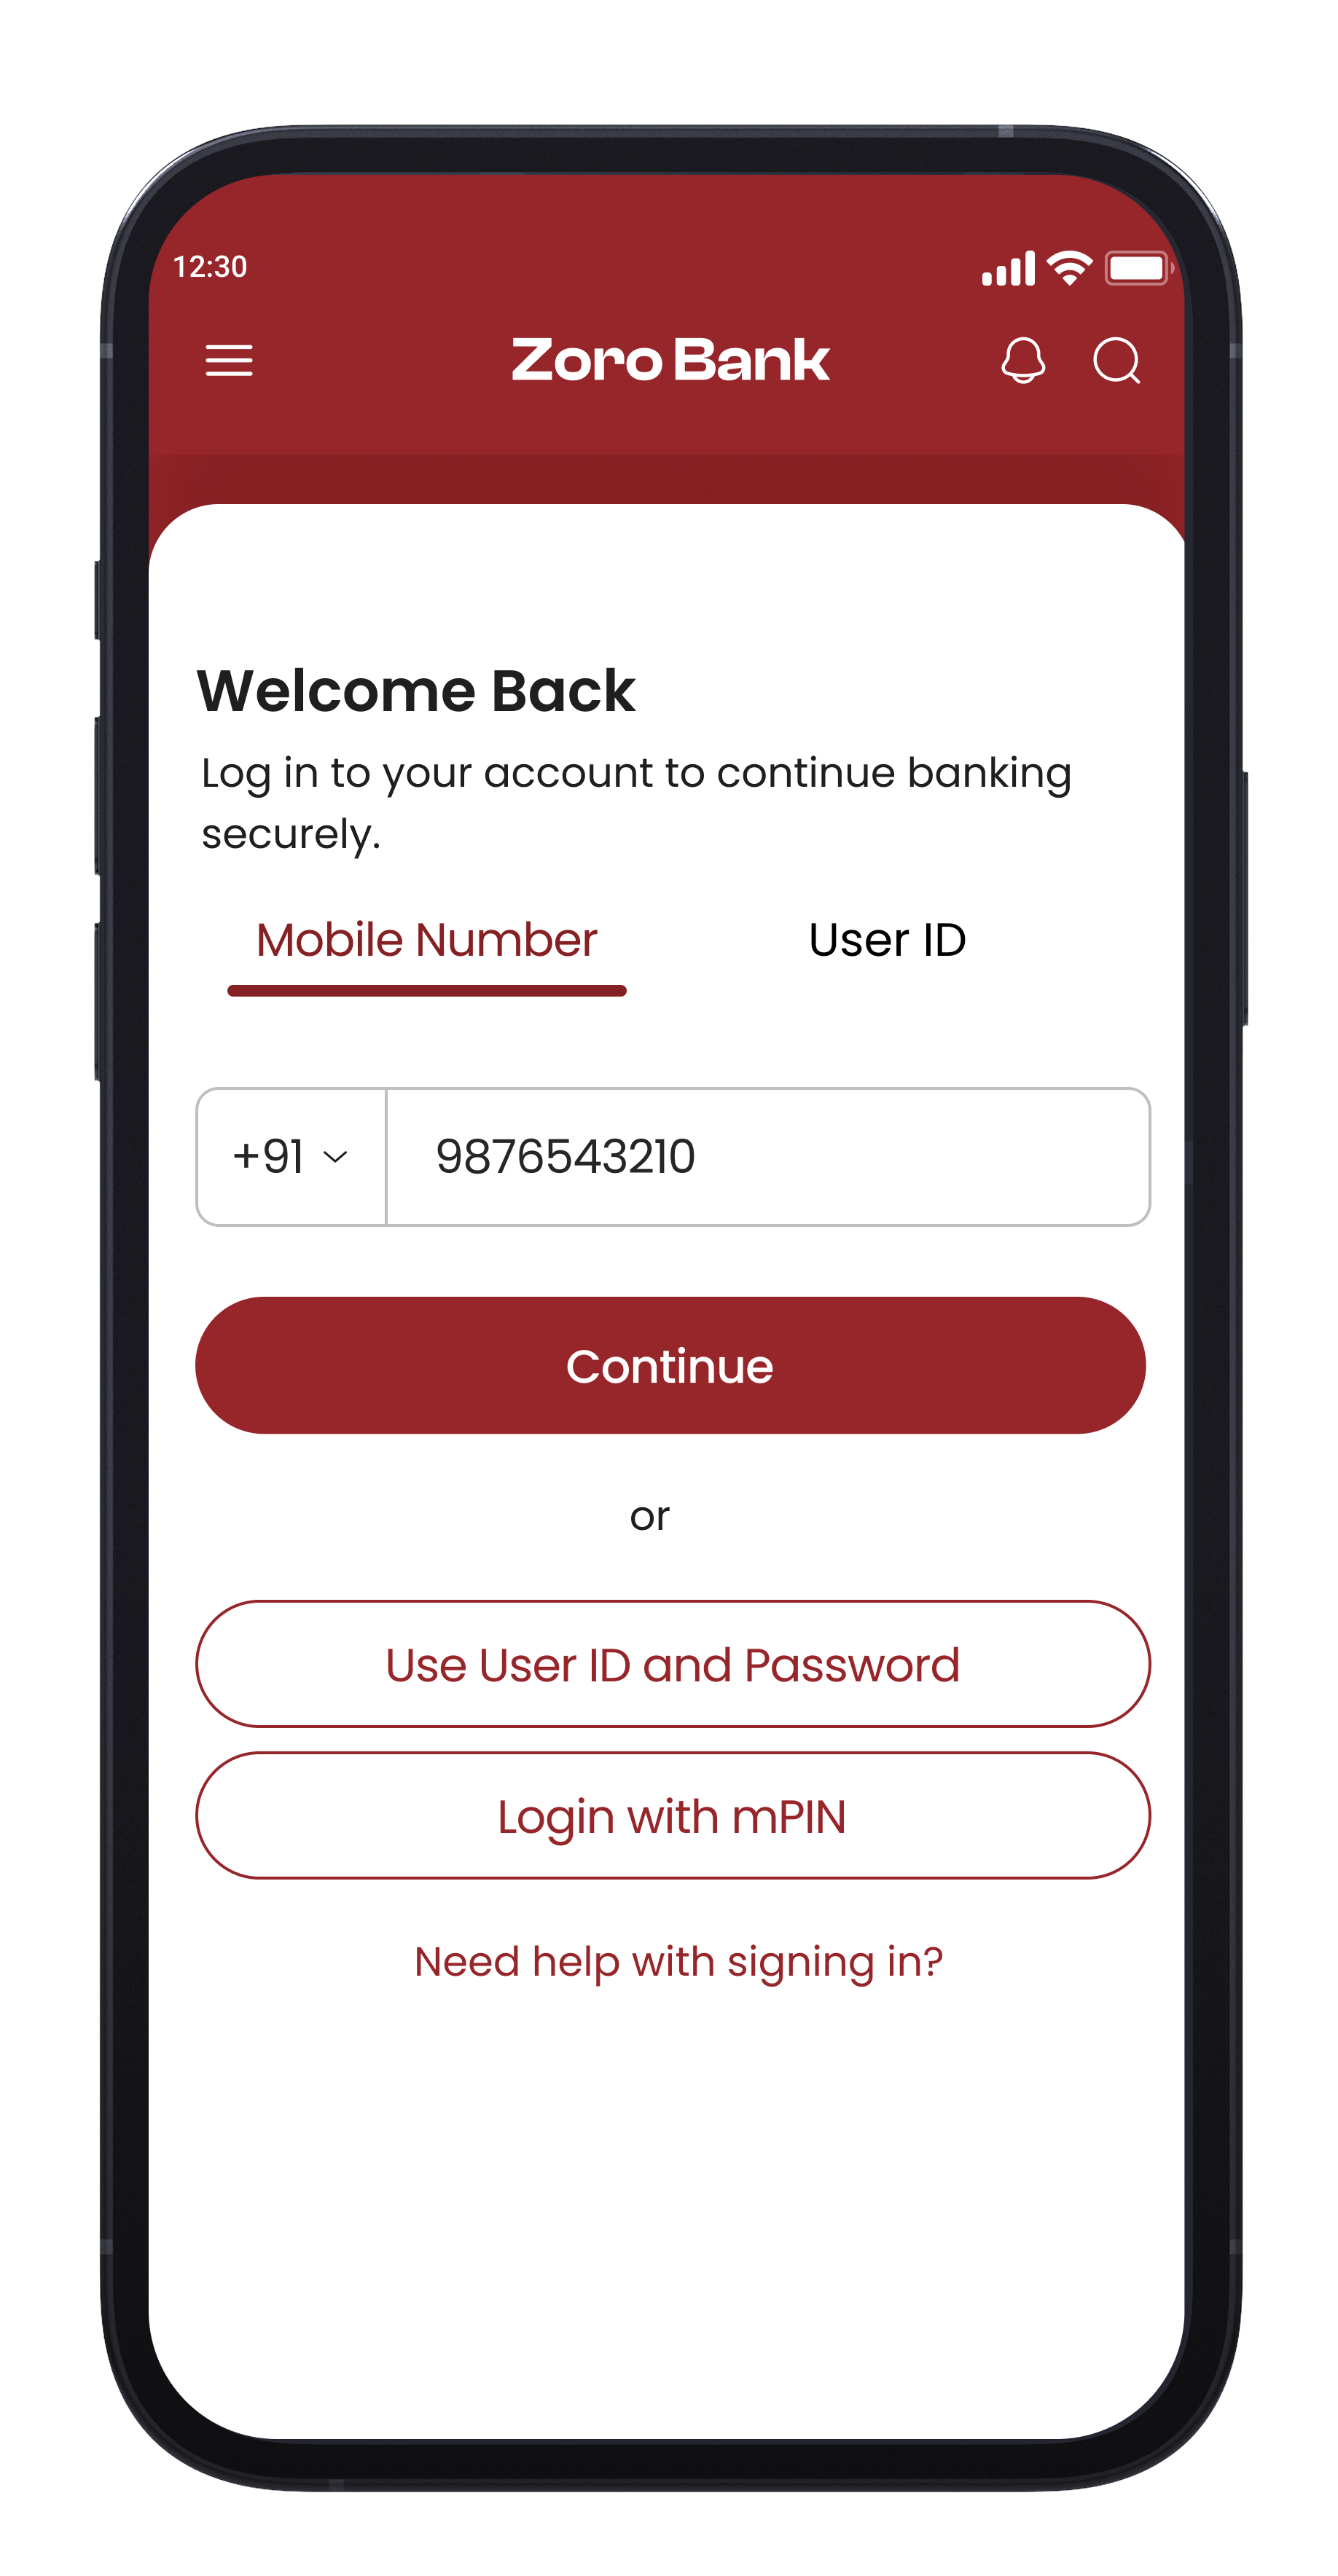
A flexible and familiar login experience.
We designed a unified experience that supports multiple login options, reduces memory burden, and keeps the experience simple and consistent.
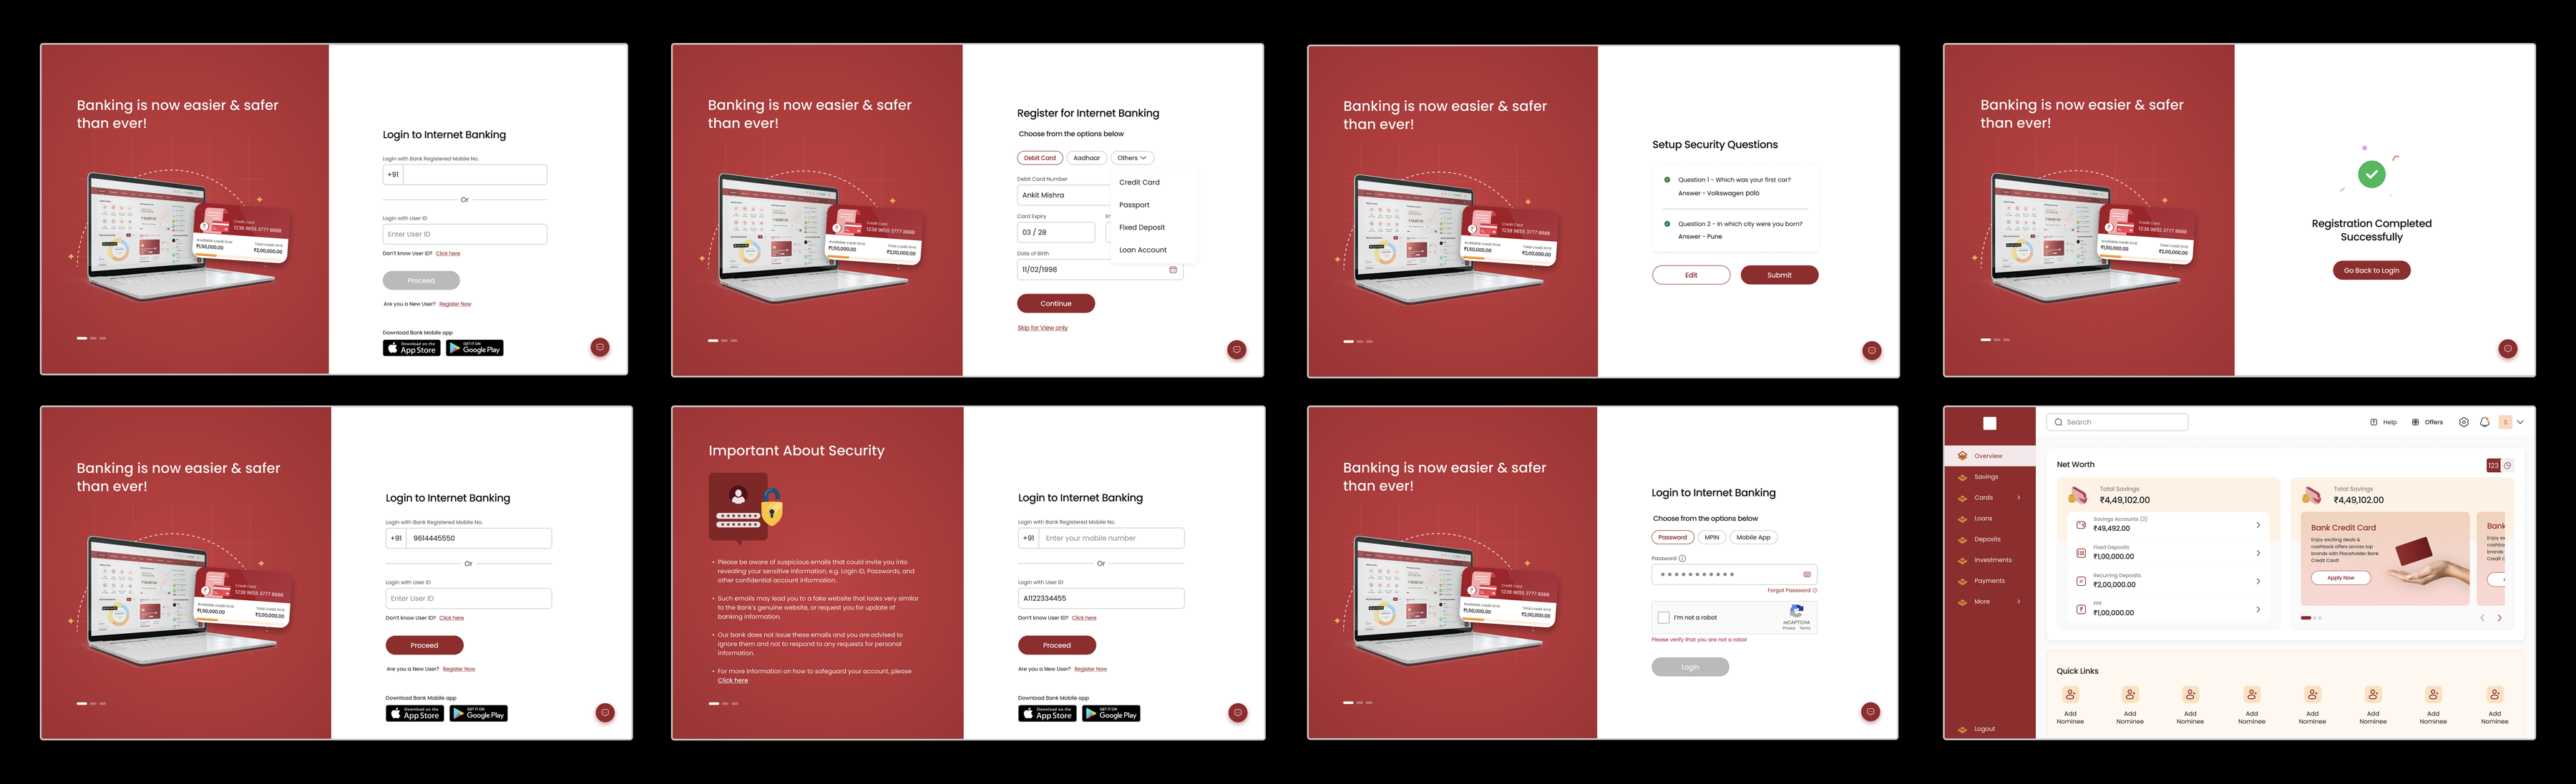
Start with a single, simple input.
Simple and quick verification.
A seamless transition to home.
Why this approach?
Gives customers flexibility to use the method they prefer.
Reduces the amount of information they have to remember.
Keeps the experience simple and consistent across web and mobile.
Works within security and regulatory requirements.
Observing what customers did, not only what they said.
The meaning of mPIN was unclear.
Some participants confused their banking-app mPIN with their ATM PIN. I introduced clarifying copy to make the distinction understandable.
Biometric login was expected.
Some returning customers instinctively searched for biometric authentication, reinforcing the importance of supporting a familiar, low-effort return journey.
The login experience was easy to use in testing.
rated the task easy.
average ease rating.
encountered no difficulty.
The flow felt simple and easy to follow. I like that I can use my mobile number.
04 Card Management
Giving customers control without creating anxiety.
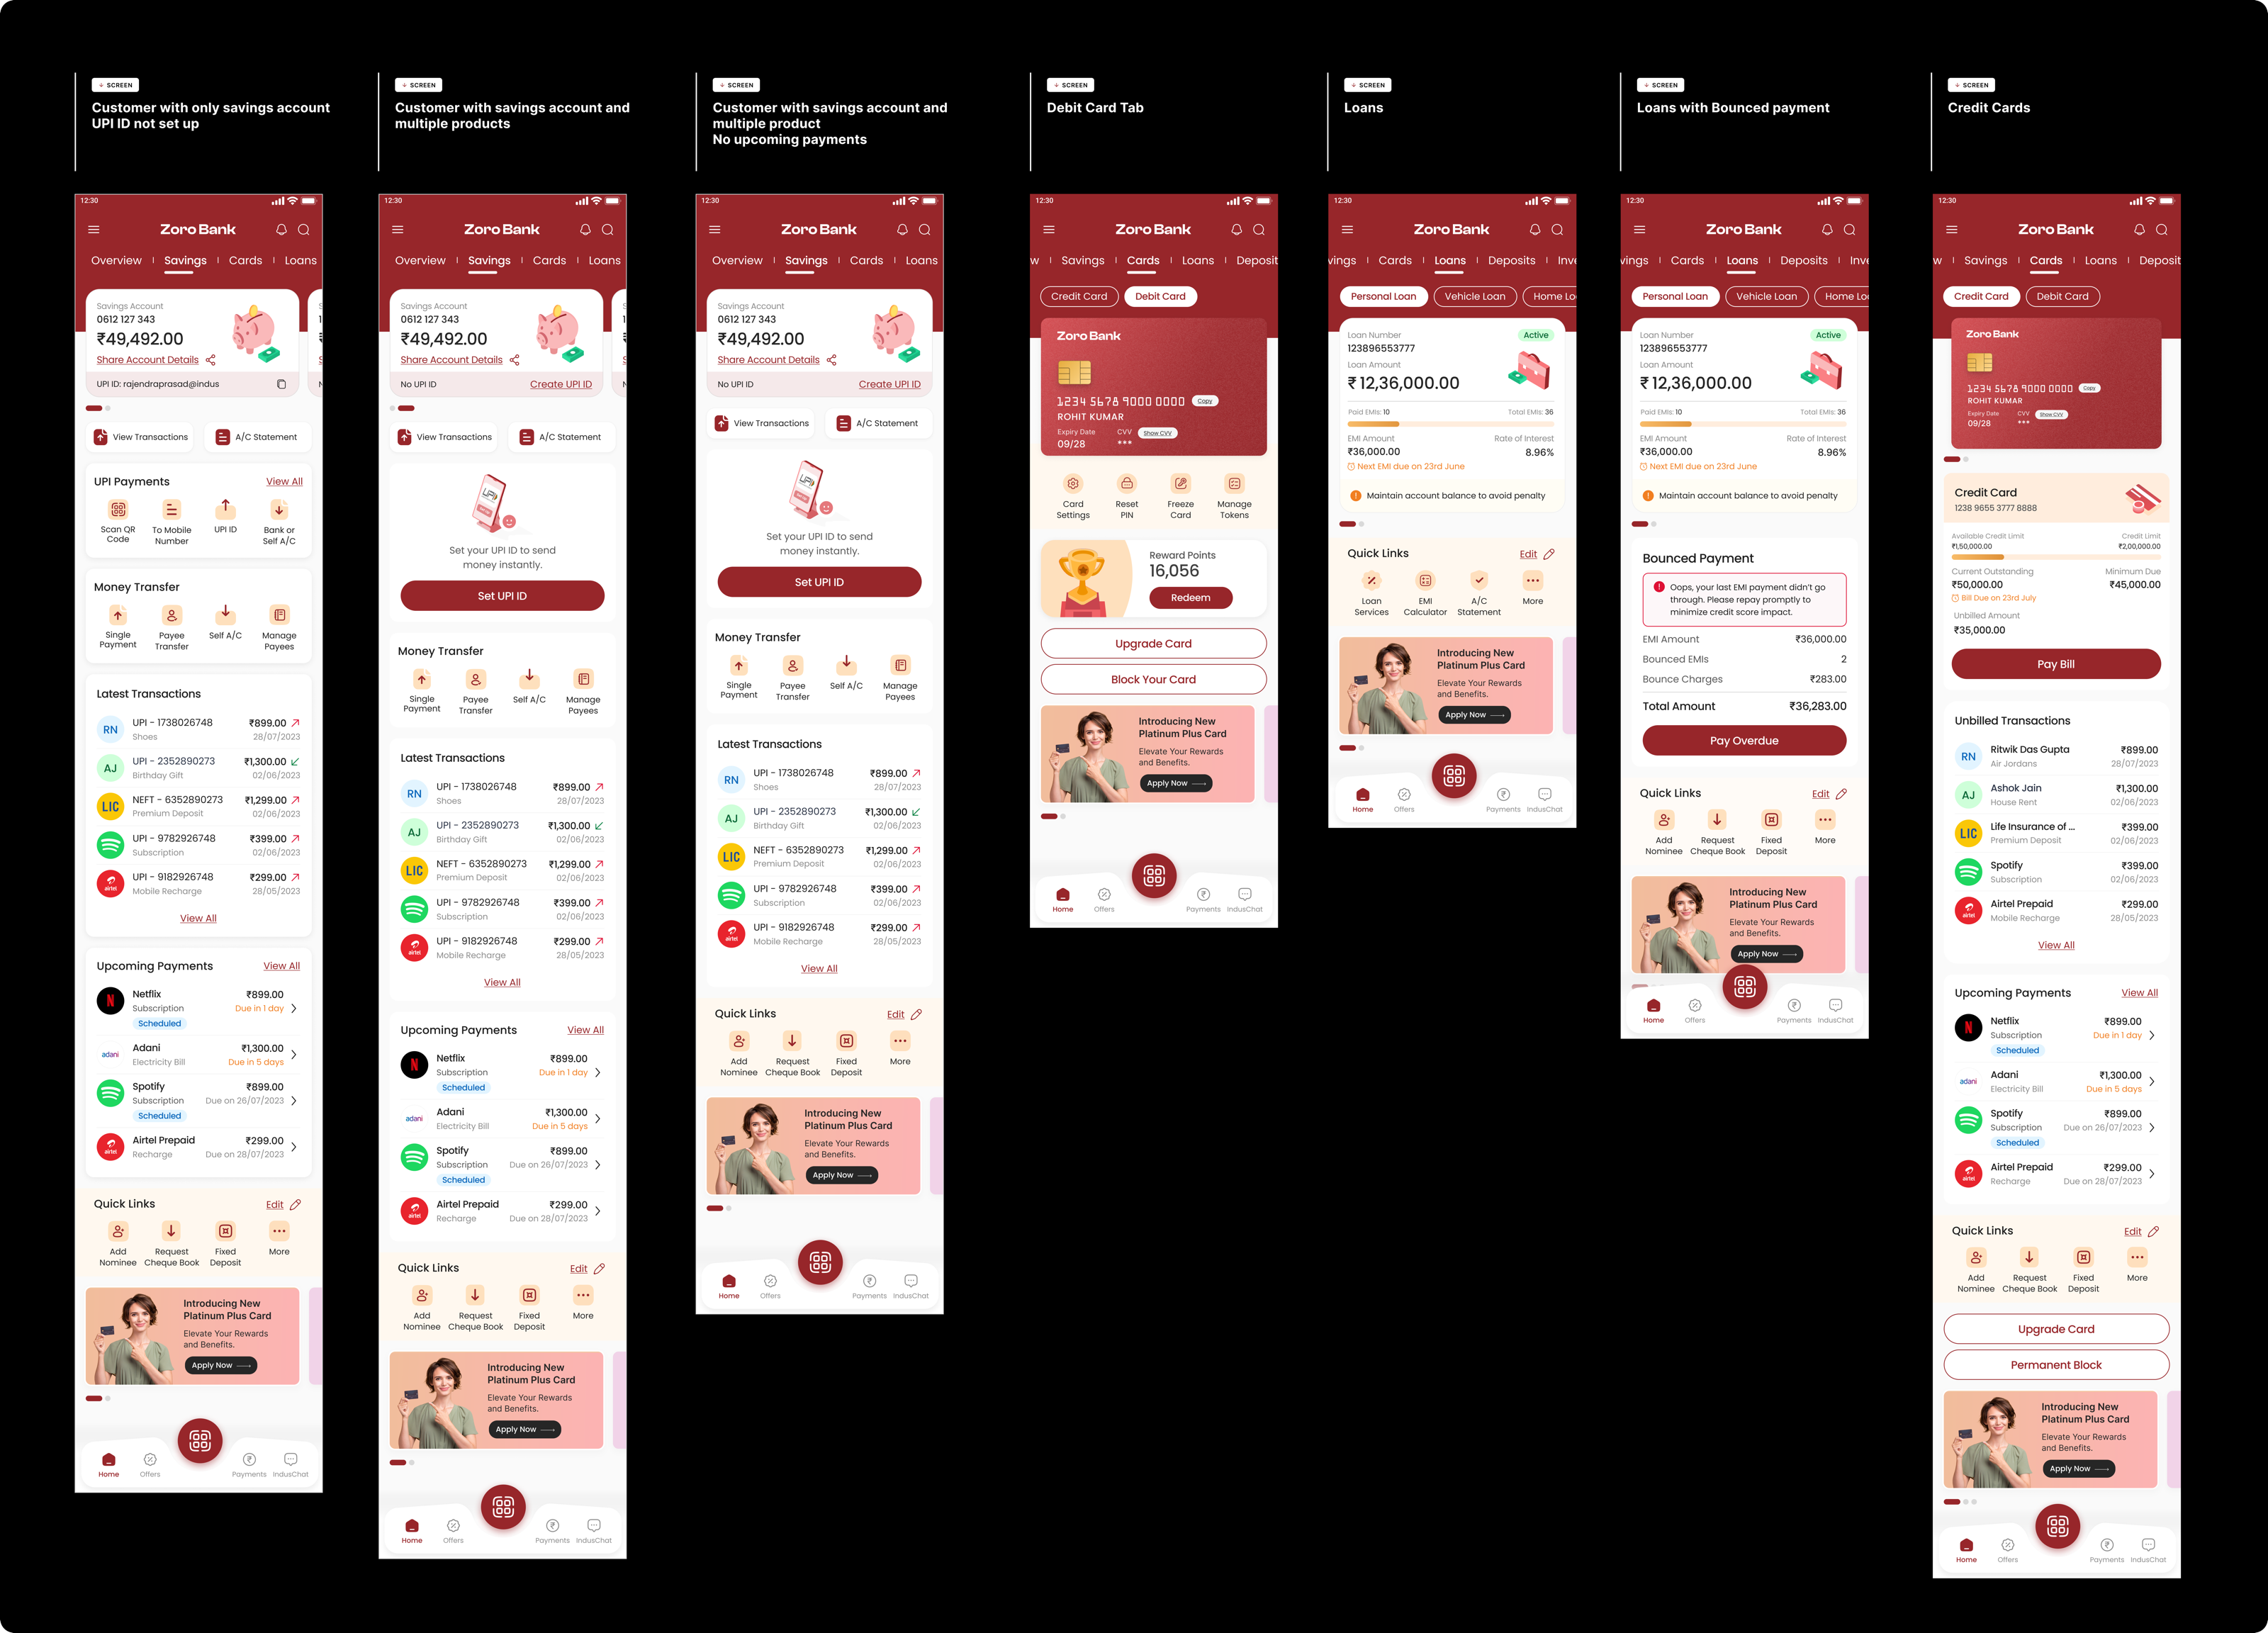
Card controls ranged from everyday settings to actions with permanent financial consequences. Making every action equally prominent could increase visibility, but also the risk of costly mistakes.
The question: How do we make routine card management effortless while keeping consequential actions deliberate?
Not every card action deserves the same treatment.
Instead of organizing controls only by feature type, I assessed them through
frequency, reversibility, and potential consequences.
Have a savings account, credit card and loans as their primary product.
Many customers use cards alongside multiple banking products.
Use net banking as either a primary or secondary method.
Card management needed to work well for both mobile and web users.
Considered dashboard customization important.
Customers wanted the ability to quickly access and manage their cards from the home screen.
Preferred debit card verification for password recovery.
Tangible and familiar verification methods were easier to trust.
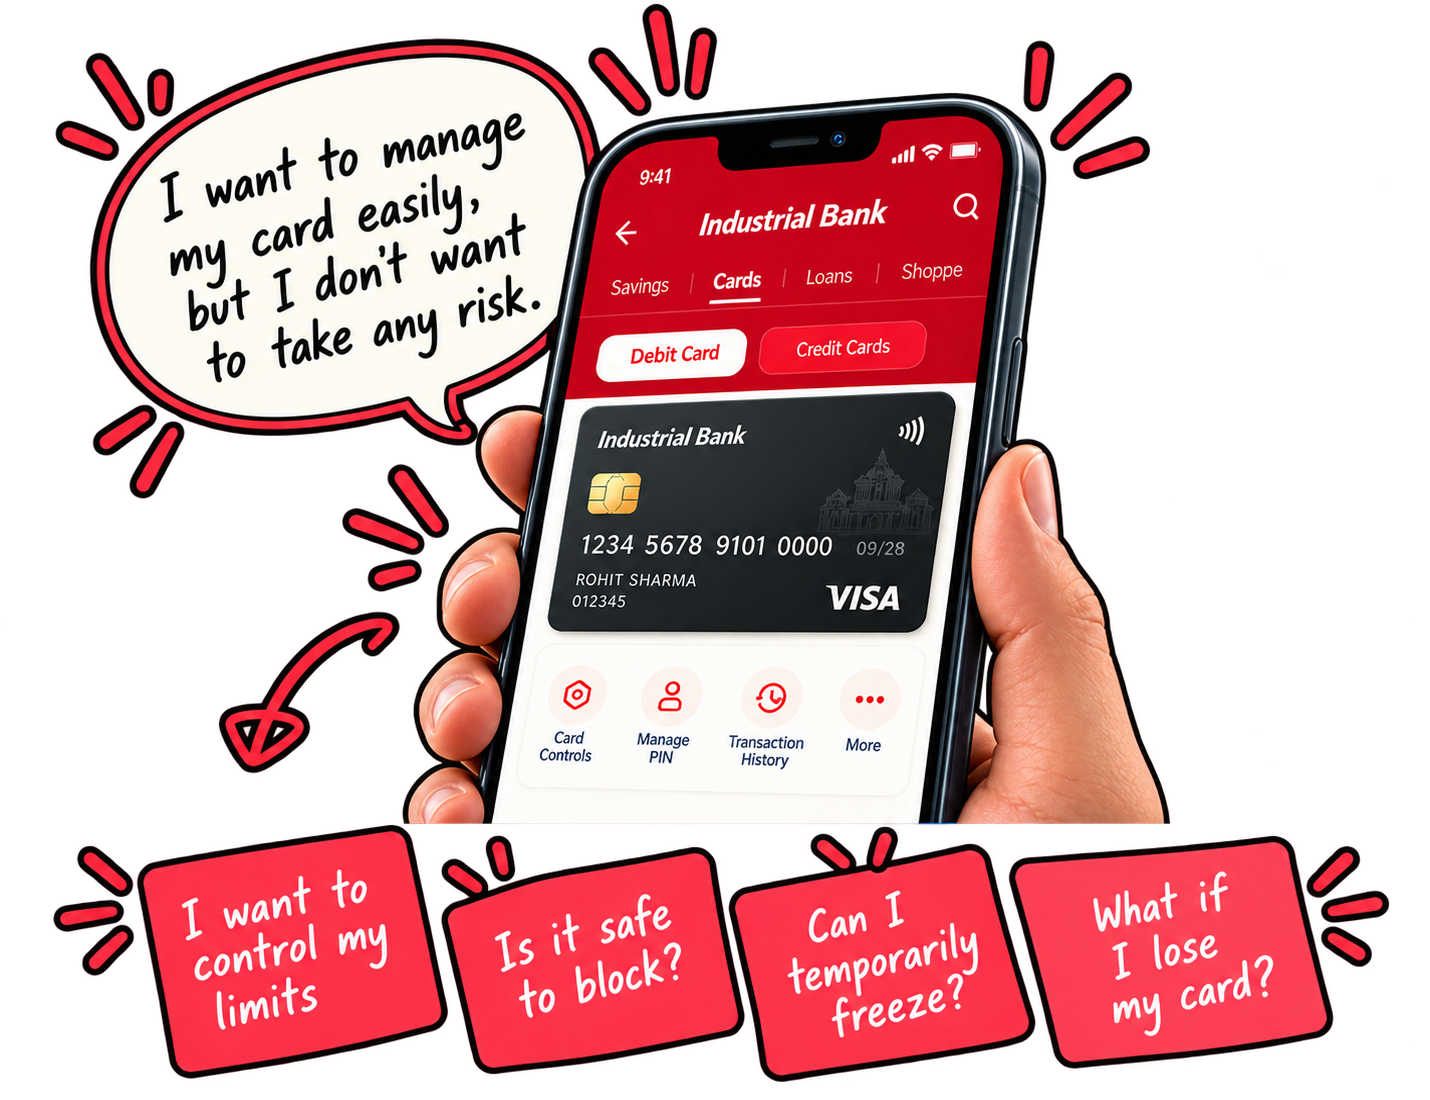
Clear, accessible controls for everyday card management.
We redesigned the card-management section to bring the most important actions upfront, use familiar language, and guide customers with clear feedback and safeguards.
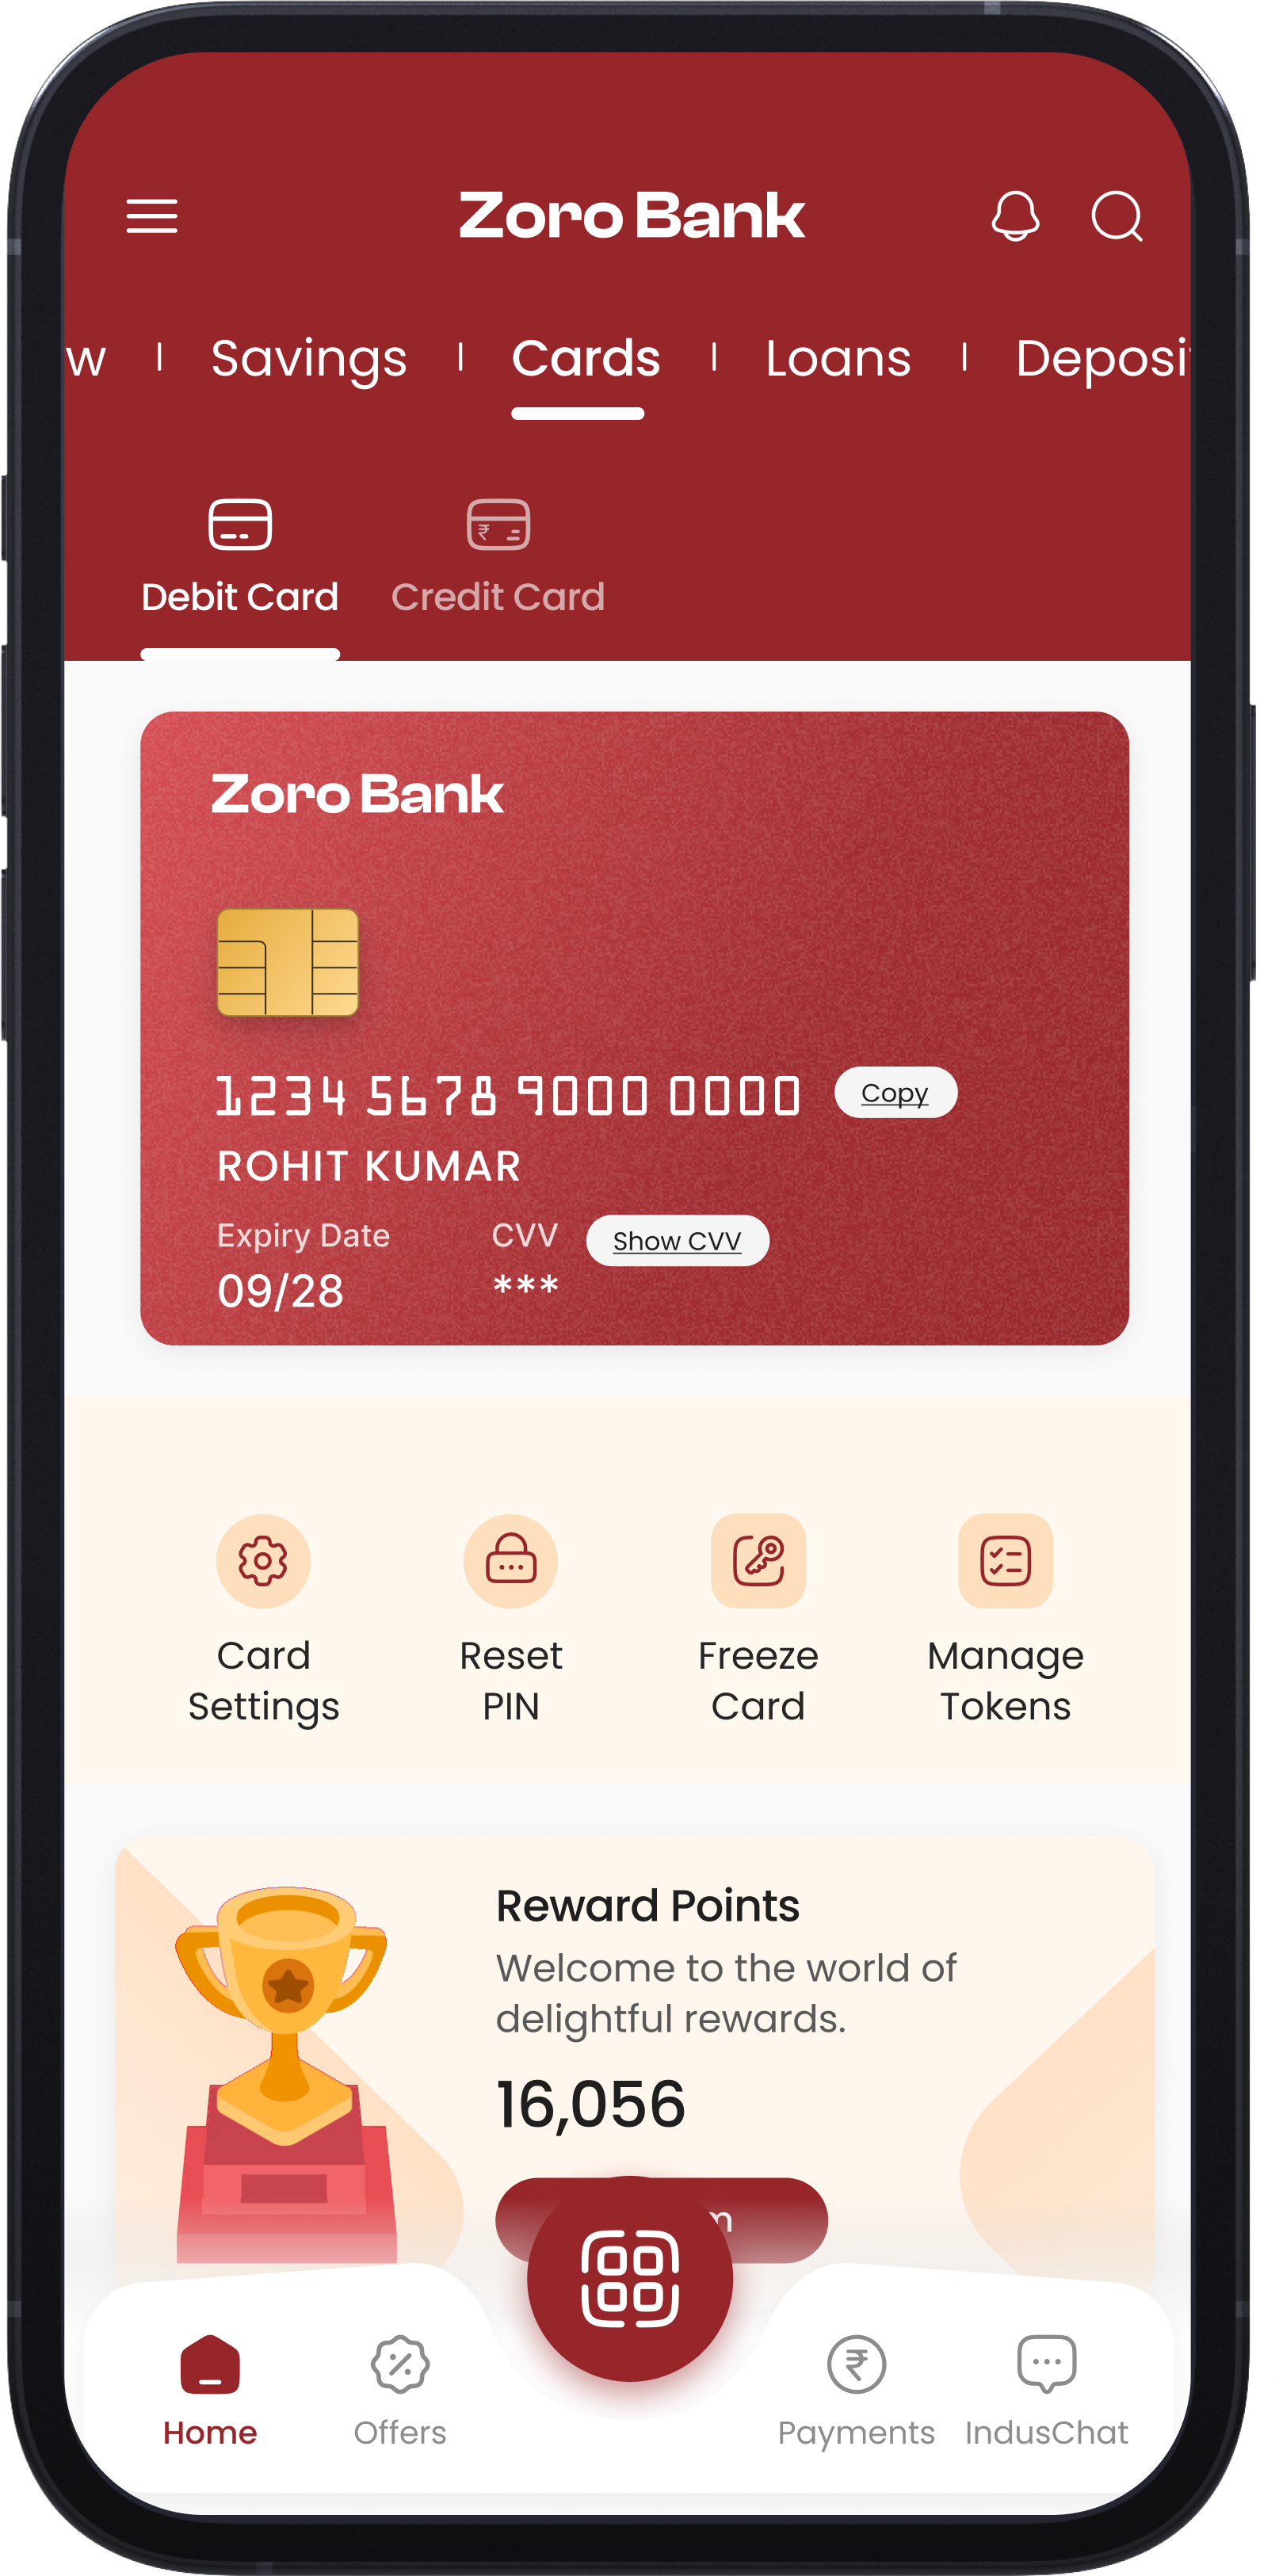
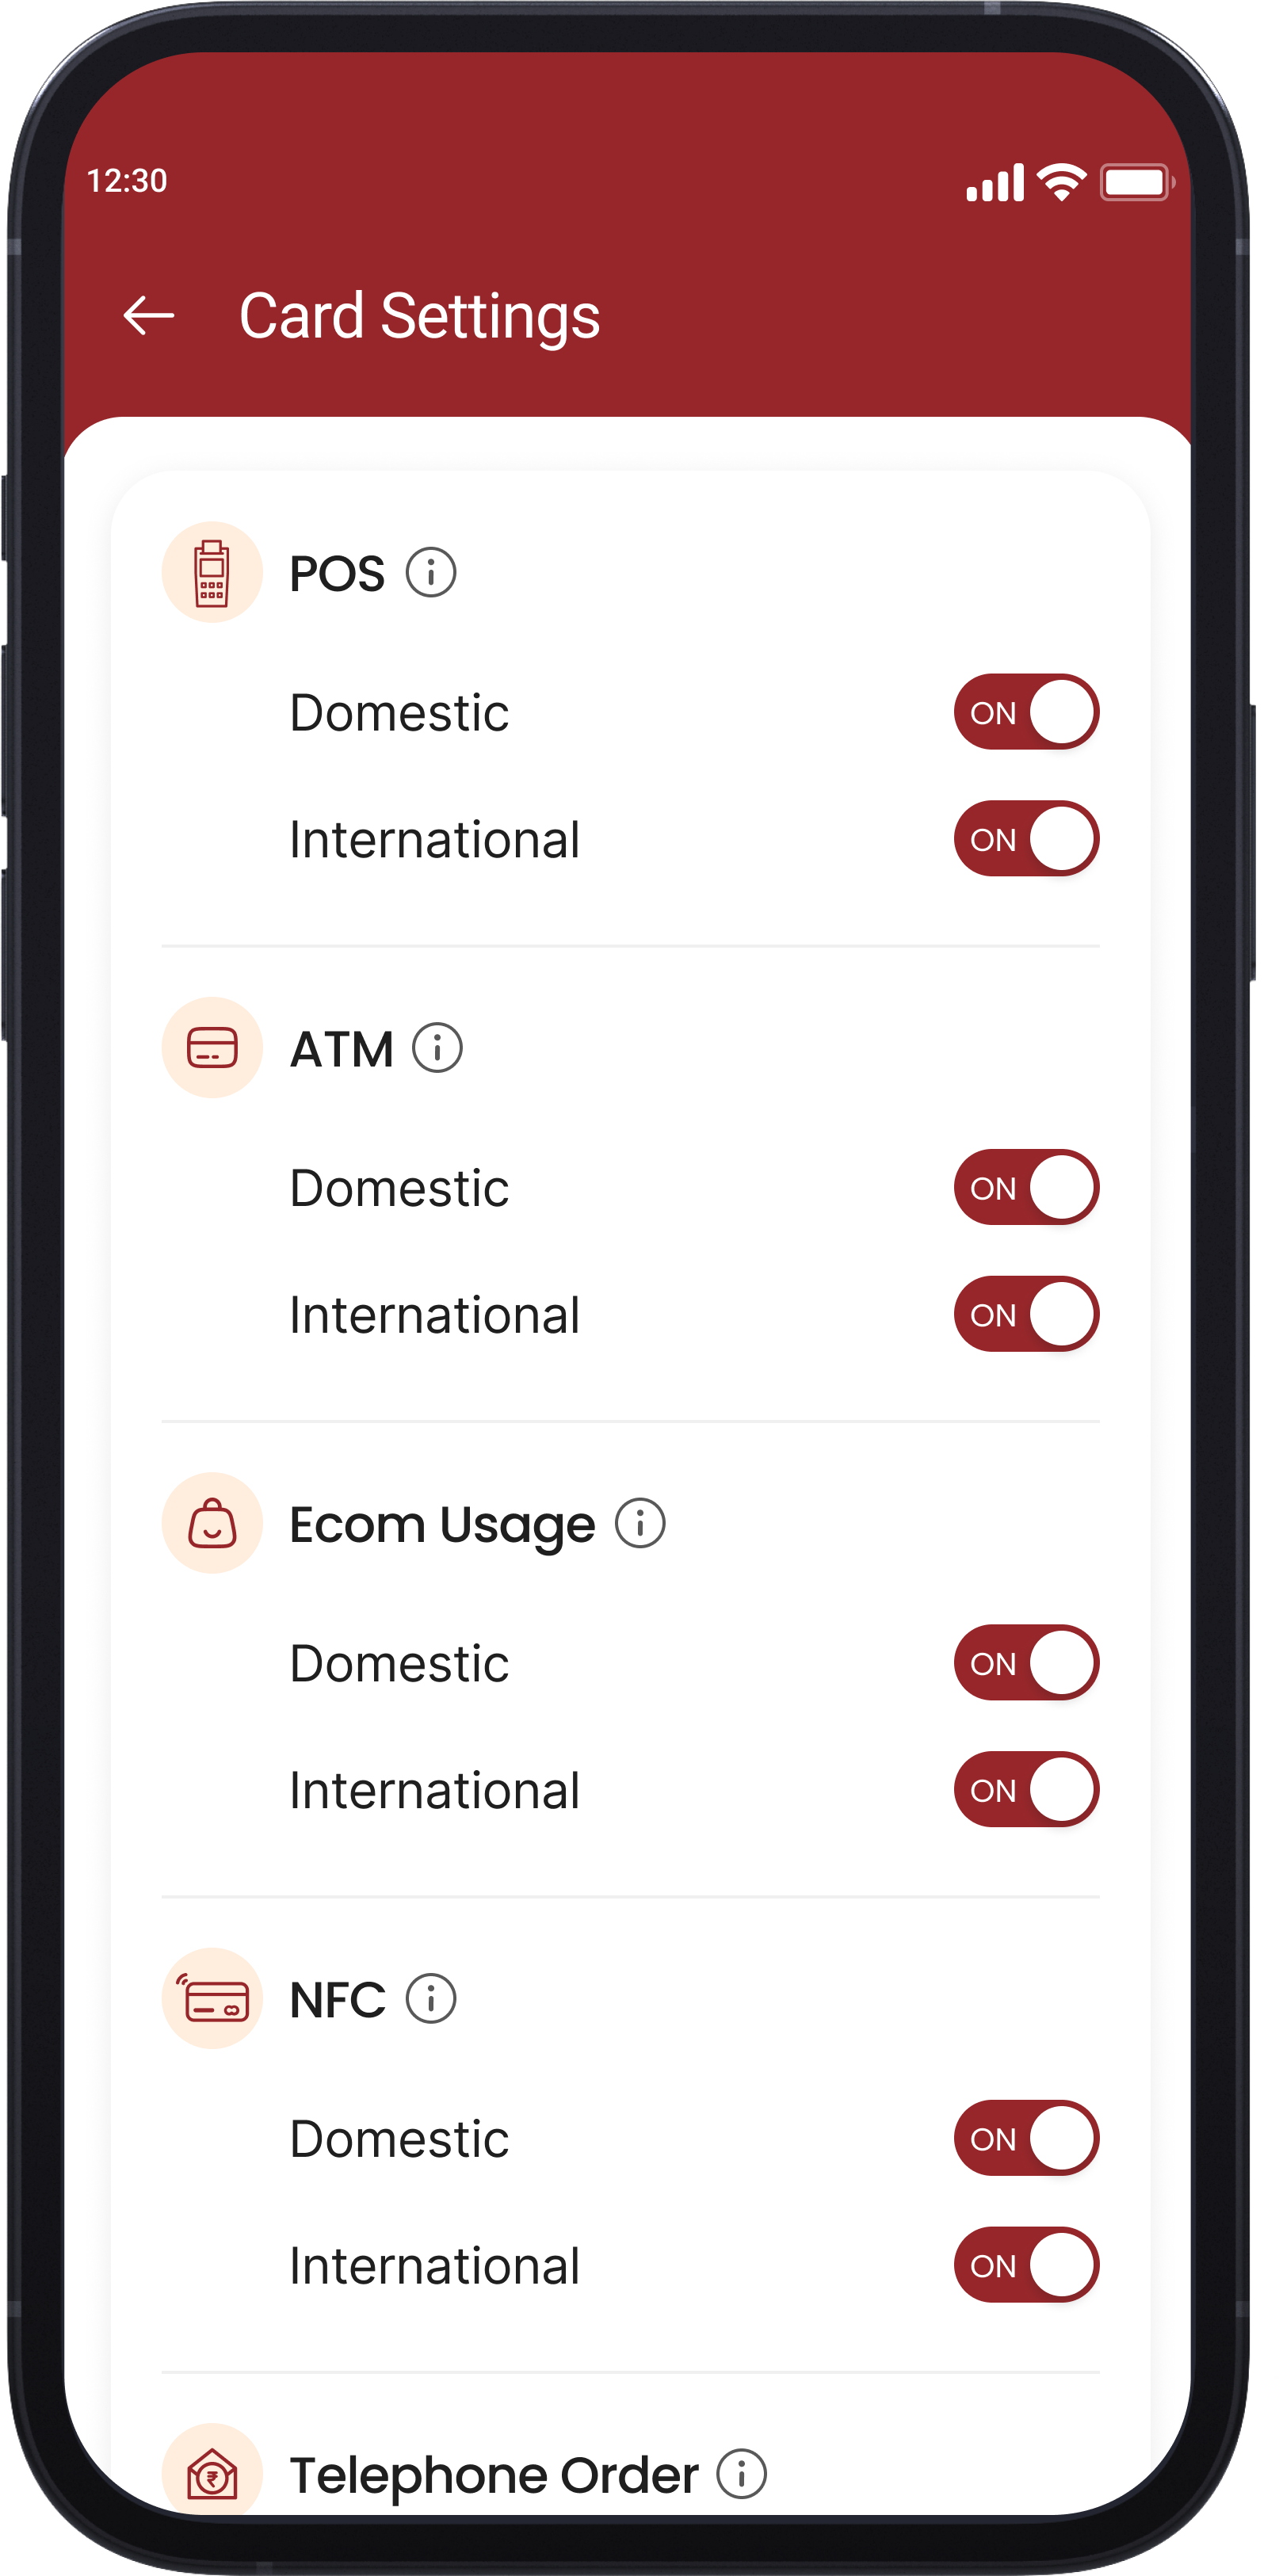
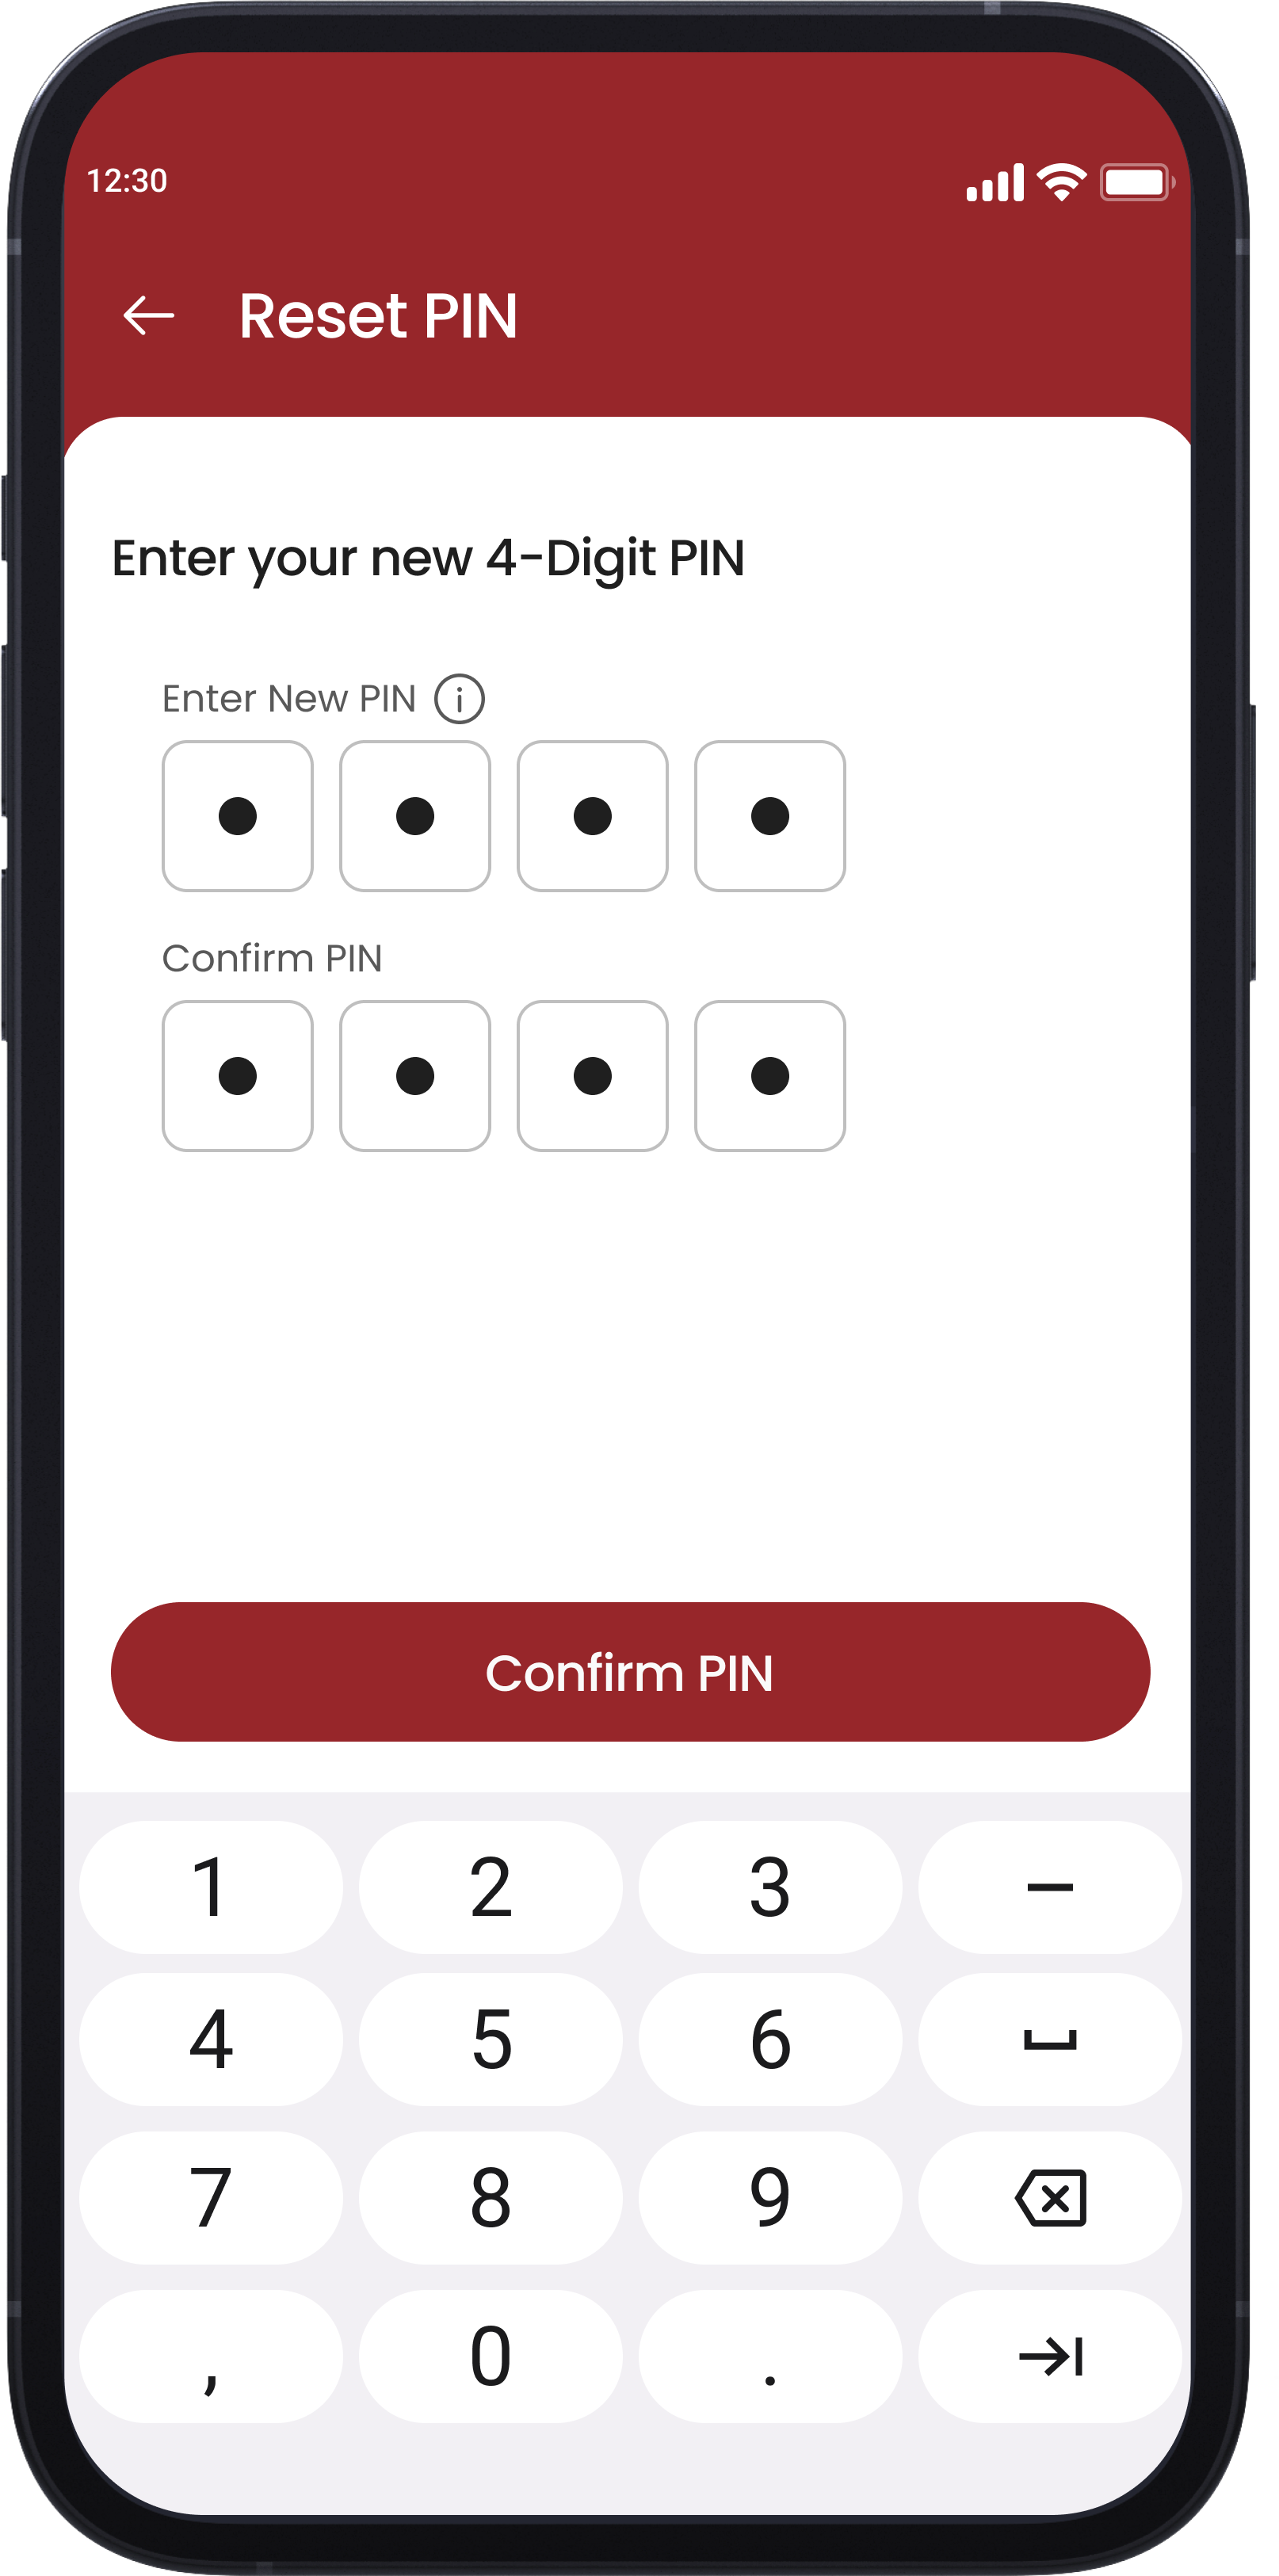
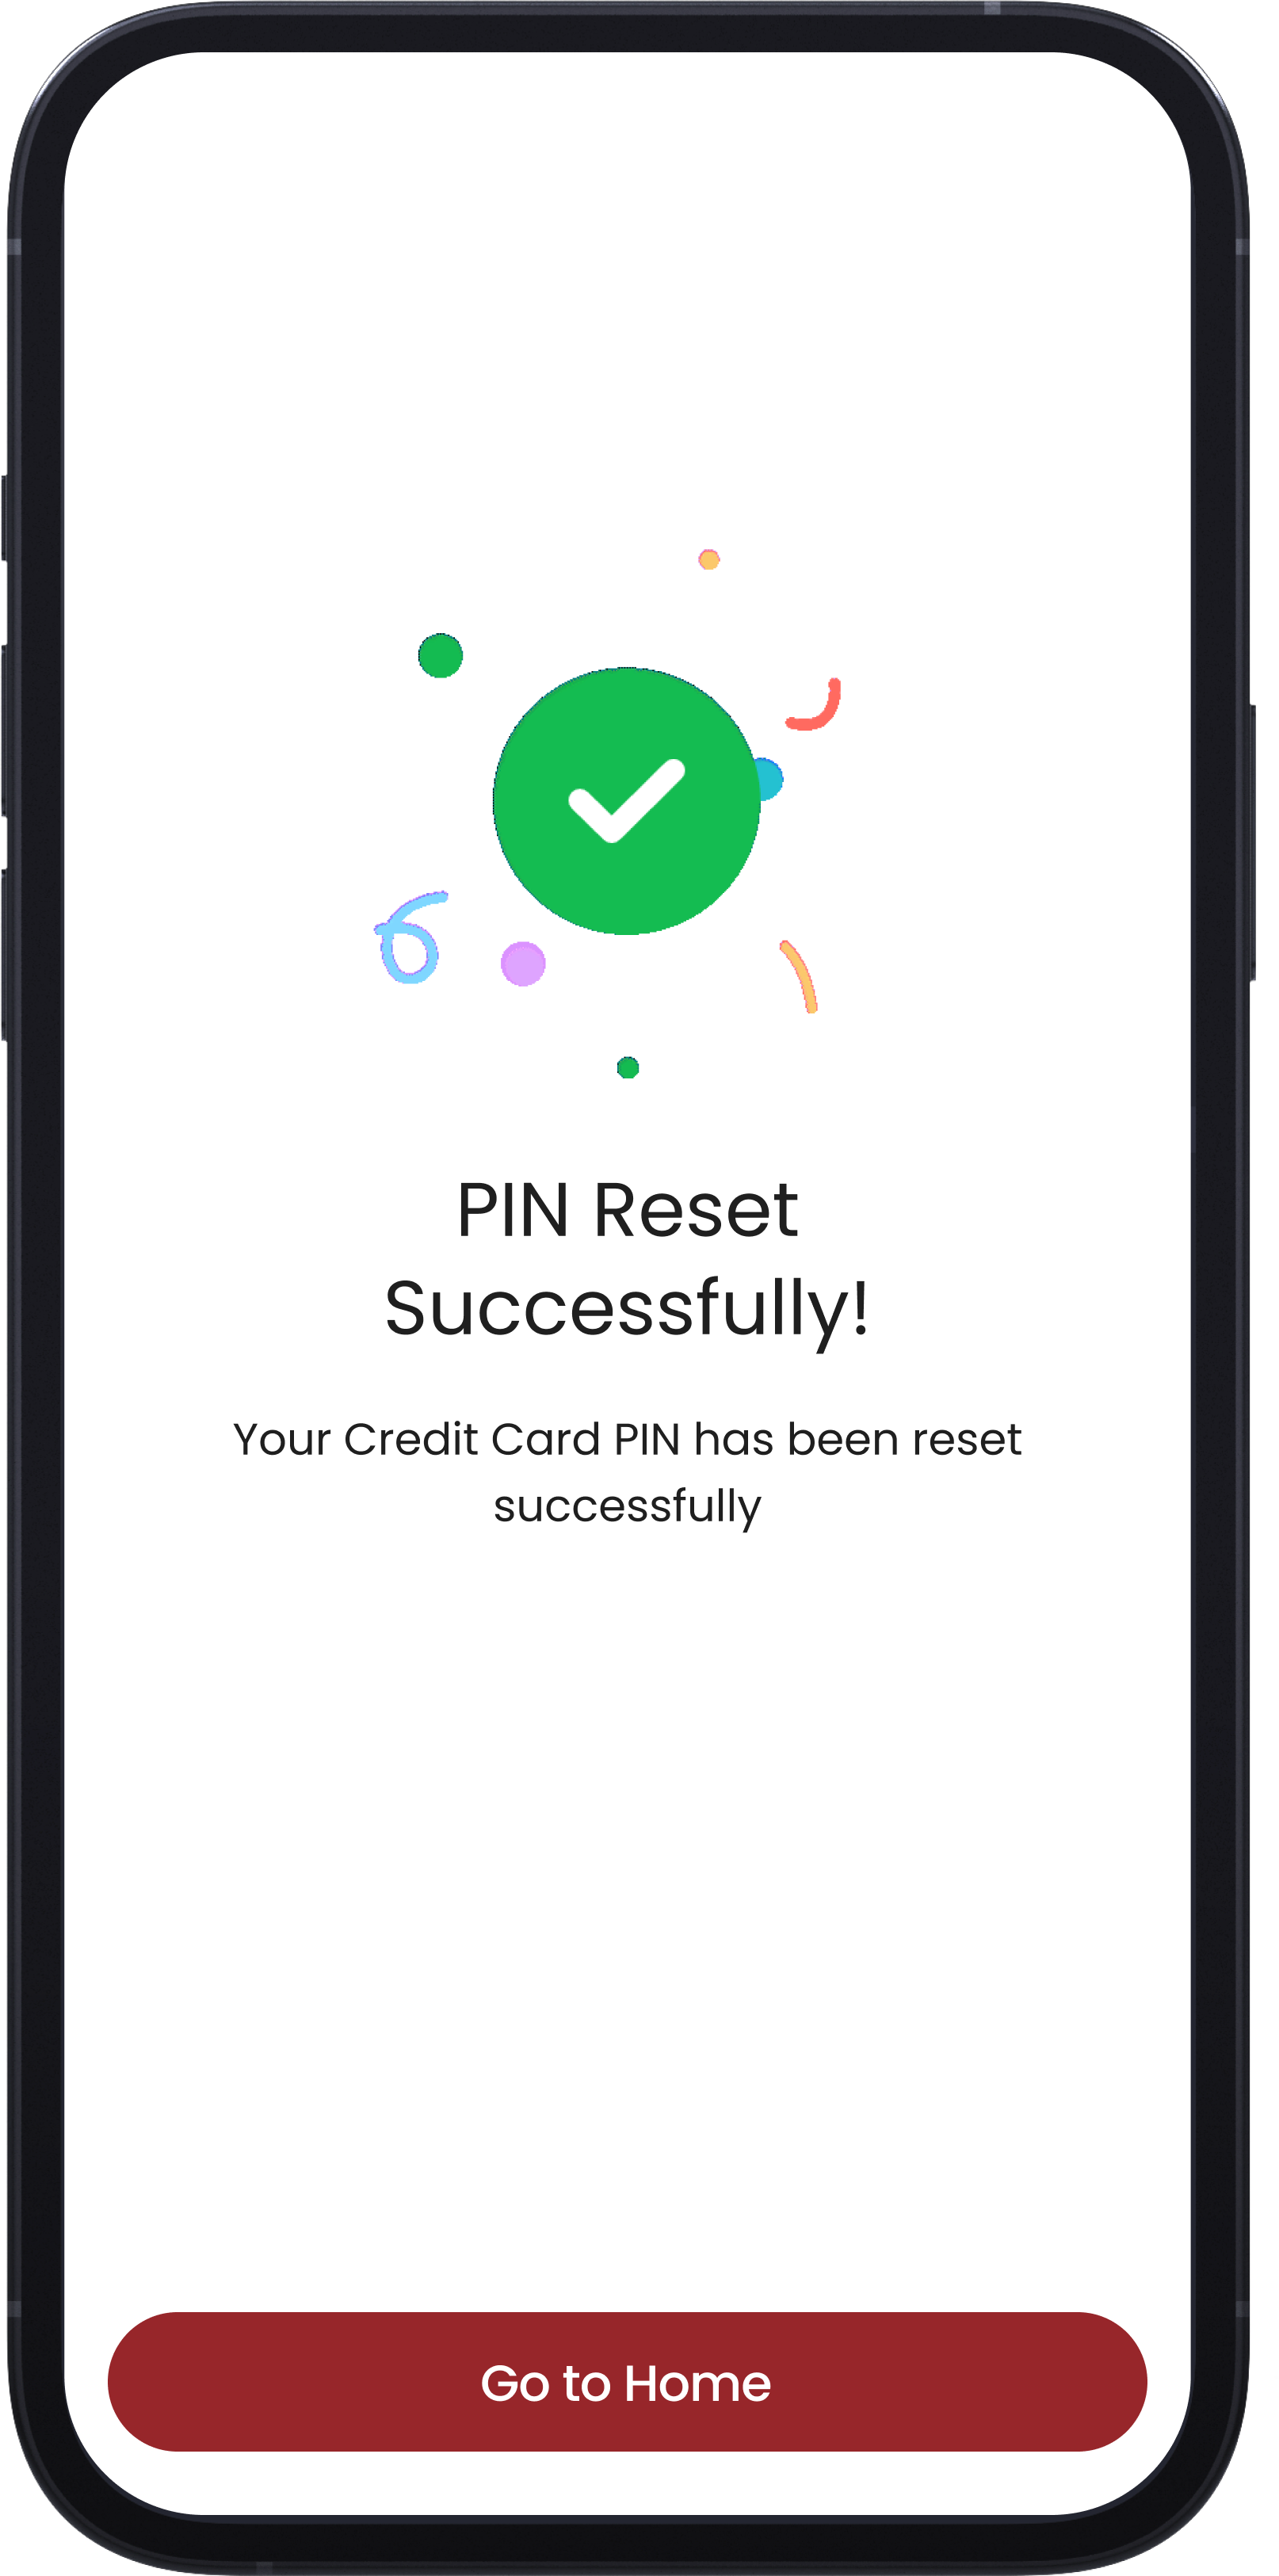
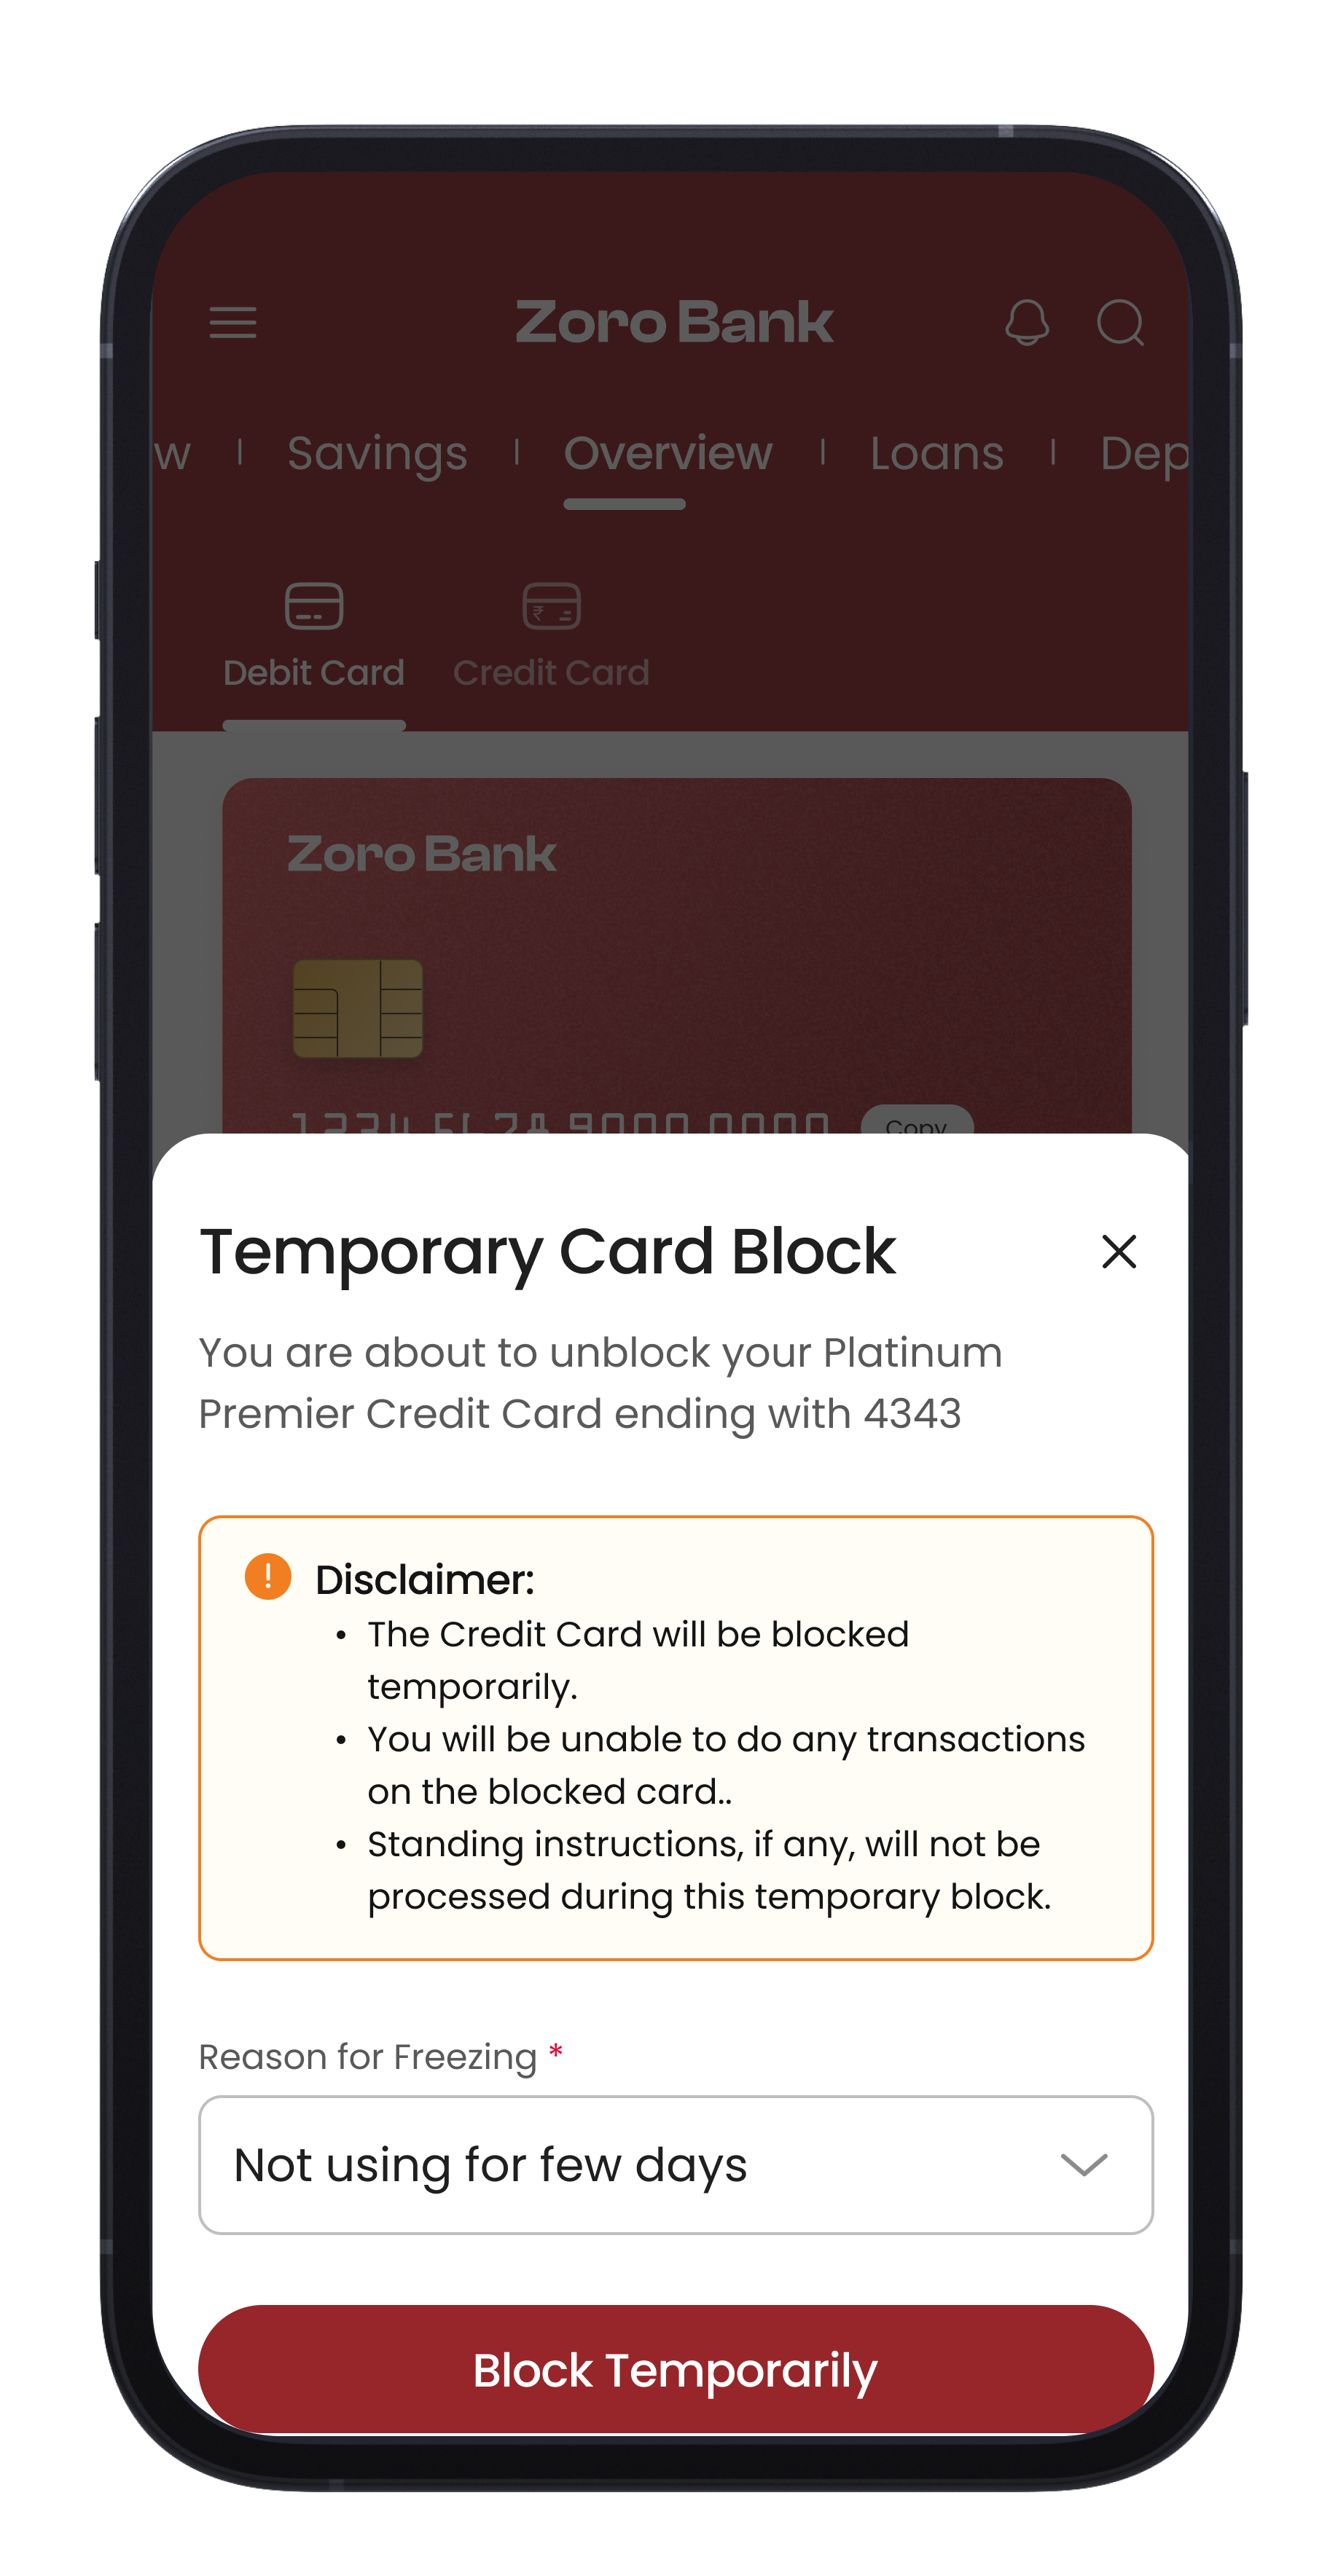
Empowering customers while keeping them safe.
We introduced protective patterns and clear guidance to help customers understand the impact of their actions.
Design principles
Key considerations
Customers could complete key tasks with confidence.
Task-based usability testing with 22 participants highlighted a clear and intuitive experience, with only minor points of confusion.
It's easy to find the option I need. I feel in control and know what each action does.
A card management experience that feels simple, safe and in your control.
05 Dashboard
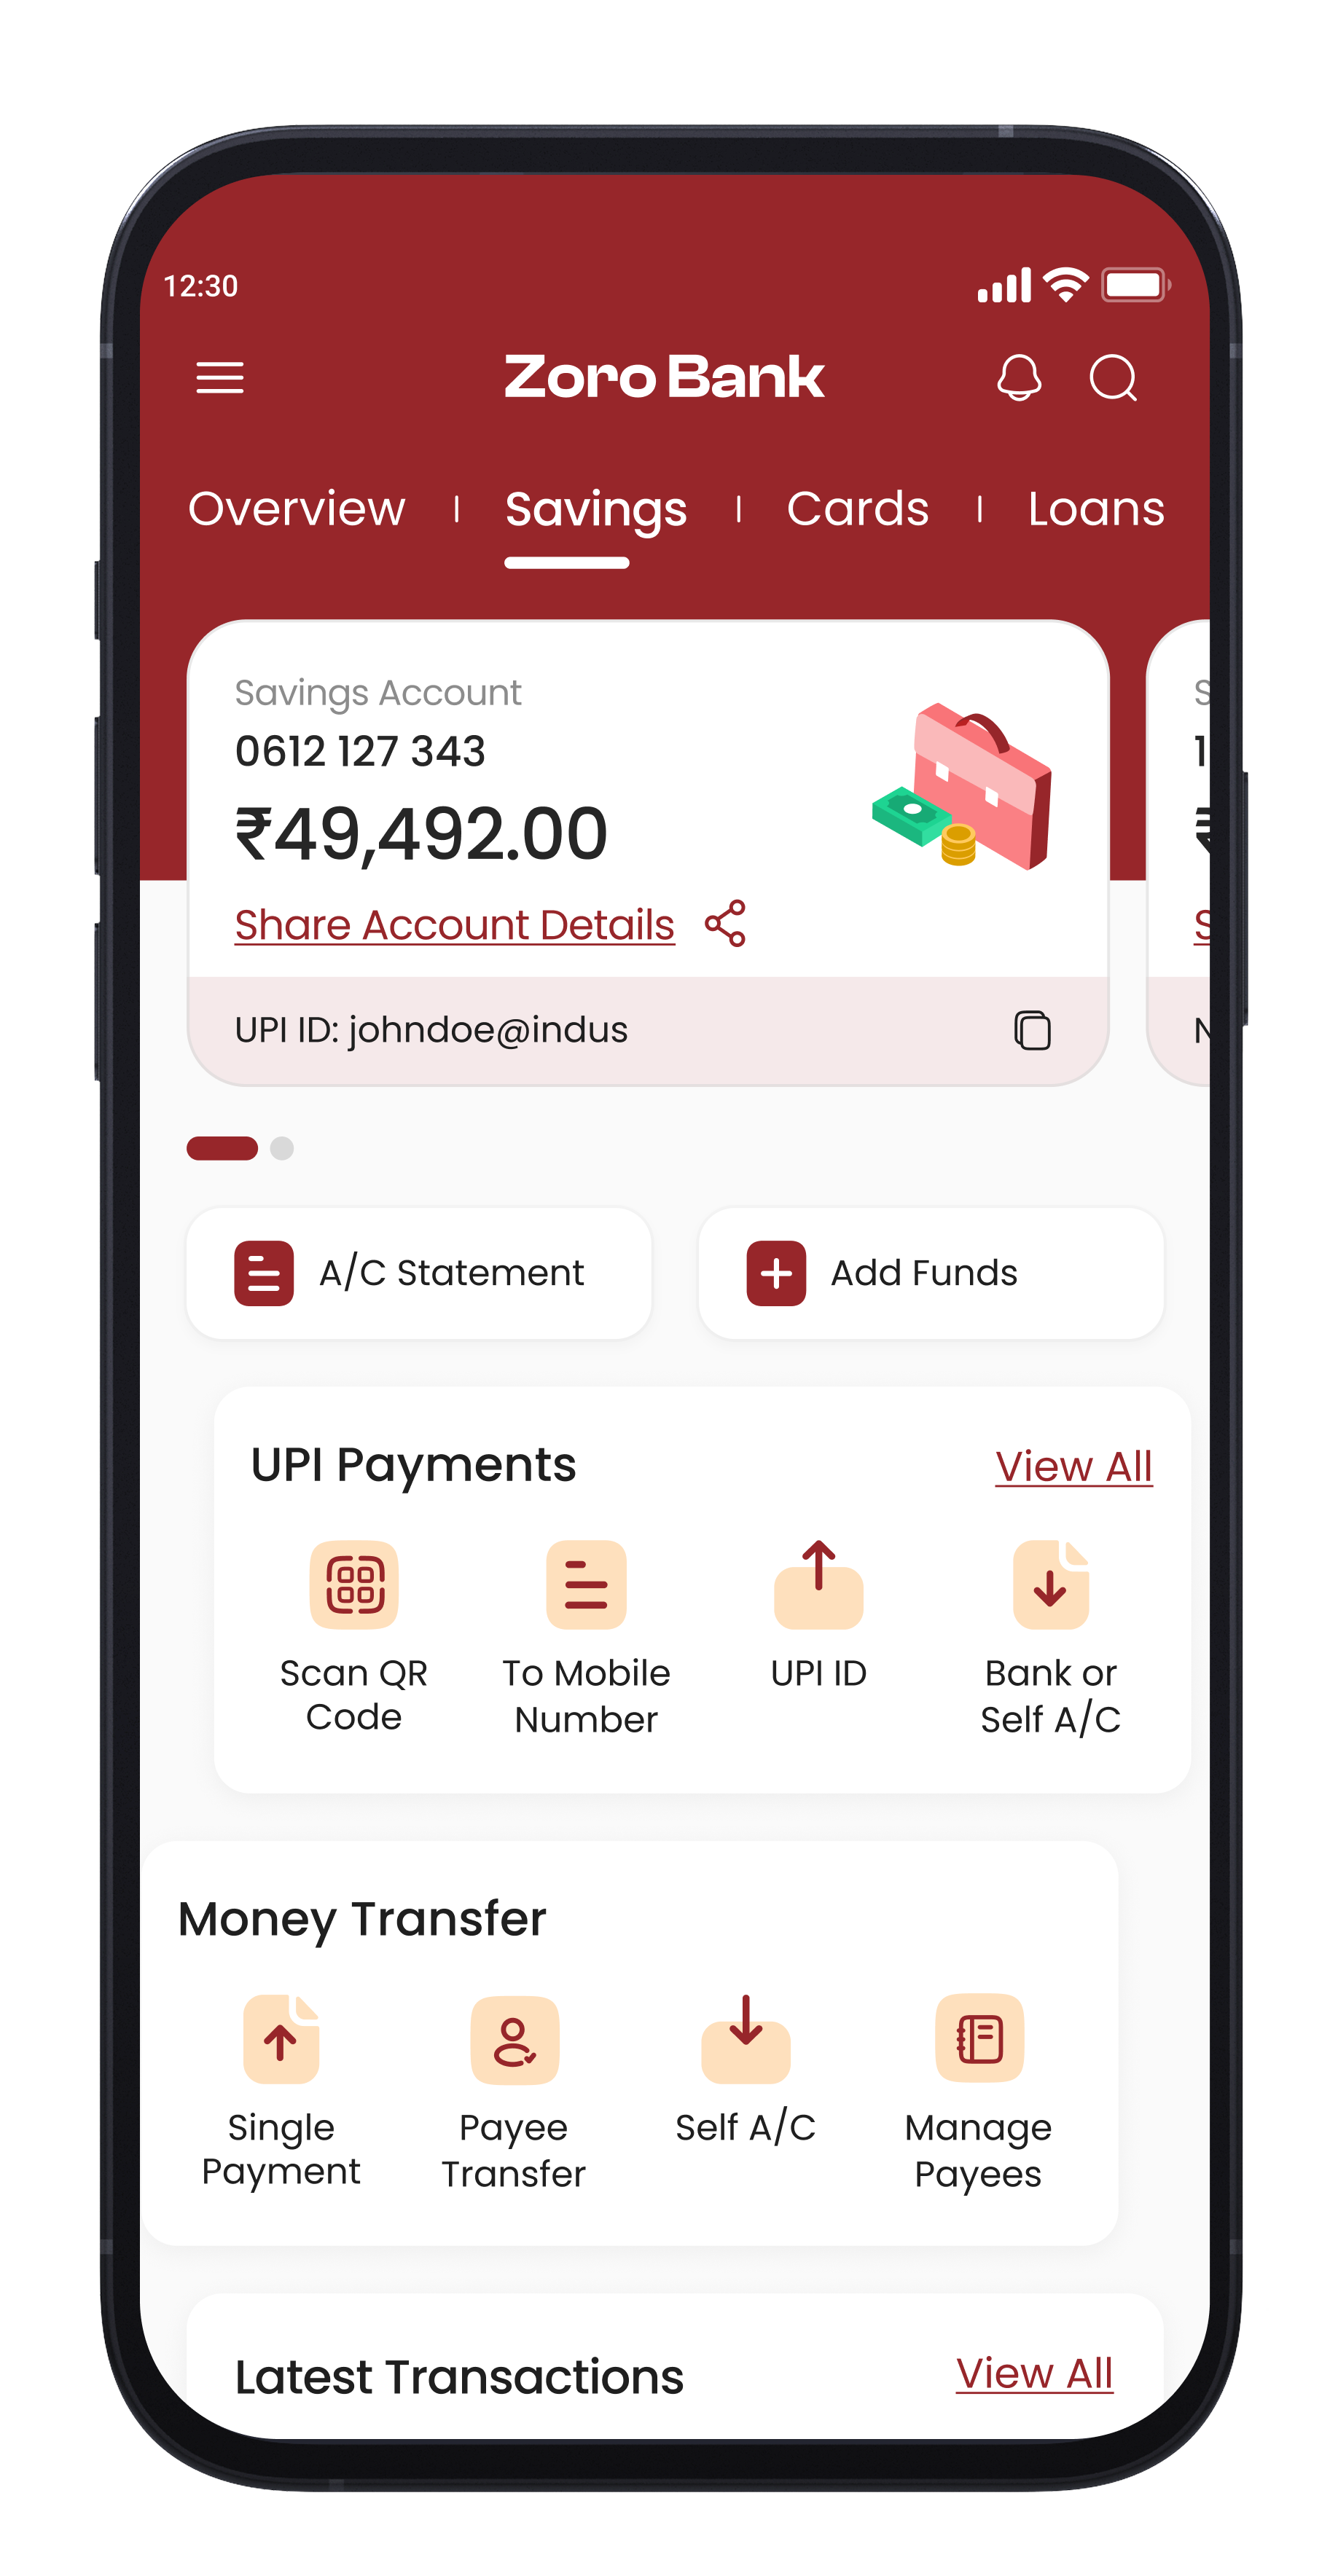
A clearer, more personalised dashboard for everyday banking.
The dashboard is where everything comes together. It needed to give customers a clear overview of their money, quick access to everyday actions, and a personalised experience across multiple banking products — without feeling cluttered or overwhelming.
Customers wanted a simpler and more relevant dashboard.
Insights from 100+ survey responses, 50+ customer interviews, branch research and usability testing.
59% considered dashboard customization important.
Customers wanted the ability to see and manage the information that matters most to them.
Many users felt overwhelmed
The existing dashboard contained too much information and made it difficult to find key actions.
Customers expected quick access
to everyday tasks such as transfers, bill payments and card management.
Enable personalisation and control
Customers wanted personalized dashboards to see what matters most. Give users the ability to customize their experience and manage their information.
A research-led and iterative design process.
We combined customer research, competitive analysis, ideation and multiple design iterations to define and validate the new dashboard experience.
Research & Insights
Competitor analysis, customer research, branch research, customer needs and pain points.
Ideation & Concepting
Explored different ways to organize information, prioritize actions and support personalisation.
Design Iterations
Created and refined multiple low and high fidelity designs based on research insights.
Usability Testing
Tested key journeys with customers to validate the design and identify areas for improvement.
Final Design
Delivered a clean, intuitive and personalised dashboard experience for web and mobile.
A personalised, easy-to-navigate dashboard.
to key actions
at a glance
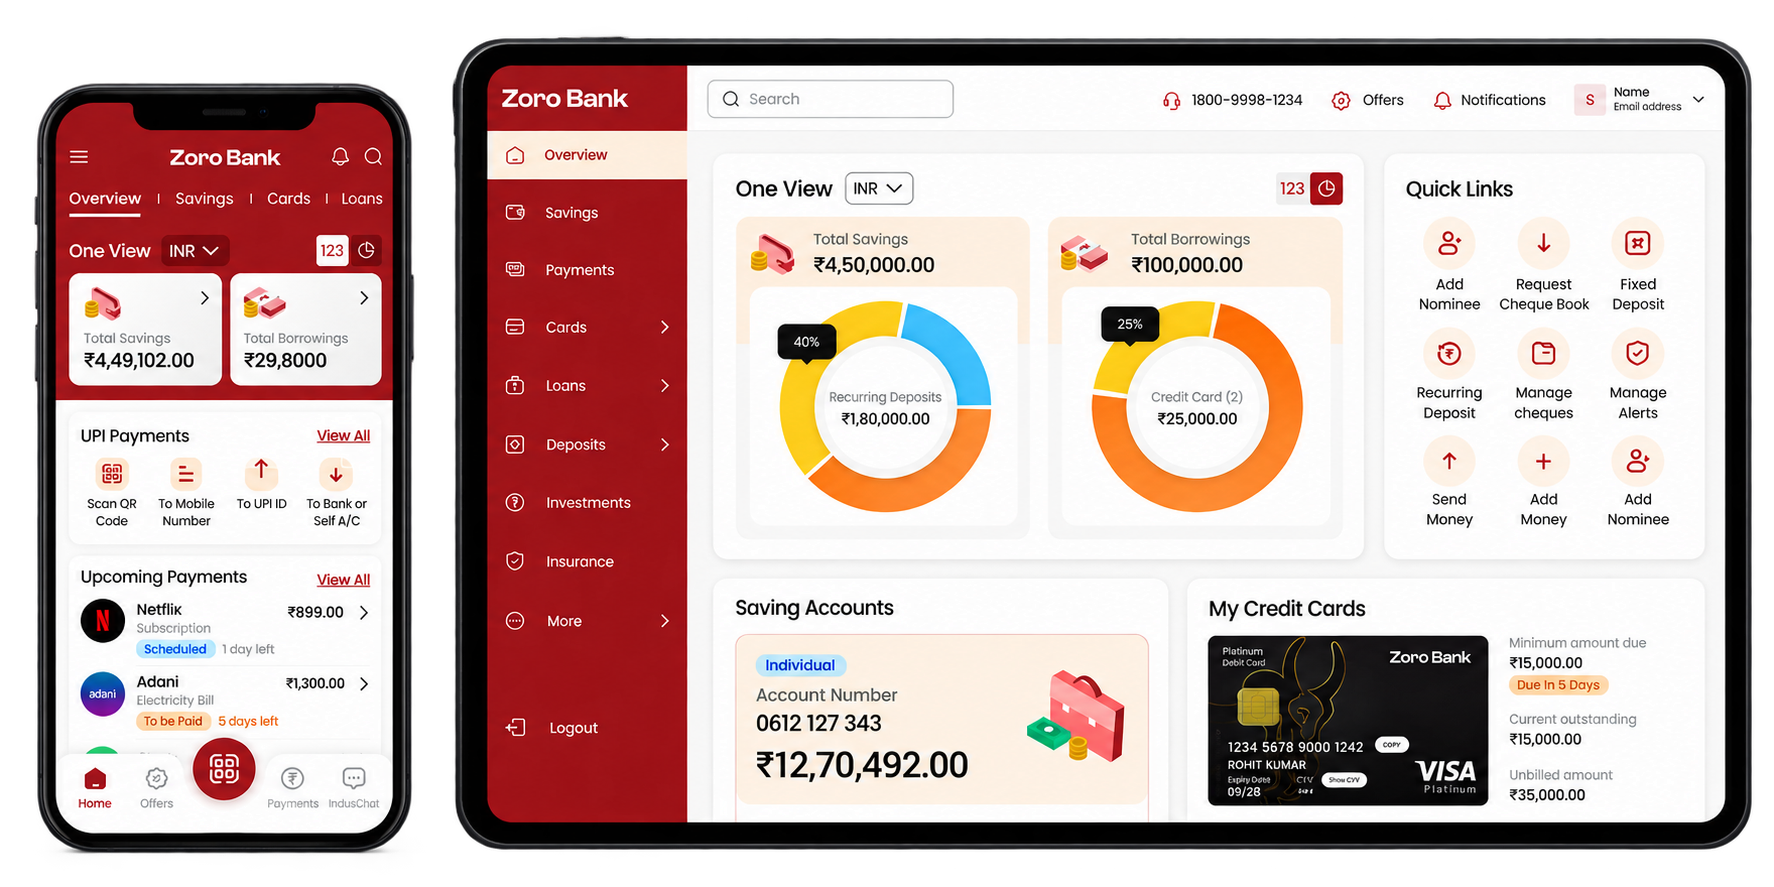
of finances
recommendations
everyday tasks
A clearer and more intuitive dashboard experience.
Usability testing with 22 participants showed that the new dashboard was easy to navigate, helped customers find important information quickly, and felt more relevant to their needs.
completed key dashboard tasks successfully.
average ease rating.
found it easy to locate important information and actions.
The new dashboard feels a lot cleaner and easier to use. I can see what I need and access things quickly.
A dashboard that gives customers control and confidence.
Clearer overview
A simplified layout that highlights what matters most.
Personalised experience
Flexible components to show relevant products and actions.
Faster access
Quick and easy access to everyday tasks like transfers, bill payments and card management.
Greater confidence
A cleaner, more intuitive experience that helps customers feel in control of their money.
06 System & Delivery
Designing for the platform, not just individual screens.
Authentication, card management, and the dashboard could not operate as isolated experiences. The work had to connect into a broader banking system, communicate clearly in high-anxiety moments, and hold up through implementation.
Connecting the wider banking ecosystem.
I created a unified information architecture to ensure a consistent and scalable experience across all key product areas, with clear relationships, shared patterns, and room for future growth.
- Transfers
- UPI Payments
- Bill Payments
- Transaction History
- Savings Account
- Goals
- Auto-save
- Recurring Deposits
- Debit Cards
- Credit Cards
- Card Controls
- Rewards & Offers
- Personal Loans
- Loan Offers
- Repayments
- Eligibility & Status
- Mutual Funds
- Digital Gold
- Bonds
- Portfolio
- Fixed Deposits
- Recurring Deposits
- Manage & Renew
- Interest & Maturity
- Health Insurance
- Life Insurance
- Motor Insurance
- Travel Insurance
- Authentication
- Profile & Settings
- Help & Support
- Notifications
Authentication entry points and recovery paths.
Designed sign in, verification and account recovery across the platform.
Debit and credit-card hierarchy.
Structured how different card types are presented and organised.
Navigation between card types.
Defined clear pathways between debit, credit and additional card products.
Placement and depth of different card controls.
Determined what controls are surfaced, and how deep settings are organised.
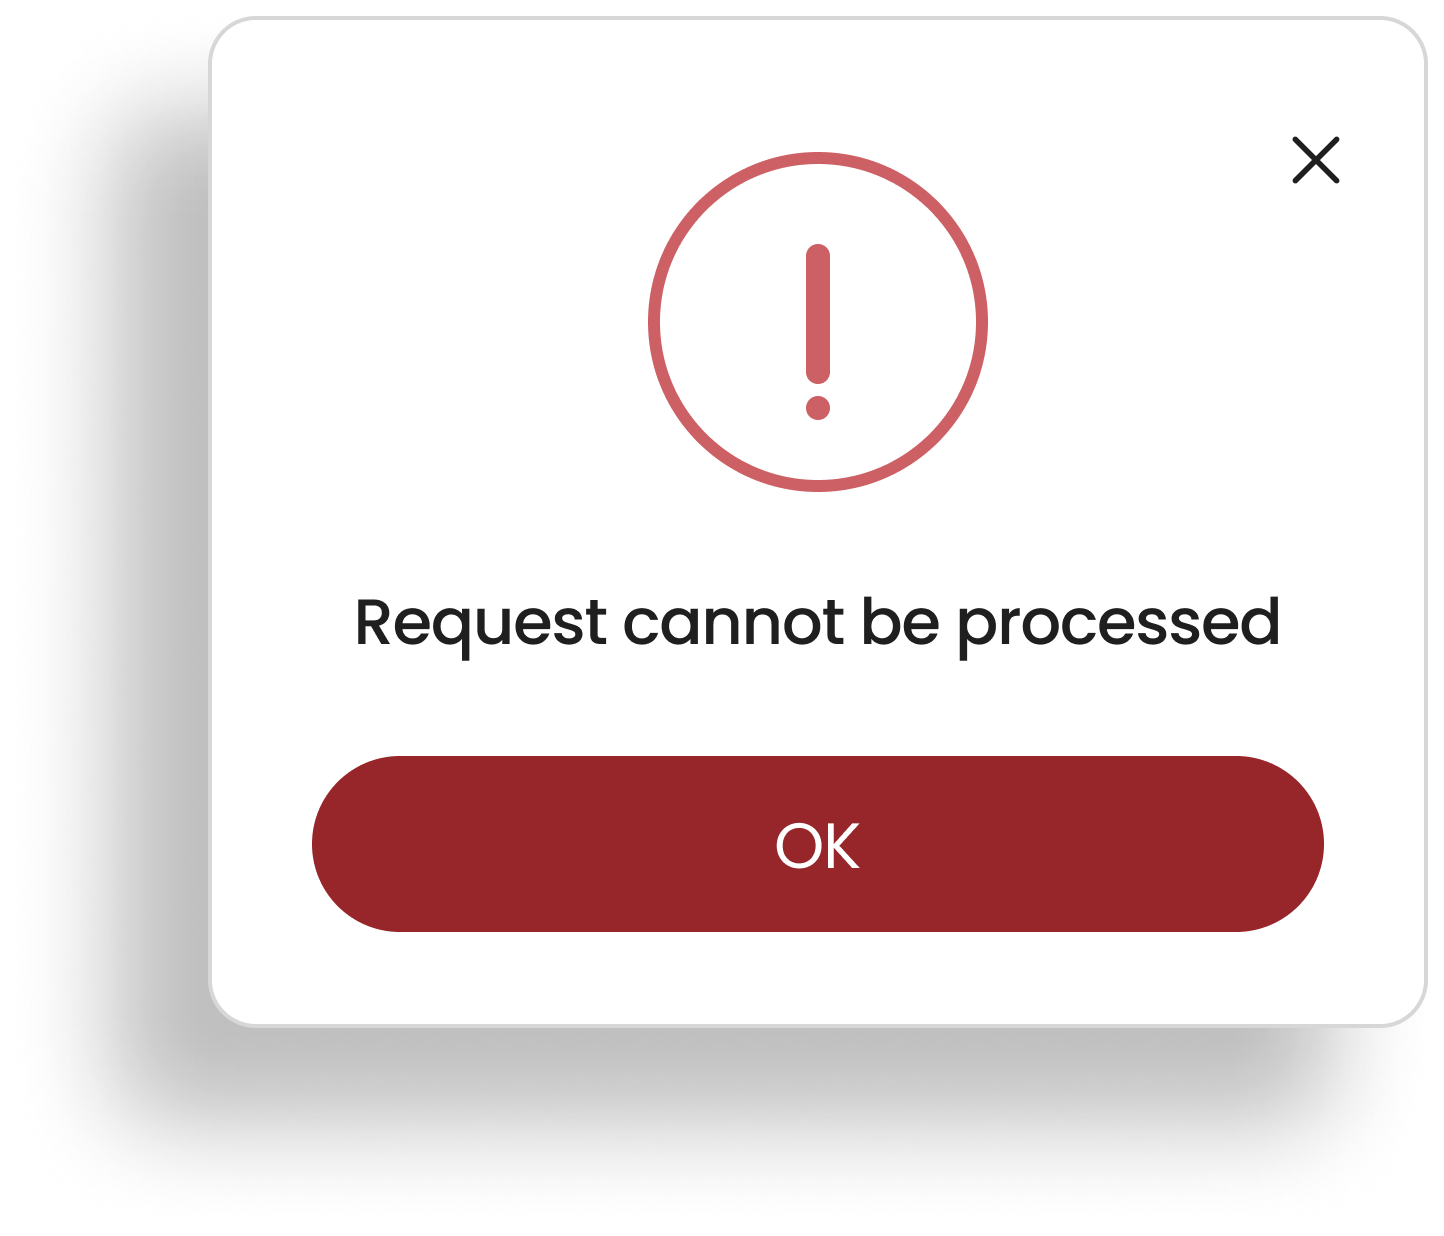
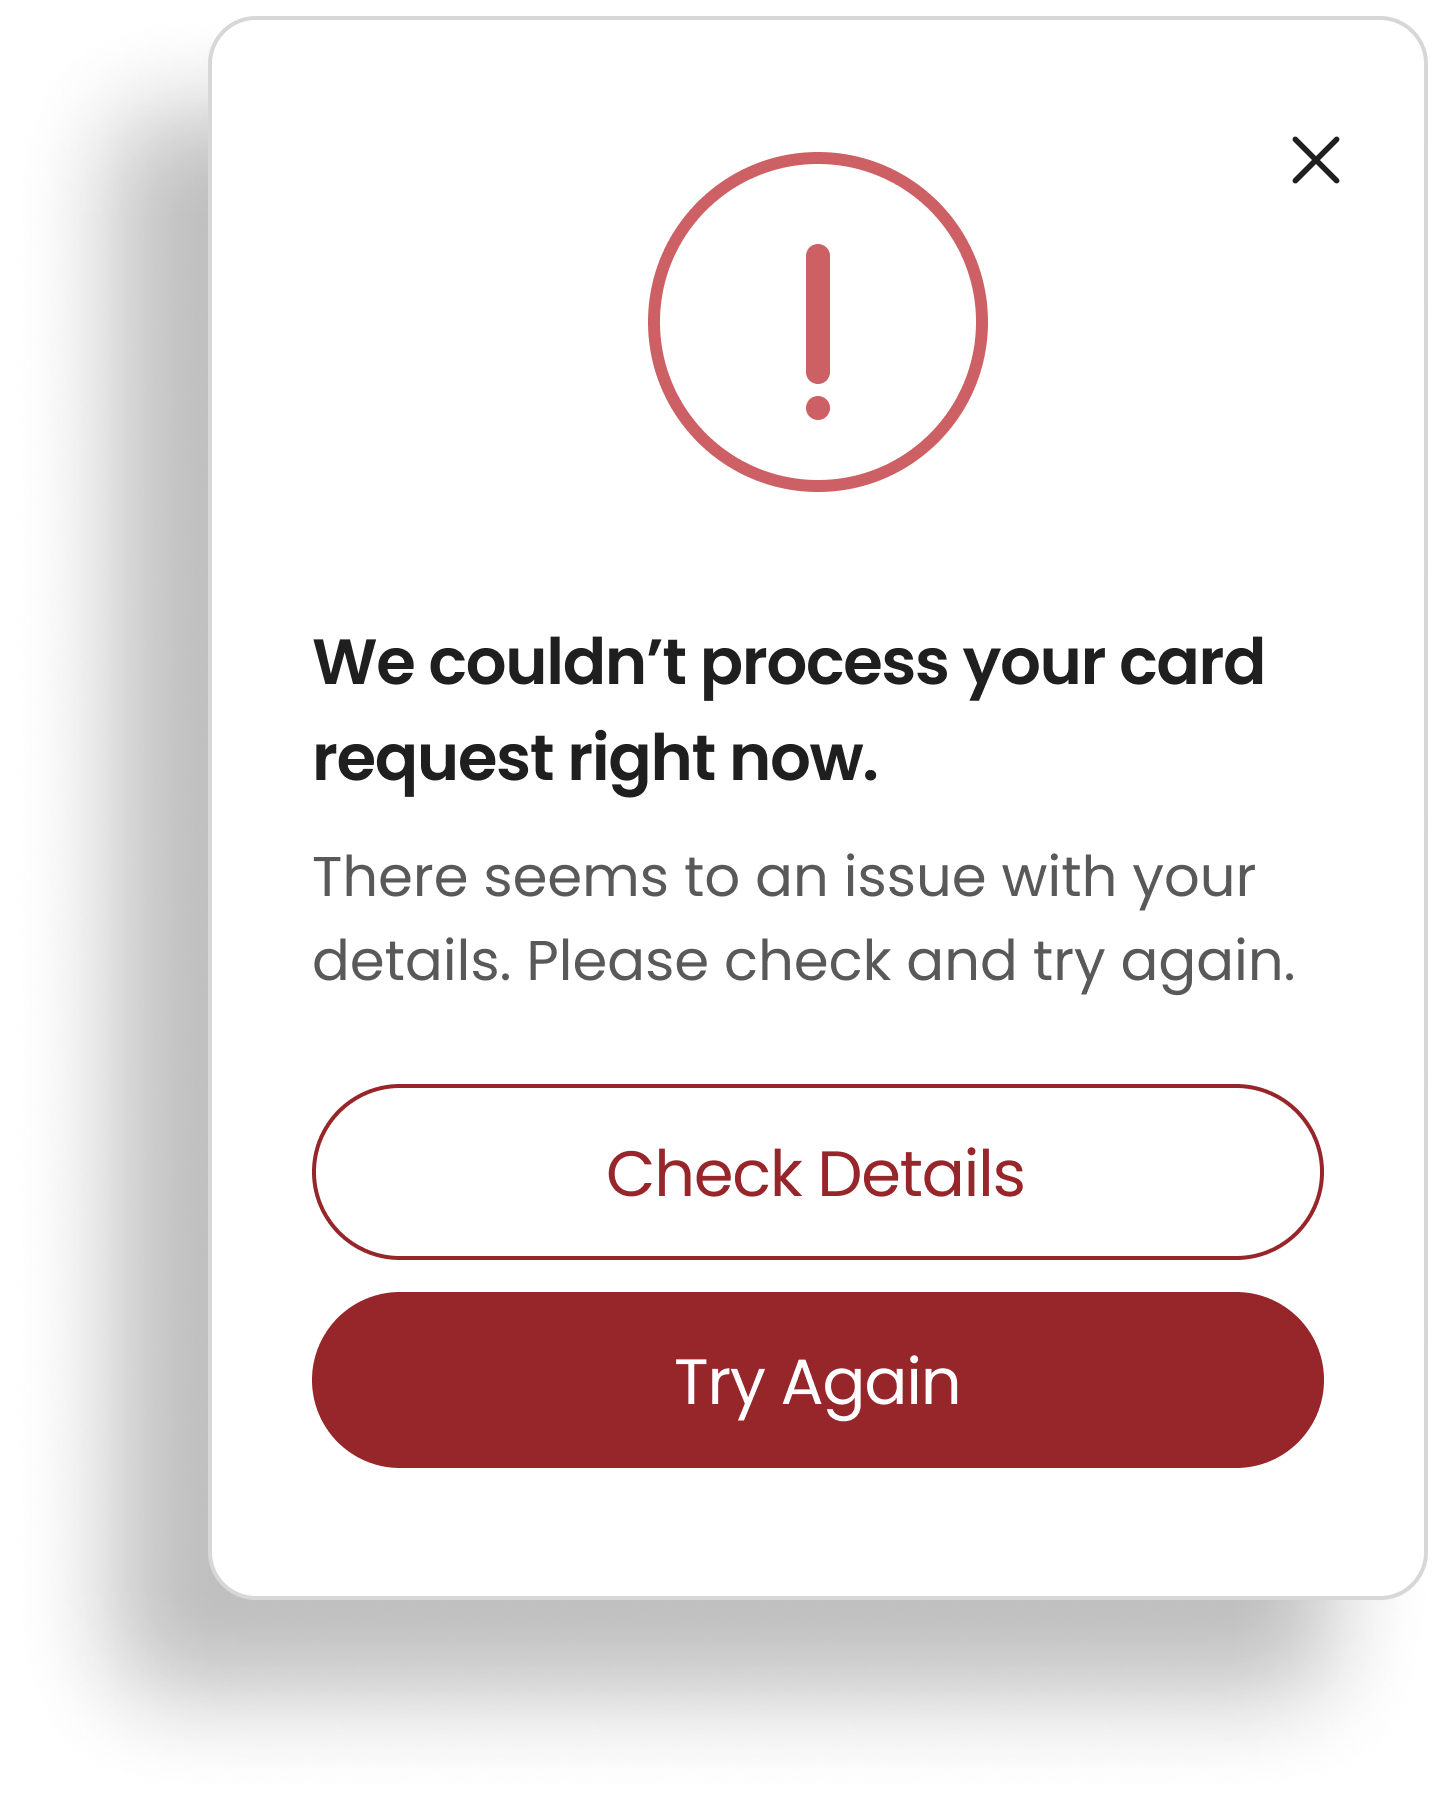
Designing how the product speaks when something goes wrong.
Error states are high-anxiety moments. The goal was to make communication more contextual and actionable, helping users quickly understand what happened and how to move forward.
-
01
What happened?
A clear and specific explanation in simple language.
-
02
What does it mean?
Helps users understand the impact on their request or account.
-
03
What should I do next?
Provides a clear next step, with help options where needed.
Making high-stakes interactions understandable and deliberate.
I remained involved through QA, refinement, and launch to help maintain design integrity, resolve edge cases, and ensure a consistent experience across devices and platforms.
Legibility
Clear type hierarchy and readable content at all screen sizes.
Contrast
Meets accessibility standards for text, icons and components.
Touch targets
Comfortable sizing for key actions across mobile.
Interaction states
Clear feedback for press, loading, empty and disabled states.
Error clarity
Consistent and helpful error patterns across the platform.
Sensitive information
Careful treatment of personal and financial data.
UI review, accessibility checks and edge cases.
Work with engineering to resolve issues.
Partner with product, engineering and compliance.
Support release and monitor post-launch.
07 Validation & Reflection
Evidence first. Reflection after.
The redesign was evaluated through usability research. Where analytics were not available, I deliberately distinguish measured usability evidence from what I would validate in production.
What the research demonstrated.
 LOGIN
n = 22
Rated the task easy.
Average ease rating.
Encountered no difficulty.
 REGISTRATION
n = 22
Rated the journey easy.
Described it as user-friendly with fewer clicks.
 PASSWORD RESET
n = 18
Rated the task easy.
Average ease rating.
Encountered no difficulty.
 DASHBOARD
n = 39
Found viewing savings, loan, and investment information easy.
Experienced a findability gap around important actions.
These metrics would help validate whether the solution drives meaningful improvements at scale beyond the usability study.
 AUTHENTICATION
- First-attempt login success
- mPIN adoption
- OTP failure loops
- Password-reset completion
- Login-related complaint volume
 CARD MANAGEMENT
- First-click success
- Completion of common card controls
- Permanent-block reversals
- Security-control usage
 DASHBOARD
- Transfer discoverability
- Quick Links usage
- Customization behavior
- Task abandonment
- Contextual-offer engagement
The real lesson was not about fewer clicks. It was about where complexity belongs.
It took me a 45-minute bus ride to get home, but I used the time to set up my account. It felt simple, and I didn't get stuck once.
Why wasn't it always like this?
Remove friction caused by recall burden and weak hierarchy.
Keep deliberate friction where consequences are high.
Make financial control feel understandable, not intimidating.
A login screen may look small, but it can determine whether the service is usable.